Alpha Metallurgical Misses Badly As Rising Costs Outrun Recovering Volumes, And 2027 Guidance Locks In The Squeeze
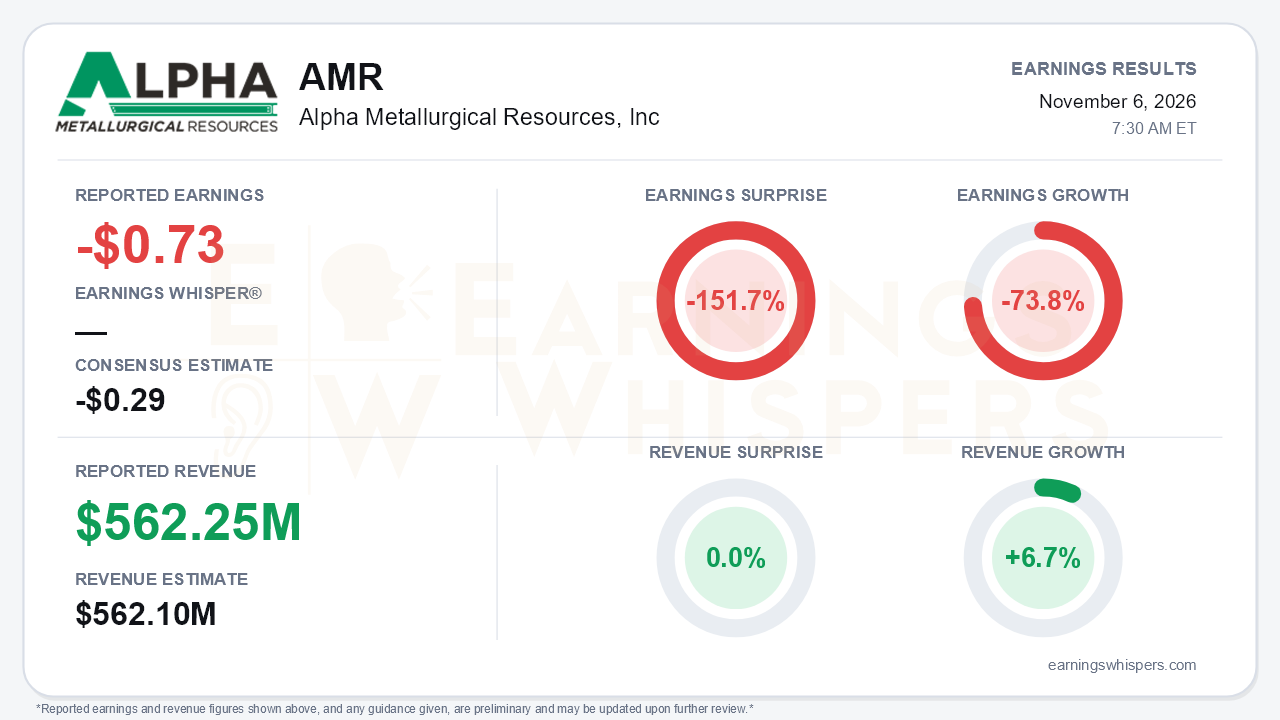
Alpha Metallurgical Resources (NYSE: AMR) posted a third-quarter loss of $0.73 per share, well short of the consensus loss estimate of $0.29. That is a 151.7% negative surprise. Revenue of $562.25 million matched the $562.1 million consensus and rose 6.7% year over year, while earnings fell 73.8% as the loss widened from $0.42 a year earlier. Sequentially the picture is better: the net loss narrowed to $9.3 million from $12.3 million in the second quarter, and Adjusted EBITDA rose to $29.4 million from $25.6 million. That is the central tension. Volumes and pricing recovered, but costs climbed faster, and the 2027 outlook suggests that pressure is not going away.
The quality of the quarter deserves scrutiny. Tons sold rebounded to 3.9 million from 3.5 million, and Met segment realization improved to $121.09 per ton from $118.71. Australian-indexed export tons fetched $150.46, up from $143.82. Cash cost of coal sales, however, rose to $106.93 per ton from $103.07 in Q2 and $97.27 a year ago. As a result, non-GAAP coal margin per ton shrank to $14.16 from $15.64 sequentially and $17.68 a year ago. Total non-GAAP coal margin dollars were essentially flat with Q2 despite roughly 10% more tons shipped, so the extra volume earned AMR almost nothing. Adjusted EBITDA remains well below the $41.7 million of a year ago. Operating cash flow of $46.9 million and lower capex ($33.8 million versus $45.1 million) were genuine bright spots. Even so, liquidity has drifted down to $443.4 million from $524.3 million at year-end.
On the call, the tone was steadier than after Q2's guidance cuts. Shipments recovered despite the June storm damage to a stacker reclaimer at Dominion Terminal Associates (DTA), which shows the workaround through other Hampton Roads terminals is functioning. The 2026 book is now 87% committed and priced, up from 70% last quarter. The Kingston Wildcat low-vol mine is ramping, and management expects several hundred thousand tons of premium low-vol coal to be available for seaborne sale in 2027, part of a multi-year mix shift away from high vol. Management also said input-cost inflation has largely flowed through, and it does not expect material further increases. The average price on committed 2026 tons, however, has slipped every quarter, from $134.02 to $126.69.
The forward-looking disclosures carry the real weight, and bears have legitimate ammunition:
- **Costs:** 2027 cost guidance of $104 to $110 per ton sits above the revised 2026 range of $103 to $107 and far above the original 2026 guide of $95 to $101.
- **Domestic book:** 2027 domestic commitments total 3.5 million tons at $135.48, smaller and cheaper than the 4.1 million tons at $136.30 initially booked for 2026, with more lower-value high vol in the mix.
- **Terminal capacity:** DTA's damaged unit must be fully replaced on roughly a two-year custom build. The insurer is engaged and Alpha expects no significant capital outlay, but management says the constraint caps upside above the 15.7 million-ton top of the 2027 shipment range of 14.3 to 15.7 million tons. That range is only slightly above 2026.
- **Pricing:** The third-quarter index rally (Australian PLV from $244 to $272.10, U.S. East Coast HVA from $157 to $195) was supply-driven amid still-weak steel demand, and it partly reversed after quarter end.
- **Fuel:** Diesel exposure tied to oil and the Iran conflict adds another cost variable.
The market setup is more complicated than the miss implies. Investor sentiment swung sharply, from clearly negative at -0.49 after the prior report to modestly positive at +0.19 heading into this release. Price action tells a harsher story. Shares opened at $147.50 after the August report and surged to an inter-earnings high of $242.50 on September 2, roughly coinciding with the met-coal index rally. They have since given back essentially all of that gain. At $143.27, the stock is down 2.9% since the prior report, sits 21.9% below its 200-day moving average of $183.50, and trades just 1.7% above a quarterly low set the day before earnings. The market had already unwound the price-driven optimism before this report confirmed that costs are absorbing the benefit.
Capital returns provide some cushion. The share count has fallen to roughly 12.66 million after $1.2 billion of repurchases under the $1.5 billion authorization. Year-to-date buybacks have been modest, though, at about $40 million, as liquidity trends lower.
The bottom line is that Alpha delivered a real sequential operating recovery, but not a profitable one. Volume, realization and cash flow improved, yet margin per ton kept shrinking, the EPS miss was wide, and 2027 guidance embeds higher costs, a weaker domestic book and a two-year terminal ceiling. Improved sentiment suggests investors are more willing to look through the trough. With shares near their lows and the index rally fading, a better 2027 depends on Wildcat's low-vol mix and cost discipline rather than on coal prices.
Read our earnings preview for Alpha Metallurgical Resources, Inc: https://www.earningswhispers.com/article/AMR/22466
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 5 hours | |
| 6 hours | |
| Oct-29 | |
| Oct-23 | |
| Oct-23 | |
| Aug-13 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Jul-27 | |
| Jun-18 | |
| May-14 | |
| May-08 |
