Scripps Swings To A Profit On A Record Political Haul, But Networks Erosion And 5.2x Leverage Keep The Thesis Unsettled
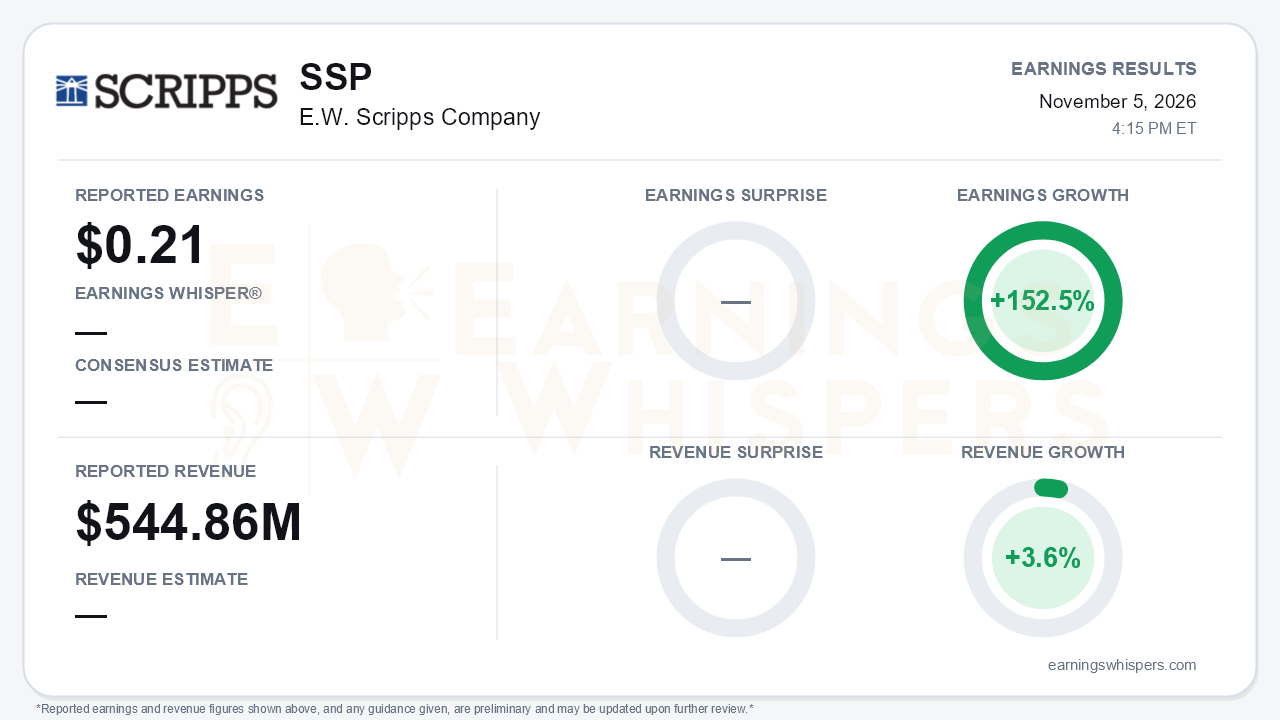
E.W. Scripps returned to profitability in the third quarter. The company earned $0.21 per share, compared with a $0.55 loss a year earlier, which works out to 152.5% earnings growth. Revenue rose 3.6% to $544.86 million. No consensus estimate was available, so the quarter is best judged against management's own targets. On that basis Scripps did well: political revenue, the networks revenue decline and networks expenses all came in better than the guidance given in August. The central tension is that the profit is real but heavily cyclical. Political dollars lifted Local Media, while the Scripps Networks division, which absorbed a $1.1 billion impairment earlier this year, is still shrinking its profit base.
The quality of the earnings deserves scrutiny. Pretax income was only $11.6 million, and a $26.0 million tax benefit turned it into $37.7 million of net income. Preferred dividends of $16.9 million then reduced the amount available to common shareholders. Restructuring costs of $18.8 million cut 14 cents from EPS, a reminder that the transformation is still consuming money. Adjusted EBITDA rose to $121.5 million from $80.4 million. That gain came almost entirely from political advertising: Local Media posted $80.6 million of political revenue versus about $5 million a year ago. Local Media segment profit more than doubled to $118 million. Scripps Networks segment profit, by contrast, fell 41% on an adjusted combined basis to $33 million. Underneath the political surge, Local Media core advertising fell 13% as political ads crowded it out, and adjusted combined distribution revenue was flat.
The call preserved a credible improvement story. Full-year political revenue reached $284 million, above the $225-$250 million guidance and 44% ahead of the 2022 midterm cycle. Networks revenue fell 11%, better than the mid-teens decline management had guided, and the fourth-quarter outlook improves to a high-single-digit decline. Three developments drove the change:
- **Nielsen's Sept. 1 methodology fix.** It lifted ION viewing 7% among adults 25-54 and all Scripps networks 23% in that demographic. Management had excluded this from guidance in the second quarter; the lift has held into October and is now built in.
- **Connected TV.** Revenue growth accelerated to 37%, up from 28% in the second quarter and 26% in the first. Full-year CTV revenue is expected to be about $155 million.
- **Cost savings.** Management reaffirmed the $100 million year-end run-rate savings target, which was originally $75 million, after cutting roughly 20% of the workforce.
Management's tone shifted noticeably, from the second quarter's admission that results did not meet expectations to confident talk about growth in 2027 and 2028.
The forward catalysts center on distribution and deleveraging:
- **Distribution.** Fourth-quarter local distribution revenue is guided up about 4% after contract renewals. Management expects 2027 net distribution to grow at a double-digit rate, helped by improving subscriber churn.
- **Sports inventory.** More than 75% of sports inventory sold in the upfront, with premium inventory held back for the 2027 scatter market.
- **Debt reduction.** Scripps plans to repay at least $150 million of debt in the fourth quarter, directed at its B2 term loan, plus a bond buyback allowance of roughly $30 million.
The bears still have legitimate ammunition:
- **Leverage.** Net leverage rose to 5.2x from 3.9x in the first quarter. Total debt is $2.5 billion, while equity has shrunk to $142.6 million after the impairment.
- **Preferred dividends.** Unpaid cumulative preferred dividends to Berkshire Hathaway reached $166 million and compound at 9%. Common shareholders cannot receive dividends or buybacks until those preferred shares are redeemed.
- **Advertising softness.** Direct-response advertising remains weak because of low consumer confidence, and it is the main drag on the fourth-quarter networks outlook.
- **Organic distribution.** Excluding blackouts, distribution growth is roughly flat in 2026.
- **Other risks.** Management said the election outcome adds uncertainty to large-scale M&A, and cutting about 850 roles raises execution risk.
Investors have barely moved. Sentiment stayed slightly negative, edging from -0.042 to -0.029, which is effectively unchanged. The stock closed at $2.95, up 2.8% from the $2.87 opening after the August report. Shares remain 13.1% below their 200-day moving average of $3.40. That pricing reflects a market still discounting the balance sheet and the networks decline rather than rewarding an election-year profit that will not repeat in 2027.
The bottom line is that Scripps delivered a better quarter than its own guidance implied. The Nielsen fix, accelerating CTV growth and a cost base that should start shrinking in the fourth quarter make 2027 look less precarious than it did in August. Still, the swing to a profit rests on political revenue and a tax benefit, networks profit is still contracting, and leverage has risen. Whether the fourth-quarter debt paydown and the promised 2027 distribution growth actually materialize will matter more to the equity than this quarter's earnings.
Read our earnings preview for E.W. Scripps Company: https://www.earningswhispers.com/article/SSP/22390
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-06 | |
| Sep-28 | |
| Sep-09 | |
| Sep-08 | |
| Aug-27 | |
| Aug-14 | |
| Aug-07 | |
| Aug-07 |
