Goldman Sachs BDC Misses As Rising Non-Accruals And A Shrinking Portfolio Leave The $0.32 Base Dividend With No Cushion
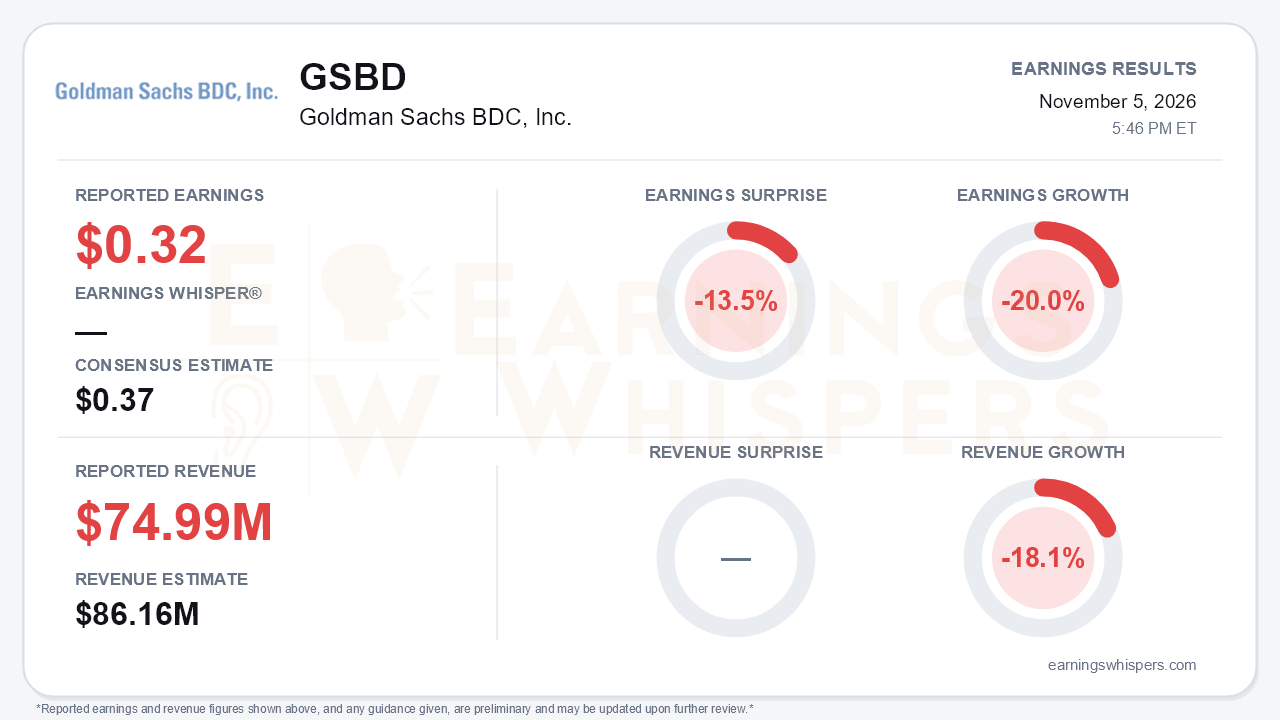
Goldman Sachs BDC (NYSE: GSBD) reported third-quarter net investment income of $0.32 per share, missing the $0.37 consensus by 13.5% and falling 20.0% from a year ago. Total investment income of $74.99 million came in 13.0% below the $86.16 million consensus and declined 18.1% year over year. On a GAAP basis the quarter swung to a loss of $(0.04) per share, compared with $0.22 in the year-ago period, as $39.2 million of net realized and unrealized losses more than wiped out investment income. The central development is not the size of the miss. It is that GSBD is now shrinking its earnings base while credit quality deteriorates. That combination leaves NII exactly equal to the newly declared $0.32 base dividend, with nothing left over.
The quality of the quarter deserves scrutiny. Non-accruals jumped to 4.2% of the portfolio at fair value from 2.9% in June, and to 7.3% at amortized cost from 5.0%. Four names went on non-accrual during the quarter: Center for Sight Management, HungerRush, and additional positions in ATX Networks and Streamland Media. Only one, Senneca Holdings, returned to accrual status, leaving 11 portfolio companies on non-accrual. NAV per share fell 3.0% to $11.70 from $12.06, extending a slide from $12.64 at year-end 2025. Underlying portfolio metrics also softened since December:
- weighted average net leverage rose to 6.3x from 5.9x;
- interest coverage slipped to 1.9x from 2.0x;
- yield at amortized cost eased to 9.7% from 9.9%.
The jump in fair-value yield to 11.9% from 10.9% mainly reflects marked-down loan prices rather than better economics. Notably, GSBD recorded zero incentive fees this quarter, versus $7.1 million a year ago. NII reached $0.32 only with no incentive fee in the expense line, so that lever offers no further relief if income keeps falling.
The balance-sheet story is deliberate deleveraging. Sales and repayments totaled $371.2 million against just $40.5 million of new commitments, producing net funded activity of $(307.5) million. The portfolio's amortized cost dropped to $3.11 billion from $3.41 billion. Net debt-to-equity fell to 1.21x from 1.35x, consistent with the roughly 1.2x pro forma level management flagged last quarter. Liquidity is ample: $1.01 billion of revolver availability and $83.5 million of cash. The cost is visible in the income statement. Investment income dropped by $8.7 million sequentially, while net expenses fell only $1.9 million. Interest expense of $29.1 million was actually higher than the $28.1 million of a year ago. Part of the sequential NII decline is normalization, since the second quarter's $0.38 included roughly $5 million of one-time income. Even so, the earnings power left after the cleanup is lower.
Management commentary from the November 6 call cannot be verified, because a usable transcript was not available. As a result, there is no confirmation of how management views redeployment pace, spreads, or the outlook for the newly non-accruing names. What the release does show is follow-through on last quarter's stated intent. GSBD activated a $75 million 10b5-1 repurchase plan and bought back about 1.5 million shares for $15.0 million. New commitments of $40.5 million, spread across seven new and seven existing borrowers, were an improvement on the second quarter's very light $12.9 million but remain far below the pace needed to rebuild the portfolio. Two other points matter for the outlook:
- spillover income, last cited at $0.89 per share, gives the board some flexibility on distributions;
- no supplemental dividend was declared this quarter, after $0.03 last quarter.
Leadership transition is also on the calendar, with co-CEO David Miller stepping down at year-end.
Investor sentiment moved from essentially neutral to moderately positive, a meaningful shift for a quarter with these credit trends. It likely reflects income-oriented holders focused on the reduced leverage and the buyback rather than on the non-accrual increase. The stock tells a more cautious story. At $8.80, shares are down 2.2% since the open after the prior report and sit 4.9% below their 200-day moving average of $9.26. That price is roughly a 25% discount to the $11.70 NAV, so the market is already pricing in further credit erosion. The discount also makes continued buybacks accretive.
The bottom line is that GSBD traded earnings for balance-sheet safety, and credit did not cooperate. Lower leverage, ample liquidity and a deep NAV discount give bulls a defensible floor. Bears, however, have legitimate ammunition: non-accruals at 7.3% of cost, a third consecutive NAV decline, and NII that only just covers a $0.32 base dividend with incentive fees already at zero. Whether the redeployment capacity created this quarter can stabilize income before more loans weaken will decide whether the dividend holds.
Read our earnings preview for Goldman Sachs BDC, Inc.: https://www.earningswhispers.com/article/GSBD/22299
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-05 | |
| Aug-06 | |
| Aug-06 | |
| Jul-07 | |
| May-07 | |
| May-07 | |
| Apr-14 | |
| Mar-04 | |
| Feb-28 | |
| Feb-27 | |
| Feb-26 |
