Skyward Specialty Beats Consensus But Misses The Whisper As Growth, Pricing And Fee Momentum Cool
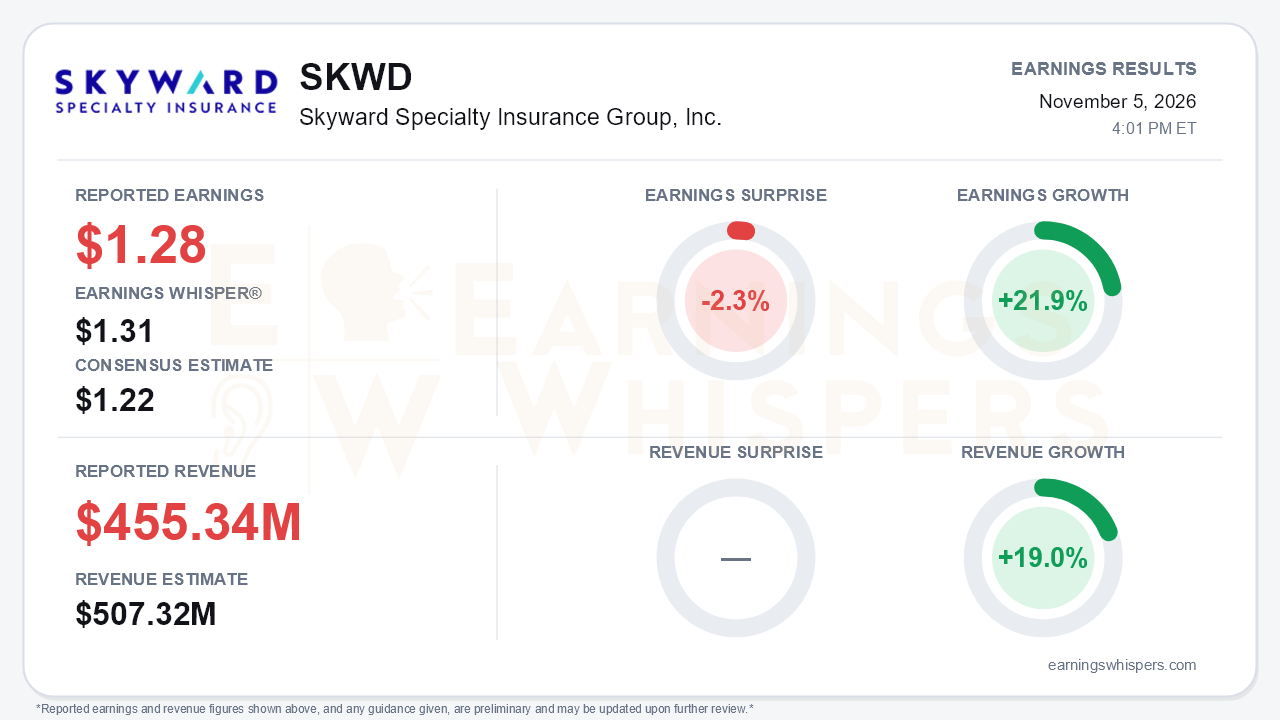
Skyward Specialty Insurance Group (NASDAQ: SKWD) reported third-quarter operating earnings of $1.28 per share. That was above the $1.22 consensus but short of the $1.31 Earnings Whisper number, a 2.3% miss against the bar that mattered. Revenue of $455.34 million fell 10.2% below the $507.32 million consensus estimate. Year over year, earnings grew 21.9% and revenue grew 19.0%, but those comparisons are flattered by the Apollo acquisition. The central tension is that Skyward remains a highly profitable specialty underwriter while nearly every growth gauge it reports slowed. Investors who bought the Apollo story for compounding top-line momentum got a quarter about deceleration.
The quality of the beat deserves scrutiny. GAAP diluted EPS was $1.09, essentially flat with $1.10 a year ago. Acquisition-related amortization rose to $8.8 million from $0.5 million, interest expense climbed to $7.0 million from $1.9 million, and realized gains disappeared. Net investment income did much of the work, rising to $33.9 million from $22.0 million on the larger Apollo portfolio and a 6.4% new-money yield. Operating EPS slipped from $1.30 in the second quarter.
Underwriting stayed solid at a consolidated 89.9% combined ratio, with an 88.1% ex-cat ratio, though that was a touch higher than the second quarter's 89.5%. The Skyward Specialty segment's combined ratio deteriorated to 88.3% from 86.9% sequentially. Its loss ratio rose 1.8 points year over year on mix shift toward accident & health and agriculture. Apollo was the bright spot, improving to 90.5% from 97.6% as cat losses eased. Below the line, a $47.7 million unrealized investment loss cut comprehensive income to just $2.7 million. Equity rose only 0.7% sequentially, and book value per share edged up to $28.74 from $28.55.
The call laid out the slowdown plainly. Gross written premiums grew 9%, down from 13% in the second quarter and 10% in the first. Fee-generating premiums grew 18%, versus 29% and 49% in the prior two quarters, and underwriting fee income dipped to $11 million from $13 million. Lower dairy livestock take-up, as diesel and input costs squeezed farmers, forced earned-premium true-ups. Those adjustments pulled net earned premium down to roughly $407 million from about $445 million in the second quarter, which largely explains the revenue miss. Management also trimmed expected 2026-27 treaty-year premium and could not say whether the issue is one-off.
Pricing is softening too:
- Pure rate excluding property fell to mid-single digits from high single digits.
- Apollo rate turned slightly negative.
- E&S property hit ratios fell by a third, with average premium down 20%.
- Primary liability retention dropped 6 points.
Management called out irresponsible competitor terms in casualty and expects fourth-quarter competition to intensify. Bears have legitimate ammunition here.
The call still preserved a credible growth story. Management said full-year gross written premiums are tracking near the upper end of the $2.65-$2.8 billion range. Submissions accelerated to the low-20s percent, including E&S property up 60% and excess up 32%. Accident & health grew 57%, and Skyward's year-to-date segment expense ratio improved 1.7 points to 25.4%. New initiatives include:
- the U.S. launch of iBott;
- a founding investment in AI-native embedded platform Slingshot;
- two new partner syndicates, including Generali, with a pipeline into 2027;
- a roughly $20 million surety team lift-out.
Management also hinted at more autonomy-related announcements. IBNR reached a record 77% of reserves. Even so, exited commercial auto and claims-made professional liability remain under pressure ahead of a fourth-quarter ground-up reserve review. The CFO is retiring in March 2027, and buybacks paused in favor of debt paydown.
Investor sentiment, already negative, deteriorated further from -0.28 to -0.40, a meaningful but not dramatic shift. The stock tells a calmer story. Shares have gained only 1.4% since the open after the August report, but at $63.86 they sit about 23% above the 200-day moving average. The market has held onto prior gains even as sentiment soured, which leaves room for disappointment if the deceleration persists.
The bottom line is that Skyward delivered strong absolute profitability and a credible pipeline of new initiatives, but the quarter marks a clear shift from acceleration to moderation. Premium growth, fee momentum, rate adequacy and earned premium all softened, and GAAP earnings were flat once acquisition costs are counted. Whether the agriculture true-up proves isolated and the fourth-quarter reserve review comes in clean will likely determine whether this is a pause or the start of a softer cycle.
Read our earnings preview for Skyward Specialty Insurance Group, Inc.: https://www.earningswhispers.com/article/SKWD/22382
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Oct-08 | |
| Sep-30 | |
| Sep-08 | |
| Aug-20 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 |
