Orion (ONL) Raises Core FFO Guidance Again As Leasing Momentum Offsets A Shrinking Rent Base, But Q4 Looks Softer
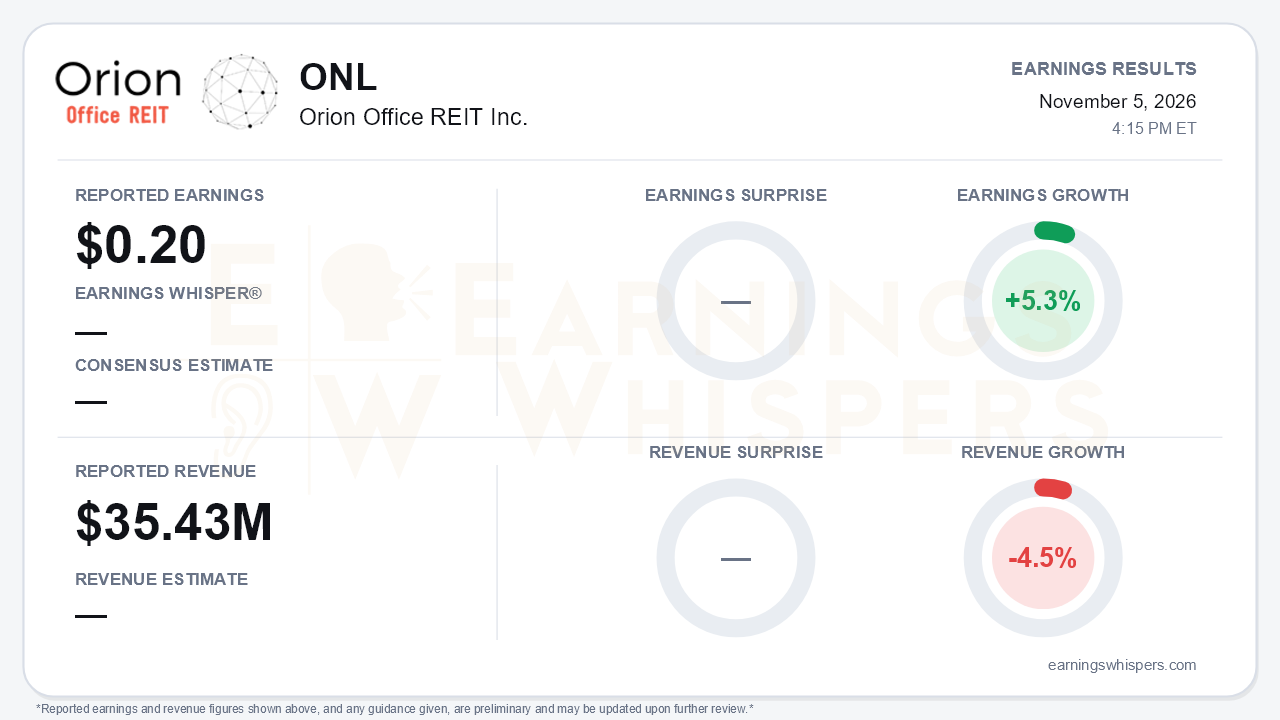
Orion (NYSE: ONL), identified in the release as Orion Properties Inc., reported third-quarter Core FFO of $0.20 per share. That was up 5.3% from a year ago, while revenue fell 4.5% to $35.43 million. No consensus estimate or Earnings Whisper number was available, so the quarter has to be judged on its own trajectory. On that basis, the most important development was not the penny of year-over-year growth. It was management's second consecutive increase to full-year guidance. Core FFO guidance moved to $0.75-$0.78 from $0.72-$0.77 last quarter and $0.69-$0.76 at the start of the year. The leverage target also improved to 5.8x-6.4x from 6.0x-6.8x, versus an original 6.5x-7.3x. The central tension is that per-share earnings are edging higher while the revenue base keeps contracting.
The quality of the beat-versus-last-year deserves some scrutiny. Core FFO rose largely through cost and capital-structure relief rather than top-line growth. Property operating expenses fell to $14.3 million from $17.3 million, and net interest expense dropped to $7.1 million from $7.9 million as principal outstanding fell to $436.5 million. Adjusted EBITDA, however, slipped to $16.5 million from $17.4 million a year ago and $17.2 million in the second quarter. Straight-line rent also fell to $3.1 million from $4.9 million. The GAAP picture improved dramatically, with the net loss narrowing to $(0.06) per share from $(1.23). That improvement mostly reflects the absence of last year's $63.7 million impairment, not a step change in operations. Funds available for distribution turned positive at $0.02 per share versus $(0.22). That swing came mainly because capital expenditures and leasing costs fell to $6.9 million from $18.3 million, and year-to-date FAD remains negative at $(0.07).
The call preserved a credible leasing story. Year-to-date leasing reached 922,000 square feet, up from 673,000 at the second-quarter call, keeping Orion on pace for another year above one million square feet. Third-quarter renewal spreads were +25%, a sharp reversal from -7.7% in the prior quarter. Occupancy reached 78.3%, up from 72.1% a year ago. Dedicated use assets climbed to 40.6% of annualized base rent from 35.8% at year-end, advancing the stated shift away from traditional office. Post-quarter deals brought Plano to 85% leased, extended 65,000 square feet in Milwaukee for 10.3 years, and renewed the full Indianapolis building. Management also expects a 93,000-square-foot, 15-year lease in Buffalo during the fourth quarter. That deal would take a property that was empty a year ago to 64% leased.
Bears still have legitimate ammunition. The raised guidance implies a meaningful fourth-quarter slowdown. With $0.61 of Core FFO already booked through nine months, the range points to a quarter well below the third quarter's $0.20, roughly $0.14-$0.17 on simple arithmetic. Management linked part of the third-quarter strength to one-time lease termination and tax items that are not expected to recur. Other metrics also moved the wrong way:
- AT&T is vacating the Richardson, Texas asset, which is being marketed for sale.
- Full-year capex is now expected in the mid-$40 millions plus leasing commissions.
- Weighted average lease term slipped to 6.1 years from 6.2.
- The leasing pipeline eased to about 1.0 million square feet from more than 1.1 million.
- Net debt to Adjusted EBITDA ticked up to 5.6x from 5.4x in the second quarter, though it remains well below the 6.64x at year-end.
The strategic review, launched in January, is the overhang that matters most for the equity. Management said explicitly that the rise in Treasury rates has further slowed the process and offered no assurance of a transaction. Review costs also rose to $266,000 in the quarter from roughly $100,000. Rates have injected uncertainty into the disposition market as well, although two properties are under contract for $9.5 million. The unconsolidated joint venture remains in payment default on its mortgage, though Orion has written that investment down to zero. Liquidity of $177.2 million and no maturities before the February 2028 revolver deadline give the company time.
Market context is thin for this report. Current investor sentiment and post-report pricing data were not available. Shares opened at $2.79 after the August report, and the 200-day moving average stands at $2.57. The $0.02 quarterly dividend signals that management is still prioritizing balance-sheet repair and leasing capital over payouts.
The bottom line is that Orion delivered another quarter of operational progress, with rising occupancy, strongly positive renewal spreads, and twice-raised guidance. The headline growth, though, rests more on cost cuts and deleveraging than on rent growth, and the outlook implies a softer fourth quarter. Leasing execution is improving, but the investment case still hinges on a strategic review that higher rates are making harder to complete.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Oct-13 | |
| Aug-07 | |
| Aug-06 | |
| Jul-14 | |
| May-07 | |
| Apr-13 | |
| Mar-06 | |
| Mar-06 | |
| Mar-05 | |
| Feb-19 | |
| Jan-27 | |
| Jan-26 | |
| Jan-15 |
