Mach Natural Resources Beats On EPS, But A $0.22 Distribution And A Reinvestment Overshoot Mark A Cash-Return Trough
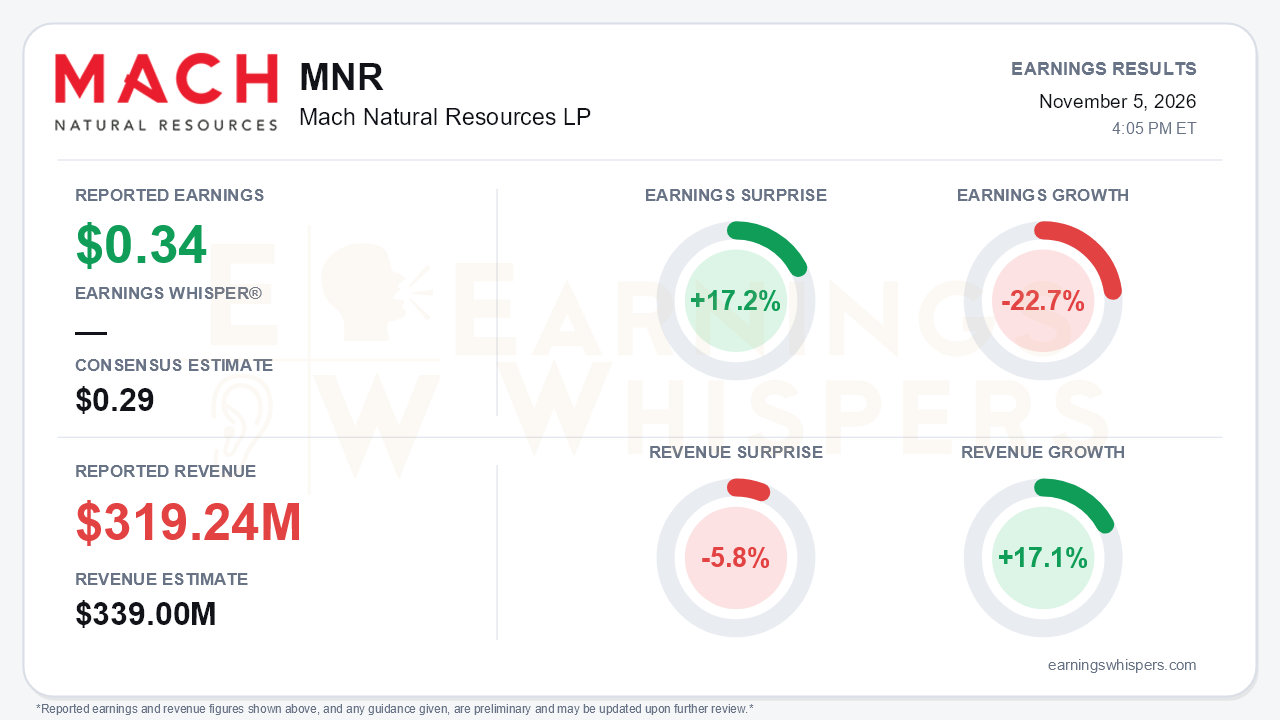
Mach Natural Resources (NYSE: MNR) cleared the earnings bar in the third quarter. It reported $0.34 per unit against a $0.29 consensus, a 17.2% surprise. That beat is not the story investors will focus on. Earnings fell 22.7% year over year, revenue of $319.24 million missed consensus by 5.8%, and the distribution fell to $0.22 per unit from $0.36 in Q2 and $0.64 in Q1. For a partnership whose pitch is maximum cash returns, the payout is the scorecard. On that measure, this quarter looks like a trough.
The headline numbers need context. Revenue grew 17.1% year over year, but it fell sharply from roughly $406 million in Q2. Production slipped to 147 Mboe/d from 149 in Q2 and 158 in Q1. Realized oil prices also fell. The release cites $85.84 per barrel, while the call analysis references $84.84; either figure is well below Q2's $95.40.
On a GAAP basis, net income was $10 million, versus a $35.7 million loss a year ago. That swing flatters the comparison, because the prior-year quarter absorbed a $90.4 million impairment. This year's quarter carried a $46.9 million unrealized derivative loss. Adjusted EBITDA of $183 million was essentially flat with Q2's $182 million, and operating cash flow improved to $165 million from $154 million.
The gap between earnings and payout comes from spending. Cash available for distribution dropped to $38 million from $60 million in Q2 and $107 million in Q1. Development costs of $126 million consumed about 77% of operating cash flow in the quarter. That pushed year-to-date reinvestment to 59%, breaching the company's own sub-50% pillar after management described itself as "right on top of 50%" at Q2.
There was genuine progress on costs:
- Lease operating expense fell to $6.49 per Boe from $7.21 in Q2.
- Cash G&A dropped to $0.44 per Boe from $0.54.
- Realized gas edged up to $2.17 per Mcf from $1.93.
Those gains were outweighed by lower volumes, weaker oil pricing and the capital overrun.
Management's answer is to cut spending. Post-quarter, Mach dropped from three operated rigs to one Oswego rig. CEO Tom Ward said the company remains positioned to bring full-year reinvestment under 50%, which implies a very light Q4 capital program. He promised a "significant increase" in the Q4 per-unit distribution, with higher payouts expected in February and May 2027. Management also cited analyst 2027 cash-available estimates of $2.00 to $2.50 per unit, roughly a 20% yield at current prices, and reaffirmed a preference for a 100% payout.
The 2027 framework calls for:
- $275 million to $325 million of capital.
- Two oil rigs focused on Oswego.
- Seven Mancos completions in Q2 and Q3, conditional on gas prices.
- Production of 134 to 142 Mboe/d.
Management characterized that output as roughly flat within about 5%. Investors should note, however, that the entire range sits below the Q3 run rate of 147 Mboe/d.
Bears have legitimate ammunition beyond the payout. Oilfield inflation is surfacing, with diesel and related costs up 30% to 50% quarter over quarter and the 2027 Oswego drilling AFE raised 11%. Gas drilling is halted, and management warned winter gas prices could go "dramatically lower." Credit-facility availability has declined every quarter, from $338 million to $250 million, with $31 million of cash. Year-end leverage is still projected at 1.4x.
The tone on deleveraging also shifted. At Q2, management framed 2027 as a year to bring leverage down, potentially through ATM issuance or retained distributions. On this call it effectively signaled no hurry, leaning instead on gas prices above $3. Acquisitions, historically Mach's growth engine, remain frozen by aggressive oil bids and gas bid-ask gaps. The longer-term gas thesis — 15 Bcf/d of demand growth by 2028 and San Juan westbound takeaway ahead of a 2030 contract roll-off — is real optionality, but it is distant.
The market had already been punishing the unit price. Shares have fallen 23.2% since the open following the August report to $9.94. That leaves them about 21.3% below the 200-day moving average of $12.63. Investor sentiment moved from essentially neutral (0.03) to clearly negative (-0.24), a meaningful deterioration. Management acknowledged the weakness, framing the implied yield as roughly 20% against a historical 10% to 15% range. That is an argument for value, but it also reflects investor doubt about the durability of the cash stream.
The bottom line is that the EPS beat masks a quarter in which Mach's core promise slipped. Distributions fell again, reinvestment overshot its ceiling, liquidity tightened and the commitment to deleveraging softened. The Q4 rig cut and a promised distribution rebound give the story a credible near-term repair path. With 2027 production guided below the current run rate, inflation rising and gas exposure on hold, the next two distributions will show whether this was a trough or a reset to a lower baseline.
Read our earnings preview for Mach Natural Resources LP: https://www.earningswhispers.com/article/MNR/22338
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| Oct-28 | |
| Oct-22 | |
| Aug-17 | |
| Aug-07 | |
| Aug-04 | |
| Jul-31 | |
| Jul-23 | |
| Jul-08 | |
| May-21 | |
| May-07 | |
| May-07 | |
| May-06 | |
| Apr-23 | |
| Apr-13 |
