Global Partners Misses Badly As Wholesale Strength Masks A Sequential Step-Down And Softening Retail Fuel Demand
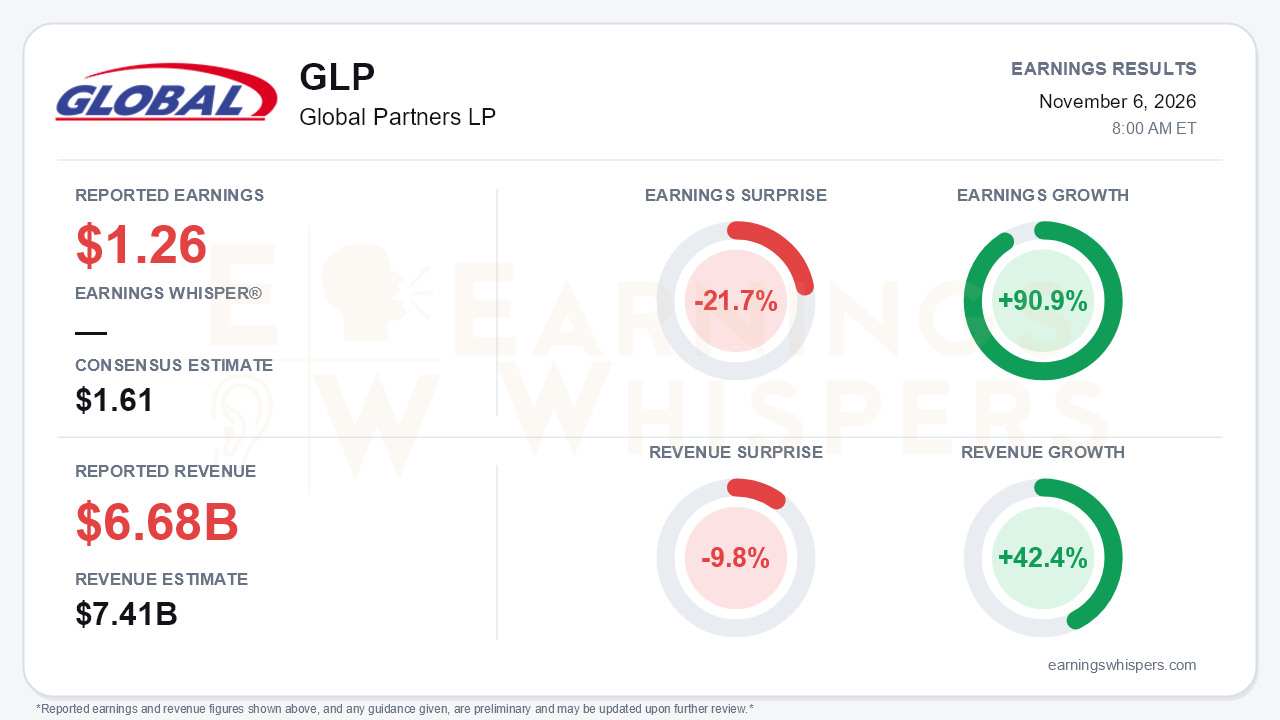
Global Partners LP (NYSE: GLP) delivered a quarter that looks strong against last year but weak against expectations and against its own recent run rate. The partnership earned $1.26 per diluted common unit on revenue of $6.684 billion, missing the $1.61 consensus by 21.7% and the $7.41 billion revenue estimate by 9.8%. On a year-over-year basis, earnings grew 90.9% and revenue rose 42.4%, with net income climbing to $52.4 million from $29.0 million. That is the central tension: the year-over-year comparison flatters a business that just stepped down meaningfully from its first-half peak, and the retail engine that powered earlier gains has started to sputter.
The quality of the beat-versus-prior-year deserves scrutiny. Revenue growth was driven by price, not throughput. Total volume was flat at 1.9 billion gallons, while GDSO volume fell to 361.3 million gallons from 390.8 million and Commercial volume dropped to 124.7 million from 149.2 million. Per-unit results were also modestly reduced by a $2.8 million charge tied to the July redemption of the Series B preferred units, which came out of income attributable to common unitholders. Sequentially, the picture is plainly weaker. Adjusted EBITDA of $122.9 million compares with $148.2 million in Q2 and $140.4 million in Q1, and adjusted distributable cash flow fell to $70.3 million from $92.5 million and $96.8 million in the prior two quarters. The partnership remains well ahead of 2025, but the growth trajectory has clearly decelerated from the first half.
Beneath the headline, the earnings mix flipped. Wholesale carried the quarter, with product margin up $33.4 million year over year to $111.4 million, a much larger gain than the $14.8 million improvement in Q2. Distillates were the swing factor, posting a $19.1 million year-over-year increase after declining $4.8 million in Q2, while gasoline blendstocks improved on more favorable market conditions. GDSO moved the other way. Segment product margin fell $8.3 million to $210.6 million, reversing gains of $17.7 million, $11.4 million and $37.3 million in the prior three quarters. Gasoline distribution margin declined to $136.8 million on lower volume. Unlike prior calls, management did not disclose a cents-per-gallon fuel margin, which leaves investors with less visibility into retail unit economics just as that business softens.
The demand commentary has deteriorated across the year. In Q1, management flagged slightly smaller fill-ups. In Q2, it called the impact not material. On this call, it said consumers were "definitely" conserving fuel. Convenience-store transactions declined, and only larger basket sizes kept store sales flat. Several other details give bears legitimate ammunition. The GDSO site count keeps shrinking, from 1,524 at the end of 2025 to 1,489. SG&A rose on wages and incentive compensation. Maintenance capex guidance was raised by $5 million to $65-75 million. Management also warned that steep backwardation should raise the cost of carrying hedged inventory. The wholesale outperformance depended on favorable market conditions, which are inherently less durable than steady retail margin.
The balance-sheet story, by contrast, remains a credible support for unitholders. Leverage improved to roughly 2.8x from 3.59x at the end of 2025. Distribution coverage rose to 2.3x from 1.56x over the same span. The 9.5% Series B preferred, $75 million in total, has been retired, and the credit facility now runs to October 2031. The distribution was raised for a 20th straight quarter to $0.785, or $3.14 annualized. Management described M&A activity as "very busy," noting that retail remains fragmented while terminal deals are fewer but larger. With balance-sheet capacity in hand, acquisitions are a plausible catalyst, though management offered no specific transaction.
The market had already been leaning bearish before the release. Shares fell 15.3% from the $49.17 open after the August report to $41.67, sitting 13.2% below the 200-day moving average. After touching a 52-week high of $54.29 on September 10, the stock gave back the entire move and entered earnings essentially at its inter-earnings low of $41.58. Investor sentiment moved the other way, rising from roughly neutral at 0.06 to a moderately positive 0.39. That divergence suggests investors were warming to the yield, coverage and deleveraging story even as the price discounted weaker fuel fundamentals. A sizable miss against consensus tests that optimism.
The bottom line is that Global Partners' quarter was strong relative to a soft 2025 comparison but disappointing relative to expectations and to its own first-half pace. Wholesale volatility rescued results while retail volume, store traffic and site count all moved in the wrong direction. The balance sheet, coverage and distribution growth give unitholders a real cushion. Still, the sequential cash-flow decline and worsening demand language mean the next leg of the story depends on whether retail fuel demand stabilizes or wholesale conditions stay favorable.
Read our earnings preview for Global Partners LP: https://www.earningswhispers.com/article/GLP/22487
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 12 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-23 | |
| Sep-18 | |
| Sep-11 | |
| Sep-03 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Jul-31 | |
| Jul-29 | |
| Jul-24 |
