Galiano Gold Misses On Adjusted EPS, But Its Q3 Operating Inflection And Expiring Hedges Shift Focus To 2027
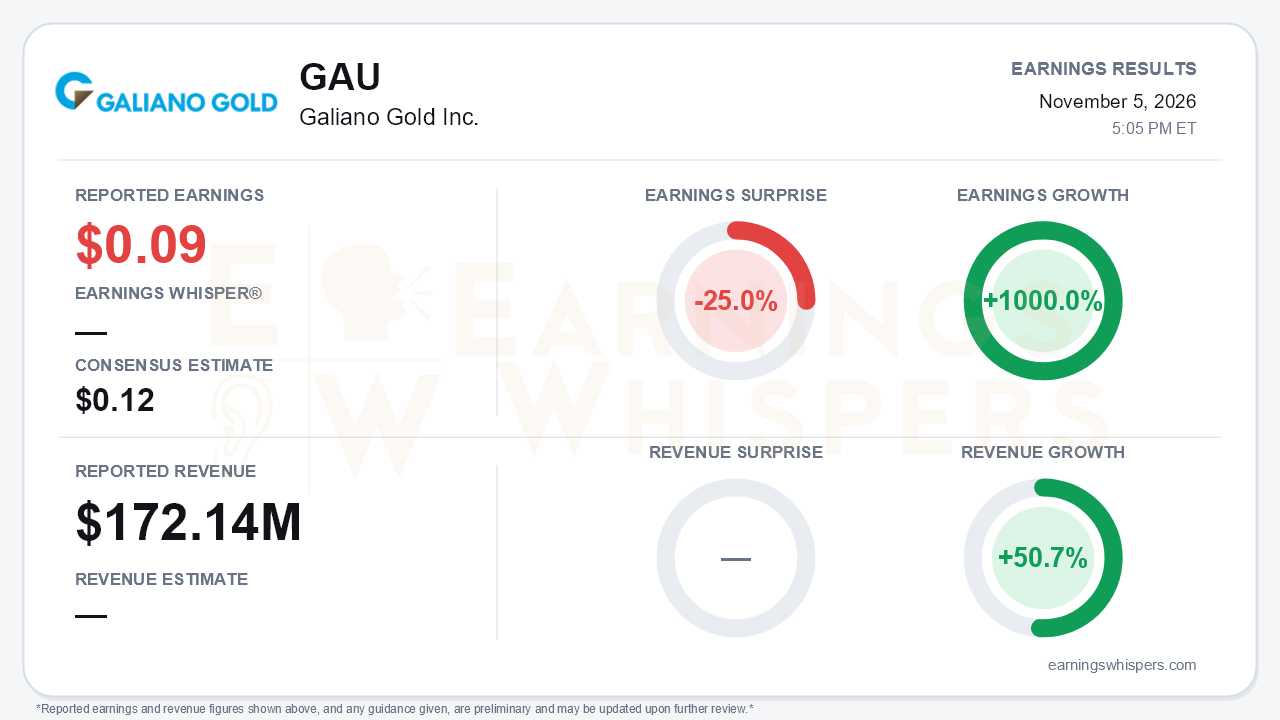
Galiano Gold's third quarter looked like a miss on the headline but an operational step forward. The Asanko Gold Mine operator reported adjusted earnings of $0.09 per share, short of the $0.12 consensus by 25.0%. Revenue rose 50.7% year over year to $172.14 million, and earnings grew 1000.0% from a year-ago adjusted loss of $0.01 per share. On a GAAP basis, the turnaround was starker: net income attributable to shareholders was $40.5 million, or $0.15 per share, compared with a $38.6 million loss a year earlier. The central tension is that the mine finally delivered the second-half grade and throughput improvement management had promised, yet the hedge book, royalties and heavy pre-stripping spending kept that improvement from showing up in per-share earnings or the cash balance.
The quality of the miss deserves scrutiny, because operations were not the problem. Gold production rose 19% sequentially to 40,922 ounces. Mill throughput climbed 11% to 1.4 Mt, and head grade improved to 1.0 g/t as deeper, higher-grade benches at Abore came into the feed. AISC fell 5% to $2,346 per ounce. Adjusted EBITDA rose to $93.3 million from $78.5 million in Q2.
The drag sat below the operating line:
- **Hedging losses.** The gross realized price was $4,247 per ounce, but the net price after hedging losses was only $3,557, a gap of roughly $690 per ounce.
- **Lower gold prices.** The gross price itself slipped from $4,432 in Q2.
- **Higher royalties.** Ghana's sliding-scale royalty has been in effect since March.
As a result, income from mine operations fell to $72.2 million from $92.8 million in Q2. Adjusted net income was essentially flat sequentially at $23.2 million despite 15% more ounces sold.
The call reinforced that underlying costs are behaving. Year-to-date AISC of $2,391 per ounce sits in the lower half of the $2,300–$2,600 range. That range was reset upward from $2,000–$2,300 earlier in the year to reflect the new royalty regime. Nkran Cut 3 waste movement jumped 40% to 8.5 Mt as additional equipment arrived, and unit mining costs there fell to $2.87 per tonne from $3.58. Not everything moved the right way, though. Processing costs rose 10% to $15.40 per tonne on mill liner and crusher maintenance, and sustaining capital increased for the tailings facility expansion. Management also flagged three ongoing cost pressures:
- unhedged diesel exposure tied to the Middle East conflict;
- Ghanaian labour costs expected to edge higher in 2027;
- a throughput-versus-grade trade-off from hard Abore ore.
Guidance of 140,000–160,000 ounces was reaffirmed rather than raised. With about 110,000 ounces produced year to date, the range implies a wide Q4 window of roughly 30,000–50,000 ounces.
The forward story is where the setup genuinely changed. Only 15,000 hedged ounces remain, all to be settled in Q4. Management explicitly anticipates a significant cash-flow inflection in 2027 once Galiano gains full gold-price exposure. The Abirem and Miradani mining leases were extended through 2041 and 2043, covering Nkran and the processing plant. The Abore underground exploration adit is now fully permitted, an advance from Q2, when management was only targeting a 2027 investment decision. The Esaase infill program is complete, feeding a reserve and resource update due in Q1 2027.
Bears still have legitimate ammunition:
- **Shrinking cash.** Cash fell to $86.8 million from $105.9 million at Q2 and $115 million at Q1 as pre-stripping spending reached $60.2 million year to date.
- **Restricted cash.** No update was given on the roughly $26 million held under the garnishee order.
- **Deferred guidance.** Both 2027 guidance and adit costs were pushed to February and to completion of the contractor tender.
One reconciliation point matters. Q2 operating cash flow was $6.0 million as reported but $31.9 million excluding the restricted-cash effect. Either way, Q3's $57.0 million marks a clear sequential improvement.
Investor sentiment swung sharply, moving from negative territory at -0.37 before the prior report to a decidedly positive +0.71. That shift suggests expectations have rotated toward the 2027 de-hedging and operating-momentum narrative rather than the EPS shortfall. The stock's response has been more measured. Shares trade at $2.12, up 10.4% from the $1.92 opening after the August report, but still about 8.8% below the $2.33 200-day moving average. The market has rewarded progress without fully re-rating the stock.
The bottom line is that Galiano missed on adjusted earnings for reasons largely tied to legacy hedges and royalties, not mine performance. Production, grade, throughput and AISC all improved, and the hedge book is about to roll off. The investment case now hinges on 2027: whether unhedged pricing turns into visible free cash flow after Nkran pre-stripping, and whether February guidance and the Q1 reserve update justify the optimism already embedded in investor sentiment.
Read our earnings preview for Galiano Gold Inc.: https://www.earningswhispers.com/article/GAU/22292
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-13 | |
| Oct-08 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-28 | |
| Jul-09 | |
| Jun-17 | |
| Jun-11 | |
| Jun-02 |
