Castellum (CTM) Misses As Pipeline Nearly Doubles, But Thinner Backlog And Cash Use Leave The M&A Pitch On Trial
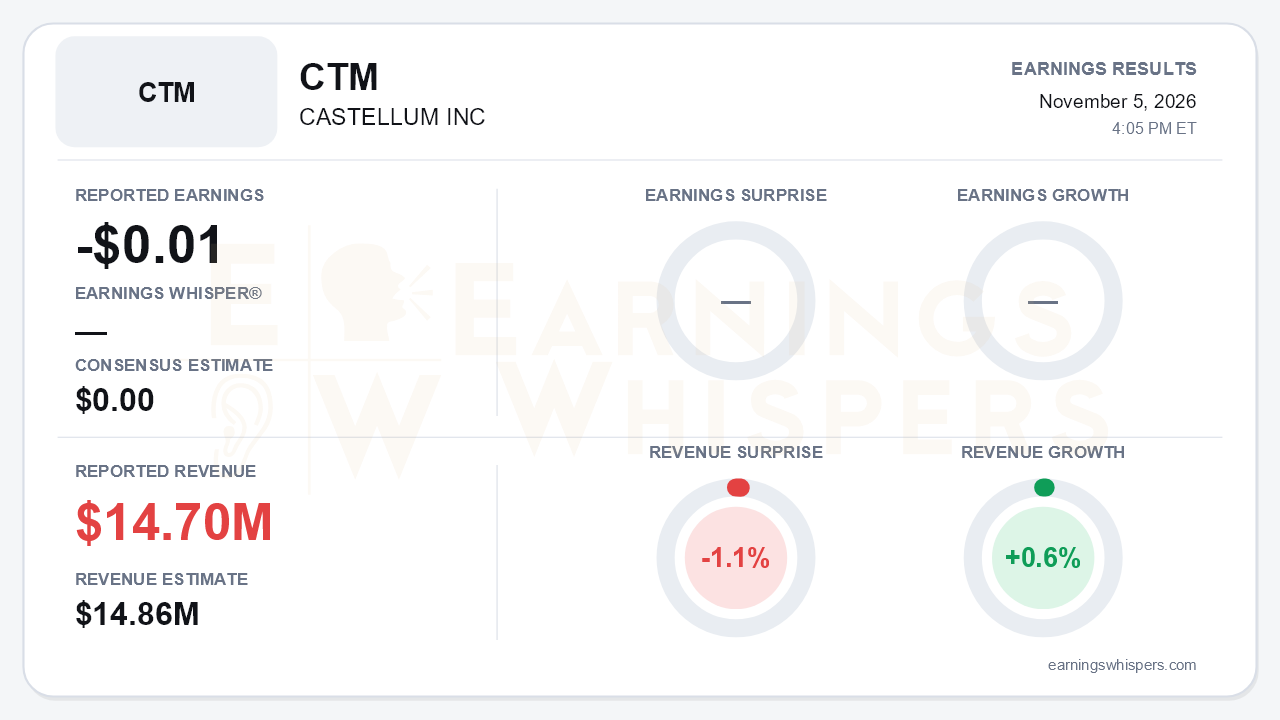
Castellum reported a third-quarter loss of $0.01 per share on revenue of $14.7 million, missing the $0.00 consensus and falling 1.1% short of the $14.86 million revenue estimate. Revenue grew just 0.6% year over year. On the bottom line, net income of $0.4 million a year ago became a $0.5 million net loss. The quarter offers two readings. Sequentially, the business recovered from a weak second quarter. Year over year, growth has stalled while spending has climbed. Management is asking investors to look past near-term earnings toward a much larger pipeline and an acquisition strategy, and shareholders do not appear inclined to grant that patience.
The sequential numbers were better than the headline miss suggests. Revenue rose from $13.9 million in Q2. Gross margin recovered to about 36% from roughly 34%, and adjusted EBITDA improved to about $0.6 million from near breakeven. The net loss narrowed to $0.5 million from the $1.1 million reported for Q2 in the release; management cited roughly $1.0 million on the call.
The year-over-year comparison is harder to defend:
- **Margins:** Gross margin remains below the 37.6% of a year ago because more of the work went to lower-margin subcontractors.
- **Expenses:** Total operating expenses rose to $5.9 million from $5.0 million as the company expanded business development and M&A activity.
- **Stock compensation:** Stock-based compensation nearly tripled to $0.8 million from $0.3 million.
- **Adjusted EBITDA:** The measure fell by roughly half from $1.1 million in the prior-year quarter.
- **Growth:** Nine-month revenue growth slowed to 6% from 10% at the half-year mark.
CFO David Bell said the EBITDA decline was anticipated and consistent with the investment plan. That is a fair framing, but it means the cost of the strategy is now clearly visible while the return is not.
The forward indicators send conflicting signals. On the positive side:
- The qualified opportunity pipeline nearly doubled to about $1.66 billion from $953.5 million.
- An August NAVAIR modification added $32.8 million to the PMA-290 Special Missions contract, lifting its total value to $136.2 million.
- Management now expects about 25% of backlog to convert to revenue within 12 months, up from roughly 16% at Q2, and 51% within 24 months, up from about 48%.
The weak spot is backlog itself. It fell to $254.5 million from $271.7 million even though the company changed its reporting to include priced contract options it previously reported separately. A shrinking backlog under a broader definition deserves scrutiny. It suggests the pipeline growth is not yet turning into contract awards fast enough to replace the work being burned off.
Liquidity is solid, but the trend has turned. Cash and receivables rose to $24.5 million and the company carries no long-term debt. Cash itself, however, fell to $15.7 million from $16.9 million at Q2. Year-to-date operating cash flow dropped to $1.1 million from $2.4 million at mid-year, which implies the company used cash in the third quarter.
Management reaffirmed its expectation of record full-year 2026 revenue. It was explicit that acquisitions, not organic growth, are its principal path to scale. It is targeting tangible M&A results within six to 12 months, possibly with news in early 2027, and is focused on businesses with roughly $15 million to $30 million in revenue. Other potential catalysts include:
- a possible change to SBA small-business size standards, which management views as a potential positive;
- its GuardTower AI insider-threat appliance, expected to be resellable in about six months.
The risks are concrete. Acquisitions are slow to produce and often difficult to integrate. Spending ahead of revenue is pressuring profitability. Management deprioritized buybacks in favor of M&A, a choice that drew visible pushback from shareholders.
The call's tone shifted noticeably from the bullish framing management offered in Q2. The Q&A was dominated by frustration over the share price, which participants referenced at around $0.39 and new lows. Shareholders asked about a reverse split, and management did not fully rule one out; the release also lists maintaining the NYSE American listing as a risk factor. The report-day snapshot put the shares at $0.47. That is 22.3% below the $0.61 opening price after the August report and 33% below the 200-day moving average of $0.71. Earnings Whispers investor sentiment stands at -0.92, near the most negative end of the scale. The market's verdict on the investment phase has been unambiguous, and bears have legitimate ammunition in the shrinking backlog and declining cash.
The bottom line is that Castellum delivered a credible sequential rebound in revenue, margins and adjusted EBITDA, along with a dramatically larger pipeline. However, it missed estimates, posted essentially flat year-over-year revenue, reported lower backlog and used cash during the quarter. The investment case now rests largely on management converting pipeline into awards and executing a disciplined acquisition within the next year. Until either shows up in the numbers, a deeply skeptical shareholder base and a stock well below its long-term trend suggest investors will need to see results rather than hear about them.
Read our earnings preview for CASTELLUM INC: https://www.earningswhispers.com/article/CTM/22440
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-06 | |
| Nov-05 | |
| Oct-28 | |
| Oct-28 | |
| Oct-16 | |
| Oct-12 | |
| Sep-09 | |
| Aug-31 | |
| Aug-06 | |
| Jul-31 | |
| Jun-24 | |
| Jun-23 | |
| Jun-15 | |
| May-19 |
