Ameren Beats On Heat And Investment Gains, But The Real News Is A Bigger, Costlier Data-Center Growth Plan
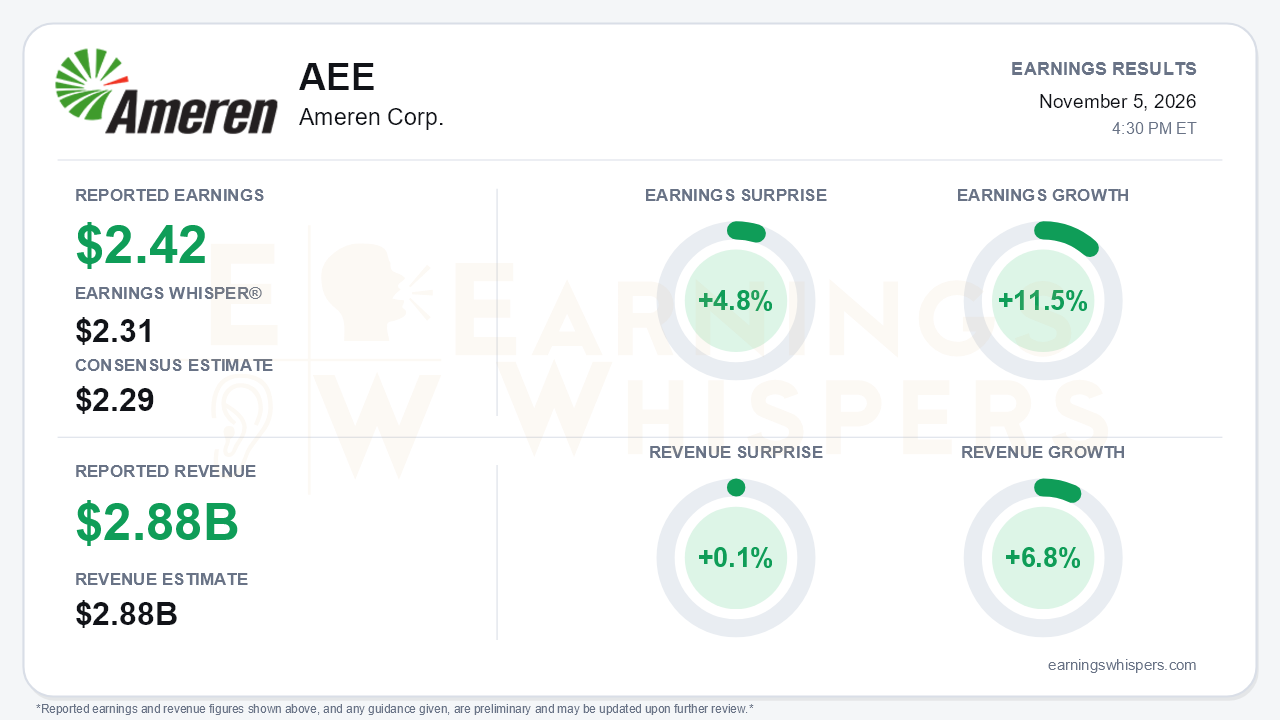
Ameren Corp. (NYSE: AEE) earned $2.42 per share in the third quarter, beating the $2.29 consensus and the $2.31 Earnings Whisper number by 4.8%. Revenue of $2.882 billion was essentially in line with the $2.88 billion estimate, a 0.1% beat, and grew 6.8% year over year. Earnings grew 11.5% against last year's adjusted $2.17. The quarter mattered less than the plan reset that came with it. Ameren raised its 2026 guidance, initiated 2027 guidance at $5.70 to $5.90, and lifted its long-term EPS growth target to 8% to 10% annually through 2031, up from 6% to 8%. The bigger growth story comes with heavier financing demands, and that is the central tension.
The quality of the beat deserves scrutiny. On a GAAP basis, EPS rose only to $2.42 from $2.35, because the year-ago quarter included an $0.18 tax benefit from a FERC order. The adjusted comparison is cleaner, but the drivers flatter it. The call attributed part of the outperformance to record heat and non-recurring gains in the innovation-fund portfolio. That fits the income statement:
- Other income jumped to $112 million from $76 million.
- Ameren Missouri residential volumes rose about 7%.
- Weather-normalized Missouri retail sales growth slowed to roughly 0.5% on a trailing basis, down from about 1% last quarter.
Other details cut the other way. Operations and maintenance expense rose on reliability-driven tree trimming and plant maintenance. The diluted share count climbed to 278.9 million from 272.2 million. Illinois industrial volumes fell about 8%. Missouri off-system sales and capacity revenue declined. Infrastructure earnings are compounding as designed, but the organic demand underneath the headline was soft this quarter.
The forward plan is a different story. Ameren raised its five-year capital plan to $38.1 billion from $31.8 billion, lifting projected rate base growth to 13.3% annually from 10.6%. Its Missouri sales growth assumption more than doubled to 12.9% from 6.2%, now embedding 2.9 GW of new load versus 1.2 GW previously. That load is anchored by 2.8 GW of signed electric service agreements, including Google and Amazon data center projects already under construction. Beyond the signed deals, management cited another 5.6 GW of large-load pipeline and said it expects more agreements in 2027. Management called the plan conservative because it embeds only signed agreements. It also expects 2028 and 2029 to land near the top of the new growth range.
Several new developments widen the story:
- **Generation build-out:** the new resource plan targets about 7.7 GW of new generation by 2031, an 80% increase in installed capacity.
- **Transmission expansion:** Ameren won its first competitive transmission project outside its service territory, the roughly $500 million ESOL project in Iowa.
- **Longer runway:** the 10-year investment pipeline now exceeds $90 billion.
Bears have legitimate ammunition, and it centers on funding and execution. Planned equity issuance rose to about $5 billion from roughly $4 billion, leaving about a 300-basis-point gap between rate base growth and EPS growth. Ameren has already lined up about $1.7 billion of forward equity sales. The payout ratio target was lowered to 45%-55% from 50%-60%, which implies dividend growth may trail earnings growth. The balance sheet already shows the strain:
- Nine-month capital spending rose to $4.1 billion from $3.1 billion.
- Operating cash flow fell to $2.2 billion from $2.4 billion.
- Long-term debt climbed above $20.4 billion.
Execution risk is real. The build includes the 2.1 GW West Alton combined-cycle plant under a non-traditional contracting structure. The 2027-2028 sales ramp depends on hyperscaler construction timelines. Regulatory exposure also remains:
- An Illinois administrative law judge proposed trimming about $200 million from the $2.7 billion grid plan.
- The Missouri electric rate case will not be decided until May 2027.
- Customer affordability will draw more attention as spending accelerates.
The market appears to have anticipated much of this. The guidance raise was described as in line with estimates, consistent with a long-telegraphed reset. Investor sentiment improved modestly, from -0.088 before the prior report to essentially neutral at -0.0001. That is a shift away from mild skepticism, not a swing to enthusiasm. Shares are up 3.7% since opening at $108.77 after the July report and trade about 3.9% above the 200-day moving average. The stock has been rewarded steadily but not aggressively.
The bottom line is that Ameren's quarter was good but helped by weather and investment gains, while the strategic update was the real event. The company has credibly re-rated its growth algorithm on signed data-center demand, raising both near-term guidance and the long-term EPS target. Investors are being asked to accept more equity dilution, slower dividend growth relative to earnings, and meaningful regulatory and construction risk to get there. With sentiment now neutral and the stock modestly above trend, the upgraded plan must be delivered, not just announced.
Read our earnings preview for Ameren Corp.: https://www.earningswhispers.com/article/AEE/22224
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-28 | |
| Oct-22 | |
| Oct-14 | |
| Oct-09 | |
| Sep-28 | |
| Sep-22 | |
| Sep-16 | |
| Sep-08 | |
| Aug-17 | |
| Aug-14 | |
| Jul-31 |
