Hyster-Yale Misses Badly As A Slower Recovery Pushes Management Toward A Bigger Restructuring
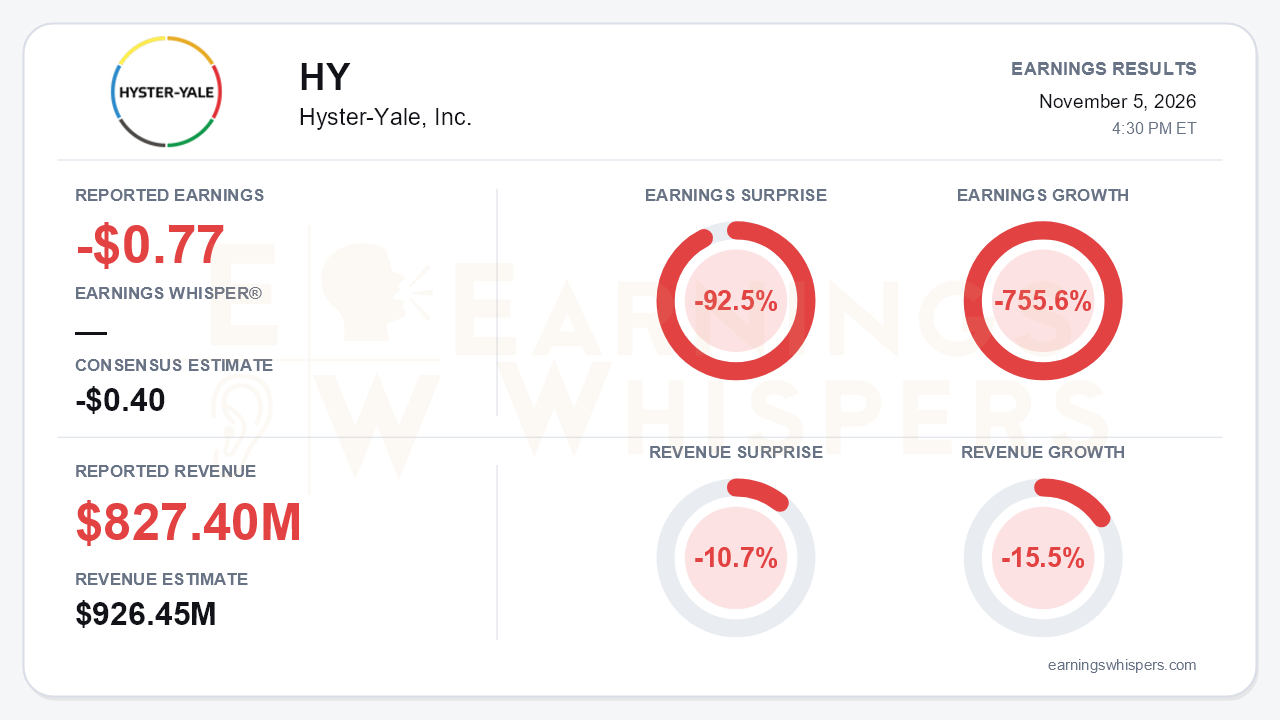
Hyster-Yale's third quarter showed real sequential progress, but the quarter fell well short of what the Street expected. The company reported an adjusted loss of $0.77 per share, nearly double the consensus loss of $0.40, a 92.5% negative surprise. Earnings fell 755.6% from a year earlier, when the adjusted loss was just $0.09. Revenue of $827.4 million missed the $926.45 million consensus by 10.7% and declined 15.5% year over year. The GAAP loss was $0.83 per share. Against those misses, the loss narrowed by more than half from Q2's $1.65 adjusted loss, and adjusted EBITDA turned positive at $6.0 million. The central tension is that the business is clearly off the bottom, but management is now describing a slower, longer climb than it did even a quarter ago.
The quality of the sequential improvement deserves scrutiny. Revenue rose only 2% from Q2, and Lift Truck revenue rose 3%. Lighter-intensity, lower-priced trucks continued to displace higher-value Class 1 and Class 4 products. Management credits those value models with share gains, but they are also a key reason Lift Truck gross profit fell 21% from a year ago. Q3 also included roughly $15 million of tariff-related recoveries on amounts paid previously. That figure was $20 million less than in Q2, yet it still flattered results that remained loss-making. Lower incentive compensation helped as well.
Cash flow carries a similar caveat. Operating cash flow rose to $26 million from $17 million in Q2, but the release ties much of the improvement to accounts payable, which climbed about $49 million. Inventory rose sequentially to $665 million. Net debt of $426 million is roughly flat with June and up from $397 million a year ago, while trailing adjusted EBITDA is negative $13.2 million.
The call explained why the revenue shortfall happened. Management said Q3 revenue missed its own internal expectations, mainly in North America. It split the cause roughly equally among freight timing, customer-requested delivery deferrals and chip and circuit-board shortages that constrained production.
Demand itself looks steadier than the revenue line. Bookings of $550 million rose 45% year over year, the fourth consecutive elevated quarter. They fell from Q2's $680 million, which management attributed to normal seasonality. Backlog held at $1.6 billion. Management expects Q4 bookings to exceed both Q3 and the year-ago quarter, with meaningfully higher production and shipments and a return to positive adjusted net income. That conversion has been promised before, however, and shipment timing remains exposed to deferrals and tariff-driven sourcing changes.
The forward outlook is where the setup deteriorated:
- **2026 outlook:** The full-year operating view has slid from "moderate profit" to "modest profit" to a "moderate loss," and it was not improved this quarter.
- **2027 outlook:** Management now says operating profit improvement will be more gradual than the demand recovery, citing cost pressure and competitive pricing, particularly in South America and Europe.
- **Dropped target:** The prior goal of trailing EBITDA above pre-COVID levels in the second half of 2027 was not reiterated.
- **Footprint savings:** Benefits from the manufacturing footprint program, already trimmed earlier in the year, are now framed as offsetting inflation rather than expanding margins.
- **Capital spending:** Capex will be held to $40 million to $50 million in 2027, explicitly to preserve cash amid a "slower-than-anticipated recovery."
Management's response is a major new restructuring program. It targets at least $100 million in annual savings by 2029 and carries at least $50 million of implementation costs, with no high-end estimate yet. As part of the program, Hyster-Yale is exiting the hydrogen fuel cell and HydroCharge business, pausing its electric terminal tractor program and canceling Big Truck production in Greenville, North Carolina. Investment is being redirected toward lithium-ion battery solutions and modular value and standard trucks. A new CFO, Matt Cornell, has also joined.
Refocusing on the core lift-truck business is a defensible move. The trade-off is that bulls are being asked to wait until 2027 to 2029 for payback, while restructuring charges continue to cloud reported results.
The market had largely anticipated a disappointing quarter. Shares closed at $26.95, down 24.1% from the $35.53 open after the August report and about 21% below the 200-day moving average of $34.27. Investor sentiment was essentially unchanged, edging from -0.165 to -0.171. Expectations were already negative and did not deteriorate meaningfully further. That leaves a stock priced for disappointment but without a clear near-term reason for sentiment to turn.
The bottom line is that Hyster-Yale delivered genuine sequential improvement, including positive EBITDA, a narrower loss and firm bookings. However, it missed consensus by a wide margin, leaned on tariff recoveries and payables timing, and replaced a faster profit ramp with a longer restructuring timeline. Q4 is now a credibility test. If shipments finally convert and adjusted net income turns positive as promised, the depressed stock and subdued sentiment leave room for a reassessment. Another conversion shortfall would give bears even more ammunition.
Read our earnings preview for Hyster-Yale, Inc.: https://www.earningswhispers.com/article/HY/22461
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Oct-29 | |
| Oct-29 | |
| Oct-15 | |
| Oct-01 | |
| Sep-17 | |
| Aug-12 | |
| Aug-12 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-28 |
