Gray Media Misses On EPS As Refinancing Charges Cloud A Record Political Quarter; Organic Core Softness Remains The Overhang
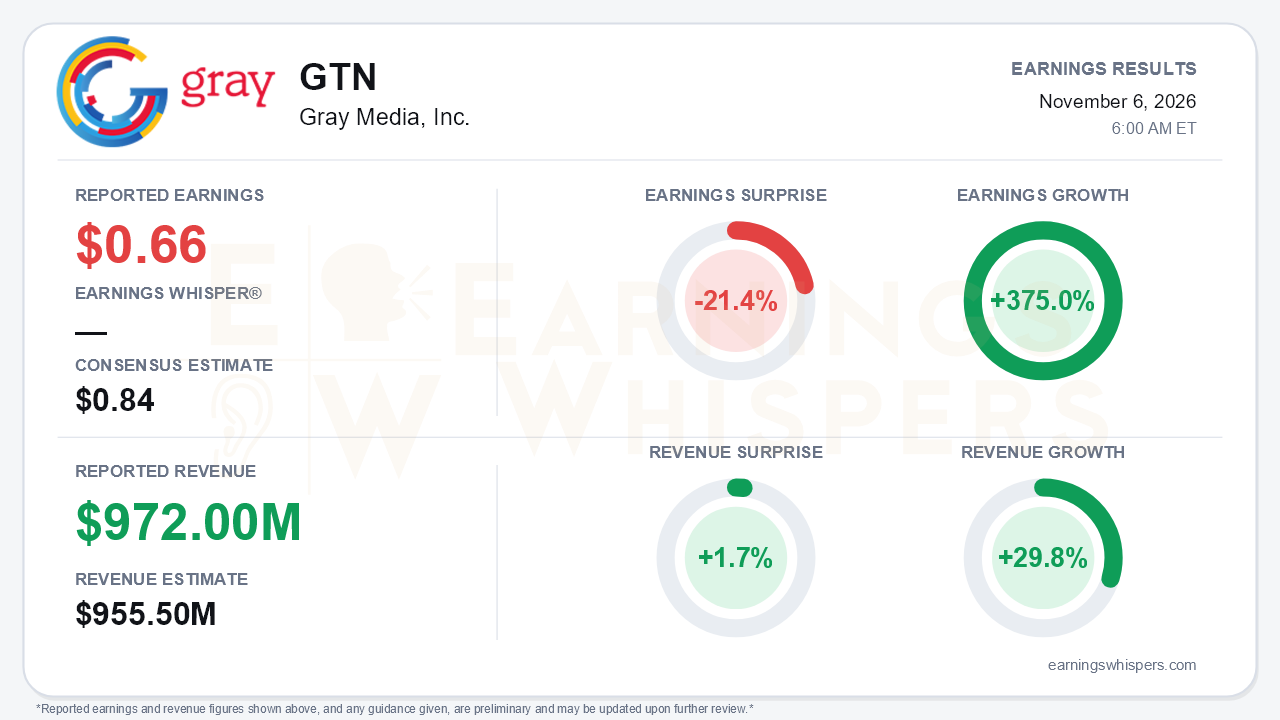
Gray Media's third quarter produced a split verdict. The company earned $0.66 per share, missing the $0.84 consensus by 21.4%. Revenue of $972.0 million beat the $955.5 million estimate by 1.7% and grew 29.8% year over year. Earnings grew 375.0% from a year-ago loss of $0.24 per share, which turns a $10 million net loss into $78 million of net income. The central tension is clear. The operating quarter was stronger than the EPS line suggests, but the strength rests heavily on cyclical political dollars and acquisitions, while organic core advertising continues to shrink.
The quality of the miss deserves context. GAAP results absorbed a $40 million loss on early extinguishment of debt tied to Gray's aggressive refinancing, compared with just $7 million a year earlier. That charge alone is a meaningful drag on a roughly 100-million-share base. Below the line, the operating picture was strong. Adjusted EBITDA nearly doubled to $319 million from $162 million, and it has stepped up sequentially from $154 million in Q1 and $214 million in Q2. Every major line topped the revised guidance issued in late September:
- Political advertising was $198 million against a $188-195 million range, well above the $173 million of the 2024 third quarter.
- Total revenue came in about $7 million above the high end of guidance.
- Net retransmission revenue rose 14% to $150 million, landing at the top of its range.
The headline masks a weaker underlying trend. Reported core advertising rose 1% to $358 million, but the 2026 acquisitions contributed $24 million of that. On a same-station basis, management acknowledged core was down mid-single digits, in line with its earlier expectation. Q4 core is pacing down low-to-mid single digits, and full-year core is guided flat to down low single digits. The category detail is not encouraging. Communications, health and insurance are soft. Auto slipped 1-2% in Q3 after management had said in August that it was pacing slightly up, and it is now expected to decline low-to-mid single digits in Q4. Digital growth has cooled from the high teens in Q1 to 12%. Political crowd-out explains part of this, but not all of it.
The balance sheet is where the investment setup changed most. Gray retired roughly $1 billion of its 10.5% first lien notes due 2029, leaving $200 million outstanding. It did so through a $750 million 7.5% note due 2034 and a $675 million Term Loan G, and it extended the revolver to 2030. The release cites more than $30 million of annual interest savings from these moves. On the call, management framed 2027 interest savings at at least $40 million, up from the $30 million-plus cited in August, with a further $175-200 million paydown planned in Q4 from political cash. The 2026 capex guidance was cut again, to $110-120 million, though partly because projects slipped into 2027.
Bears still have legitimate ammunition:
- Total net leverage remains 5.7x, essentially unchanged from Q2, partly because of about $65 million in refinancing costs, including roughly $43 million of call premiums.
- Net debt actually rose to $5.67 billion from $5.44 billion at year-end, following $302 million of acquisition spending.
- The next retransmission renewal cycle begins in about six months, amid industry concern over network content exclusivity.
- A shift in congressional control adds regulatory uncertainty around consolidation.
On the other side, management said Q1 2027 core is pacing positive on a same-station basis despite tough Olympics and Super Bowl comparisons. It also expects both gross and net retrans to grow in 2027 and acquired-station costs to fall as integration reaches 75-80% completion. Q4 guidance calls for record political revenue of $319-329 million and total revenue of $1.115-1.14 billion, up from $792 million a year ago.
Investor sentiment improved dramatically ahead of the report, rising from essentially neutral at 0.02 to a solidly positive 0.77. That is a genuine shift in expectations, and it raises the bar for the post-report reaction. Price action has been far more muted. Shares closed at $4.88 the day before the release, up just 2.7% from the $4.75 open after the August report. The stock sat 6.1% above its 200-day moving average but 10.8% below the $5.47 inter-earnings high set on that same August day. It had rebounded 15.4% from the October 28 low of $4.23, suggesting buyers were returning into the print without fully recovering the summer's peak.
The bottom line is that Gray delivered a record political quarter, beat its own guidance across the board and materially de-risked its debt maturities. The EPS miss reflects refinancing costs more than operating weakness. Still, the equity story now depends on whether same-station core advertising actually turns positive in early 2027 and whether retrans growth materializes as promised. Until leverage moves meaningfully below 5.7x, the post-election hangover remains the key test of how durable this improvement is.
Read our earnings preview for Gray Media, Inc.: https://www.earningswhispers.com/article/GTN/22513
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Nov-03 | |
| Oct-29 | |
| Oct-26 | |
| Oct-20 | |
| Oct-15 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-02 | |
| Sep-28 |
