Fidelity National Financial: GAAP Windfall Masks A 19% Adjusted Earnings Drop As A Fed Hike Stalls The Title Engine
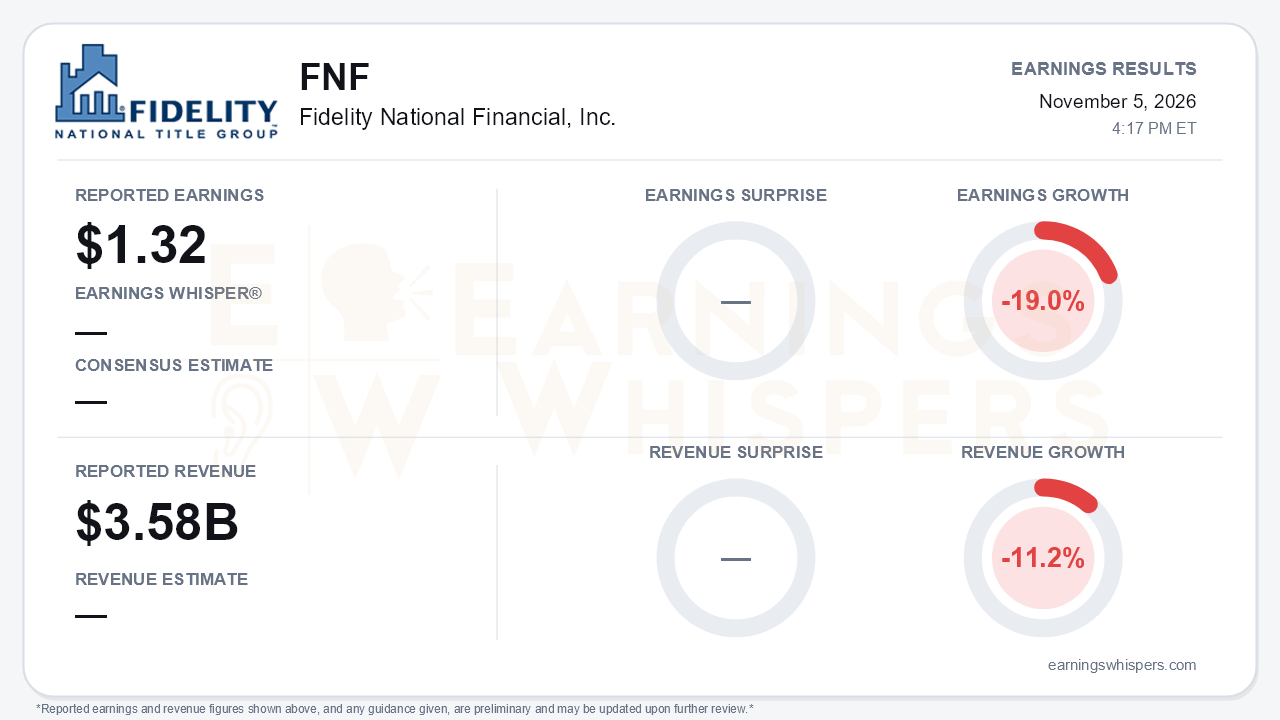
Fidelity National Financial's third quarter carried two very different headlines, and the less flattering one matters more. Adjusted earnings were $1.32 per share on revenue of $3.578 billion. Adjusted earnings fell 19.0% year over year and revenue fell 11.2%. GAAP net earnings nearly doubled to $2.37 per share from $1.33, but that came from favorable mark-to-market swings at F&G, including $652 million of market-related liability adjustments, not from improving operations. Adjusted EPS also slipped sequentially from $1.39 in the second quarter. The central takeaway is that FNF's title momentum is rolling over. A September Fed rate hike pushed mortgage rates back toward 7.6%, and management is now guiding the fourth-quarter title margin toward the low end of its 15% to 20% range.
The quality of the quarter deserves scrutiny because the title segment looks healthier on a year-over-year basis than the trend beneath it. Adjusted pre-tax title earnings rose 3% to $422 million. Direct premiums grew 11%, commercial revenue grew 19% to $463 million, and total fee per file rose 6% to $4,229. But the 3% gain is a sharp deceleration from roughly 33% growth in the second quarter and 27% in the first. The adjusted pre-tax title margin fell to 17.1% from 17.8%. Costs are outrunning revenue. Title personnel costs rose about 10% and other operating expenses about 13%, while agency premiums grew only 3%. Management attributed part of the pressure to front-loaded recruiting and acquisition spending. It has already begun cutting staff, which signals it recognizes the mismatch.
The order data is where the story turns. Total daily opened orders fell to 5,800 from 6,200 in the second quarter and 6,400 in the first. October orders dropped to 4,700 per day, down 17% from a year earlier. That is a stark reversal from the 7% gain management cited for July on the prior call. The weakness is broad:
- Purchase orders fell 6% year over year in October.
- Refinance orders fell 35%.
- Commercial orders, the segment's reliable bright spot, fell 6%.
Management's tone shifted accordingly, from talk of sustained momentum to describing a challenging real estate cycle. Commercial is still on pace for a record year, with nine-month direct commercial revenue up 22%. Management also pointed to data center refinancings as a recurring driver and expects another strong year in 2027. However, deals with premiums above $1 million slipped to 24 from 29, and comparisons get tougher from here.
F&G is a mixed contributor. Its adjusted contribution to FNF fell to $72 million from $139 million. That decline reflects FNF's smaller ownership stake (about 72% versus 82%) and the sale of F&G Life Re ( Bermuda ). It also reflects lower surrender charge income, and alternative investment income again fell short of long-term expectations. Operationally, F&G posted record core retail sales of $2.1 billion and gross assets under management of $76.2 billion. Total gross sales fell to $3.0 billion from $4.2 billion. That drop was deliberate: multiyear guaranteed annuity volume was cut from $969 million to just $73 million because returns fell below threshold. Management also said it will pursue ways to unlock what it views as F&G's undervaluation, a potential catalyst without a defined path yet.
There are offsets worth noting:
- The rate backdrop that hurts orders helps the float. Management raised its title and corporate investment income outlook to about $105 million in the fourth quarter, rising roughly $5 million per quarter through 2027. That compares with a $95 million to $100 million quarterly guide last quarter, though the outlook assumes another 75 basis points of Fed hikes.
- Holding company cash rose to $545 million. Buybacks were only $5 million because of a closed trading window, and management said it expects to be aggressive once the blackout lifts.
- Technology adoption is advancing. inHere usage reached about 88%, and AI agents are now running in production workflows.
The new FHFA executive order adds regulatory uncertainty on top of the rate risk.
Investors were already leaning pessimistic, and sentiment deteriorated meaningfully. The Earnings Whispers sentiment reading fell from -0.36 to -0.59. The stock has slid 17.8% since the open following the August report, from $52.16 to $42.89, and sits about 10% below its 200-day moving average of $47.81. Much of the order slowdown appears to have been absorbed into the price before this release. Even so, the October data and lower margin guide give bears legitimate ammunition that the decline in title earnings is just beginning.
The bottom line is that FNF's GAAP surge is accounting noise, while the adjusted results show a title franchise losing momentum as higher rates choke off orders and costs run ahead of revenue. Commercial strength, rising investment income, a growing F&G retail franchise and dry powder for buybacks keep the longer-term case intact. Still, the near-term setup has clearly weakened, and fourth-quarter margins near the bottom of management's range now look like the base case.
Read our earnings preview for Fidelity National Financial, Inc.: https://www.earningswhispers.com/article/FNF/22286
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-13 | |
| Oct-08 | |
| Oct-05 | |
| Sep-17 | |
| Sep-16 | |
| Sep-08 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 |
