Atmus Beats And Raises Again, But Flat Margins And A Buyback Pivot Define A Quarter Driven More By Koch Filter And Volume Than By Pricing
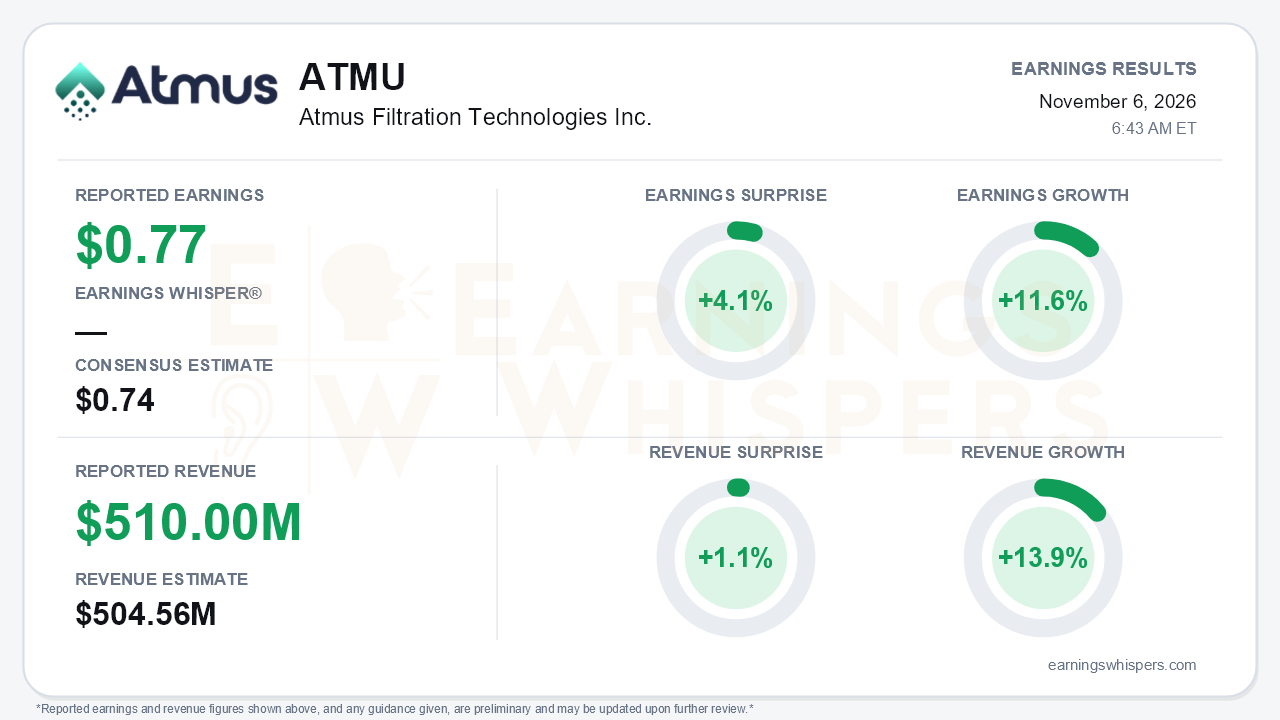
Atmus Filtration Technologies delivered a clean but measured third quarter. Adjusted earnings of $0.77 per share beat the $0.74 consensus by 4.1% and grew 11.6% year over year. Revenue of $510.0 million topped the $504.56 million estimate by 1.1% and grew 13.9%. Management raised full-year revenue and adjusted EPS guidance for the second straight quarter, with the EPS range now $2.90 to $3.05, and paired it with a new $300 million buyback authorization. The central tension is that the top line is getting stronger while profitability is not expanding. Earnings growth trailed revenue growth, the adjusted EBITDA margin was flat at 20.4%, and the margin outlook was held rather than lifted.
The quality of the beat deserves some scrutiny. Much of the 13.9% sales growth came from the Koch Filter acquisition. The new Industrial Solutions segment contributed $42 million of the roughly $62 million year-over-year increase. On the call, management put Power Solutions organic growth at 3%, or 5% excluding tariff refunds and currency. Gross margin rose to 30.3% from 28.9% a year ago and 29.2% in the second quarter. The gains came from volume, pricing, manufacturing costs, lower warranty expense and the absence of Cummins separation costs, partly offset by higher material and freight costs. Below gross profit, however, the acquisition's financing showed up:
- Interest expense climbed to $13.1 million from $8.5 million as long-term debt rose to $948 million.
- Koch Filter added $2.8 million of intangible amortization.
- Other operating expense of $3.8 million included what the call described as a non-recurring $3 million supplier settlement.
GAAP diluted EPS was $0.74, matching consensus. The adjusted $0.77 adds back acquisition amortization, so the size of the beat depends on which earnings basis investors use.
The operating story improved most in volume. Power Solutions volume rose 5%, the strongest of the year, after 2% in the second quarter and a slight decline in the first. Management raised its full-year volume outlook to 2-3% from flat-to-2%. The U.S. heavy- and medium-duty first-fit recovery that began in the second quarter is expected to continue into the first half of 2027, with no supply constraints. Pricing moved the other way. Net pricing guidance was cut to about 1% from 1.5% as tariff-related increases lapped and $9 million of tariff refunds to customers reduced reported sales. Aftermarket, roughly 85% of Power Solutions, remains flat with no freight-cycle inflection. Atmus is therefore growing on first-fit volume and acquisition revenue rather than on its higher-quality aftermarket base.
Bears have legitimate ammunition on the outlook. The adjusted EBITDA margin guide of 19.75% to 20.25% was unchanged and implies a fourth-quarter margin near 19.1%, a seasonal step down. Other risks raised on the call include:
- input costs are stepping up and price actions may lag;
- diesel pickup first-fit demand is weakening into the fourth quarter;
- the Middle East conflict is weighing on Europe, Indian aftermarket demand and the India joint venture's profitability;
- the EPA 2027 rule remains unresolved until an expected December decision, clouding first-fit timing.
On the positive side, Koch Filter integration is complete. A HEPA clean room in Louisville has received its first order, adding higher-margin healthcare exposure, and a Florida facility is approved for 2027. Management now plans to pursue industrial-air growth and bolt-on acquisitions.
Capital allocation is the most meaningful change in the setup. Atmus repaid $100 million of debt since the second-quarter call and cut net leverage to 1.7x from 2.1x at the deal close, reaching its target. Management said the majority of free cash flow will now go to repurchases, a clear shift from the second-quarter emphasis on debt paydown with modest buybacks. Third-quarter adjusted free cash flow rose to $88 million from $72 million, and year-to-date adjusted free cash flow was $189 million, up $61 million. That cash generation gives the larger authorization credibility.
Investor expectations had improved into the report even as the stock struggled. Earnings Whispers sentiment rose from slightly negative (-0.09) to clearly positive (+0.35), a meaningful shift. Shares were not rewarded, though. At $46.16 heading into the release, the stock was 12.4% below its open after the prior report and 12.7% below its 200-day moving average. It had set a 52-week low of $40.75 on October 8 and has since rebounded 13.3%, yet it still sits 15.7% beneath its August high. Sentiment has run well ahead of the price.
The bottom line is that Atmus delivered a solid beat-and-raise backed by the best volume growth of the year, a completed integration, strong cash flow and a deleveraged balance sheet that frees cash for buybacks. The weaker underlying trend is margins: flat year over year, held for the full year and set to dip in the fourth quarter as pricing fades and input costs rise. Until aftermarket demand turns and the EPA rule is settled, the stock's recovery from its October low likely depends more on buybacks and first-fit volume than on margin expansion.
Read our earnings preview for Atmus Filtration Technologies Inc.: https://www.earningswhispers.com/article/ATMU/22468
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Oct-29 | |
| Aug-14 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| May-13 | |
| May-11 | |
| May-02 | |
| May-01 | |
| May-01 | |
| Apr-30 |
