Wheaton Precious Metals Misses As The Metal-Price Tailwind Fades, Even As Its Growth Pipeline Gets Its Best Quarter Of Milestones
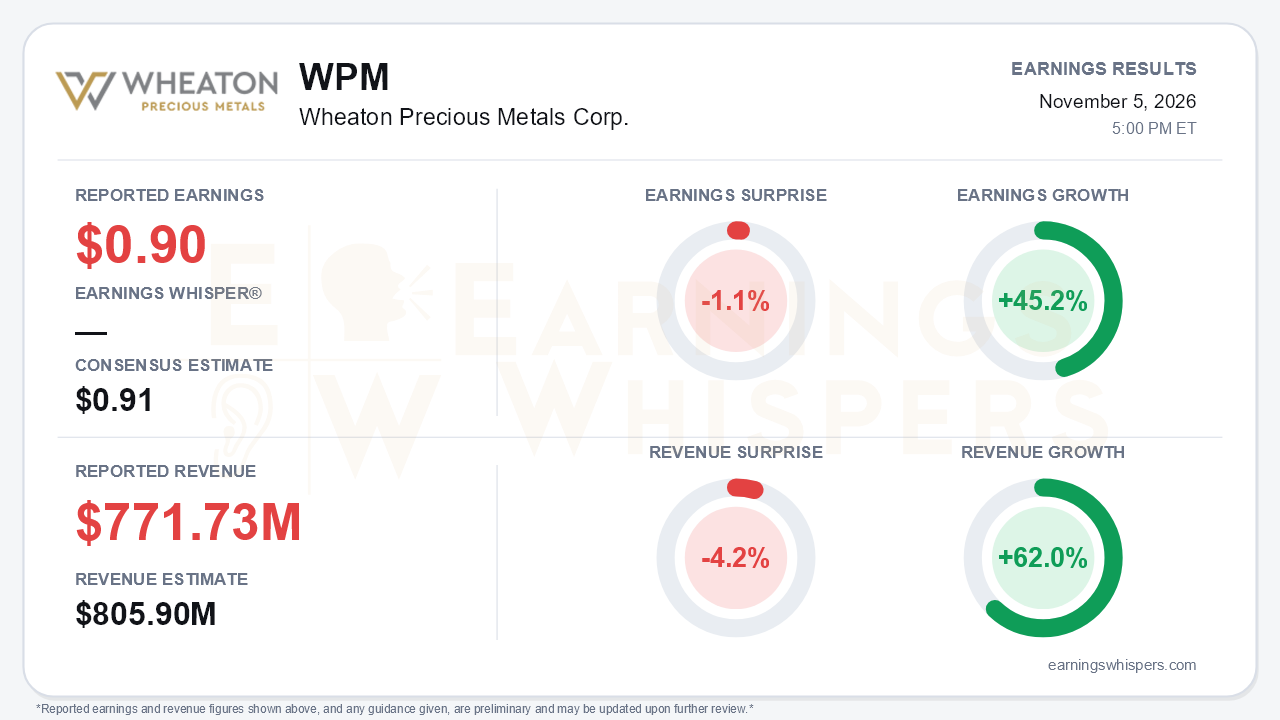
Wheaton Precious Metals delivered a quarter that looks strong on a year-over-year basis but is weaker by the standard that matters now: sequential momentum. Third-quarter earnings of $0.90 per share missed the $0.91 consensus by 1.1%. Revenue of $771.73 million fell 4.2% short of the $805.9 million estimate. Year-over-year growth remained large, with earnings up 45.2% and revenue up 62.0%. That growth is clearly decelerating, though. Management's figures show realized gold-equivalent price growth slowing to 36% from 61% in the second quarter and 98% in the first. Revenue slipped from a record $929 million in Q2 and $901 million in Q1. That is the central tension: the commodity-price engine behind record year-to-date results is losing force just as Wheaton has taken on leverage to buy growth.
The beneath-the-surface details explain the shortfall. Production was genuinely strong at 231,000 gold-equivalent ounces, up 13% year over year and well above Q2's 202,600. Sales lagged at 192,270 GEOs, however, and produced-but-not-delivered inventory rose to roughly 178,600 GEOs from 161,700. Some of the revenue miss therefore reflects timing rather than lost ounces. Pricing was also softer within the year. Q3 realized gold of $4,273 and silver of $62.13 sat well below the nine-month averages of $4,527 and $72.90. The cost structure has also shifted. Depletion nearly doubled to $127.9 million, driven by the newly acquired BHP Antamina stream, which carries $26.30 per ounce of silver depletion versus $4.39 a year ago. Finance costs jumped to $25.1 million from $1.4 million. GAAP net earnings rose only 11.7% because last year included an $85.7 million gain on the Cangrejos buyback. The adjusted comparison, up 45.8%, is the cleaner read.
The call preserved a credible growth story. Wheaton reaffirmed its 860,000-940,000 GEO 2026 guidance. It also reaffirmed its 1.2 million GEO target for 2030, and management noted that Marathon, Jervois and Cangrejos are not yet included. Development milestones were unusually dense:
- Montage's Koné poured first gold ahead of schedule, and the long-term view improved to at least 350,000 ounces a year for more than 10 years.
- Kurmuk entered production, and Platreef made first deliveries.
- Copper World and Jervois reached final investment decisions, and Marathon began construction.
- The Salobo stream was restructured around Vale's coarse particle flotation project. A $40 million payment replaces a potential $80 million obligation, with roughly a 1.5-year payback.
Nothing was raised, however, and bears have legitimate ammunition on the near-term outlook. Management flagged a significant drop in Peñasquito silver into Q4 and 2027, with Newmont pointing to roughly 30% lower group silver next year. Antamina may dip slightly in 2027. Salobo grades fell on mine sequencing and are guided flat in 2027 rather than recovering. Hitting even the low end of 2026 guidance requires a large Q4 ramp that excludes Koné and Kurmuk. Labour disputes at San Dimas and Stillwater and a four-month delay at El Domo add friction. The 2030 target also rests on a 60:1 gold/silver ratio assumption that management will reassess at year-end.
The balance sheet story is mixed. Net debt fell to about $1.5 billion from about $1.9 billion after a $372 million revolver repayment, and liquidity is roughly $3 billion. Even so, the return to net cash slipped to end-2027 or early 2028, later than the roughly one-year timeline given earlier in the year. Management raised its potential deal-size range, but the pipeline narrowed from about 20 opportunities to just over a dozen.
Investor sentiment remained positive but weakened noticeably, falling from 0.25 to 0.15 heading into the report. The stock has gone essentially nowhere since the prior earnings open, slipping 0.6% to $132.46. Shares sit about 0.9% below the 200-day moving average of $133.63. That flat, average-hugging price action fits a market already weighing decelerating price leverage against an improving project slate, and it leaves little cushion for a miss.
The bottom line is that Wheaton's quarter traded near-term financial momentum for long-term de-risking. The miss partly reflects delivery timing and softer realized prices, not operational failure. Production hit a strong level, and the growth pipeline advanced meaningfully. Still, sequential revenue and earnings are declining, silver headwinds loom at Peñasquito, and deleveraging is taking longer. Until Q4 delivers the required ramp and new mines like Koné reach commercial production, the market is likely to keep weighing a strong long-term story against a softening near-term setup.
Read our earnings preview for Wheaton Precious Metals Corp.: https://www.earningswhispers.com/article/WPM/22414
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 8 hours | |
| 11 hours | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-06 | |
| Oct-01 | |
| Sep-30 | |
| Sep-28 | |
| Sep-17 | |
| Sep-15 | |
| Sep-02 | |
| Sep-01 | |
| Aug-07 |
