Mettler-Toledo Raises Guidance For A Third Time As Lab And China Recovery Broadens, But Earnings Growth Is Holding In A Low-Teens Band
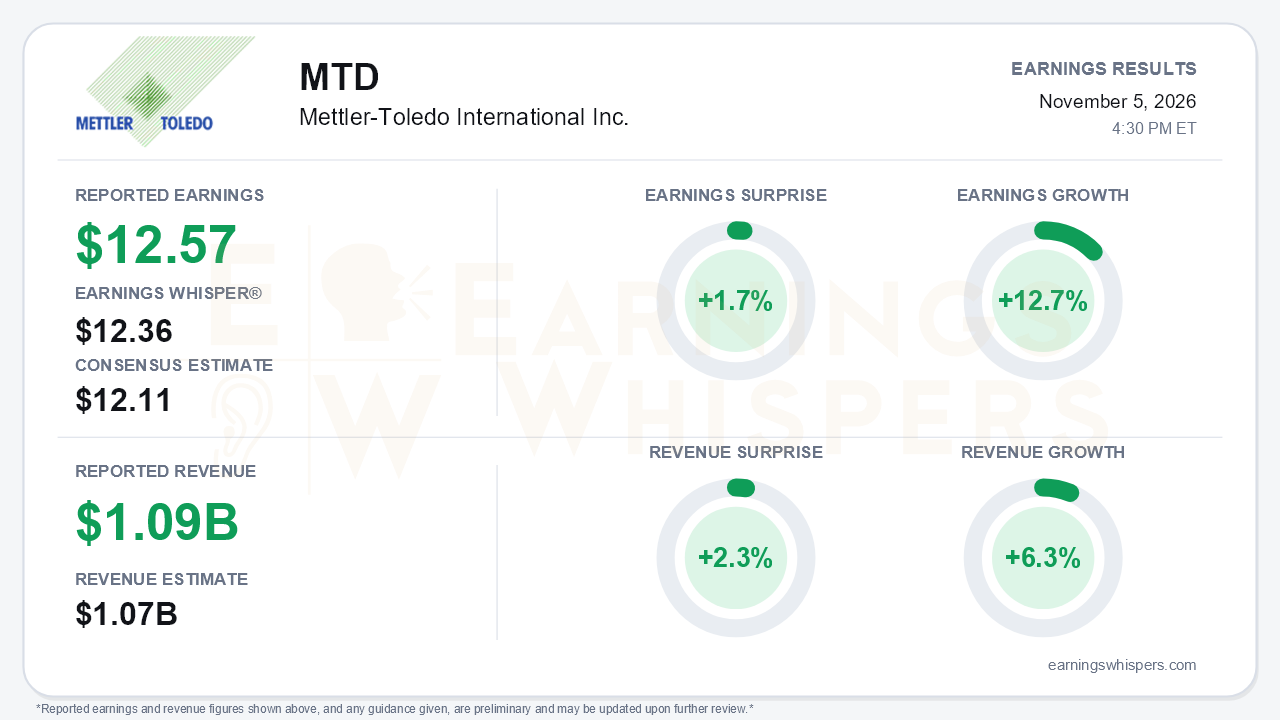
Mettler-Toledo delivered the kind of quarter that rewards investors who bet on a cyclical recovery in lab instruments. Third-quarter adjusted EPS of $12.57 topped the $12.11 consensus and the $12.36 Earnings Whisper number, a 1.7% surprise, and cleared the company's own $12.00-$12.15 guidance range. Revenue of $1.094 billion beat the $1.07 billion consensus by 2.3%. Earnings grew 12.7% and revenue grew 6.3%. The more important development is that management raised full-year guidance for the third time this year and issued an initial 2027 outlook that came in above estimates. The central tension is that sales growth is clearly accelerating while earnings growth is holding at roughly the same low-teens rate. That leaves a stock already up sharply since the last report with less room to surprise on the bottom line.
The beat was driven by volume rather than one-time items. On a GAAP basis, EPS rose to $12.29 from $10.57. Last quarter's tariff-refund noise does not affect the third-quarter comparison. Gross margin improved 60 basis points to 59.8%, better than the 30-basis-point gain in the second quarter. Adjusted operating margin rose 40 basis points to 30.5%, and adjusted operating profit grew 8%. The gap between 8% profit growth and 13% adjusted EPS growth deserves attention. Lower interest expense, a favorable tax-timing adjustment and a diluted share count roughly 2.7% below last year's all helped. SG&A also rose slightly as a percentage of sales, to 24.4%. Buybacks remain a core part of the earnings algorithm, not just an add-on.
The sequential trends are what stand out. Organic growth stepped from 1% in the first quarter to 4% in the second and 6% in the third. China accelerated from 4% to 9% to 13%, and lab demand there has now joined industrial. Management said China is tracking near 10% for the year, against an initial low-single-digit outlook. Global lab organic growth improved from flat to 4% to 6%. Pipettes and liquid handling are rebounding as biotech activity improves, which suggests the recovery is spreading into R&D budgets rather than relying on Asian industrial demand alone.
The softer spots are real, even if secondary. Americas growth slowed to 3% against a tough 9% prior-year comparison. Europe cooled from 4% to 2% and is guided to low-single-digit growth next year amid energy costs and trade disputes. Food retail swung from an 11% gain in the second quarter to a 2% decline. Fourth-quarter local-currency growth of about 5% implies a modest slowdown from 6%, as core industrial laps a 19% comparison and product inspection is expected to be roughly flat. Higher material and transportation costs are the bigger concern. Management guided 2027 gross margin roughly flat, and that outlook assumes tariff rates revert to prior IEEPA levels, which is a policy assumption rather than a certainty. Year-to-date adjusted free cash flow of $652 million trails last year's $689 million, which management attributed to $72 million in higher tax payments.
The guidance still carries the story. Full-year adjusted EPS guidance rose to $47.70-$47.90 from $47.15-$47.50, compared with $46.05-$46.70 at the start of the year. Fourth-quarter guidance of $14.84-$15.04 implies 11% to 13% growth. For 2027, management expects about 5% local-currency growth, adjusted EPS of $52.50-$53.50 (10% to 12% growth), operating margin expansion of 70 to 90 basis points, about $950 million in free cash flow and $950 million in buybacks. Management described onshoring activity, which produced some early revenue in the third quarter, and AI-driven "self-driving lab" demand as upside not included in the budget. Monday's investor day is the next venue for testing that narrative.
The market had already anticipated much of this. Shares are up 14.6% since the open after the July report and sit about 25% above the 200-day moving average. Investor sentiment moved from slightly positive to slightly negative, a modest shift that suggests some fatigue after a strong run rather than outright skepticism. With the stock extended, bears have legitimate ammunition: the 2027 EPS growth guide is no faster than this year's, and margin expansion is constrained by input costs.
The bottom line is that Mettler-Toledo's recovery is broadening across China, lab and biotech, and management's steady guidance raises make the growth story credible. The quarter did not show earnings acceleration, however. Low-teens EPS growth supported by buybacks, flat gross margin assumptions for 2027 and a stock trading well above its long-term trend mean the setup now depends on whether the onshoring and AI-lab upside can turn top-line momentum into faster earnings growth.
Read our earnings preview for Mettler-Toledo International Inc.: https://www.earningswhispers.com/article/MTD/22343
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-05 | |
| Nov-05 | |
| Oct-30 | |
| Oct-28 | |
| Oct-12 | |
| Oct-09 | |
| Sep-02 | |
| Aug-03 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-06 | |
| Jun-04 | |
| May-09 |
