Koppers Misses Badly And Cuts Guidance A Third Time As Input Costs Swamp Volume Gains, Leaving Record Cash Flow And 2027 Repricing To Carry The Story
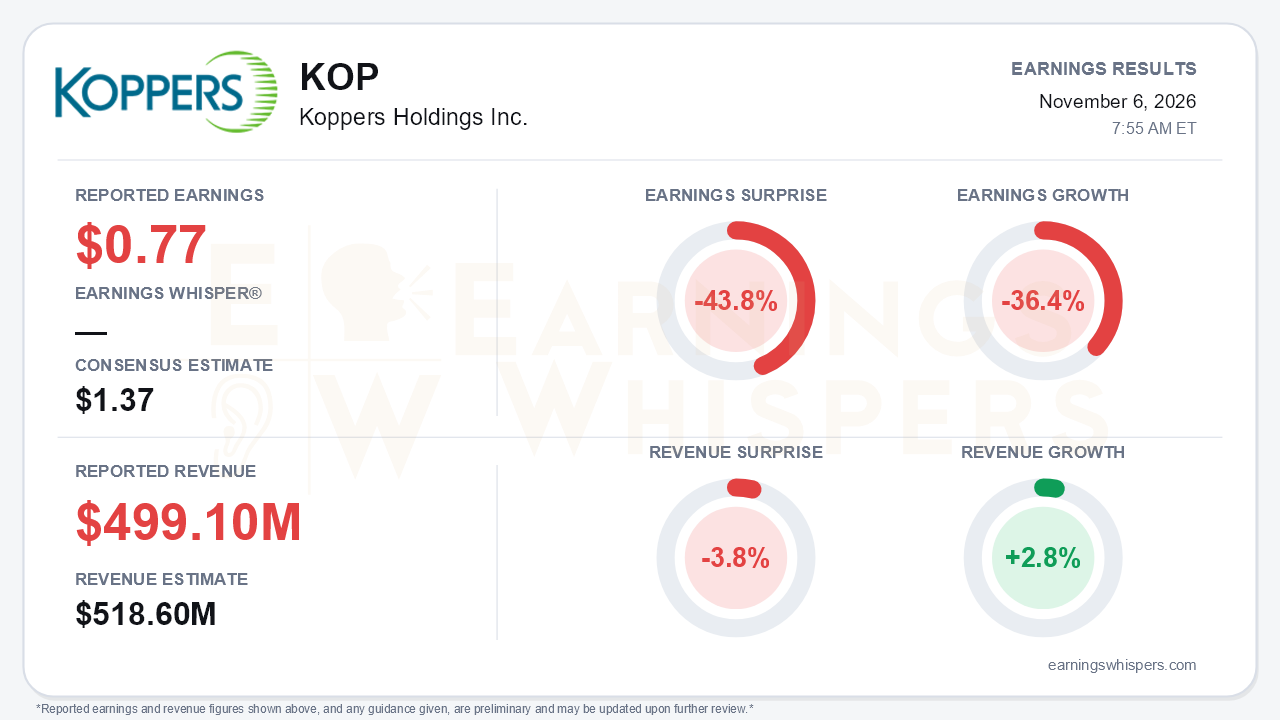
Koppers Holdings (NYSE: KOP) delivered a third-quarter miss that was less about demand than about cost. Adjusted EPS of $0.77 fell 43.8% short of the $1.37 consensus and was down 36.4% year over year. Revenue of $499.1 million rose 2.8% but still missed the $518.6 million estimate by 3.8%. The decline is also steepening. Nine-month adjusted EPS of $2.70 compared with $3.38 a year ago, so the third quarter erased a larger share of prior-year earnings than the first half did. Management then cut full-year guidance for a third consecutive call. That is the central tension: volumes are growing, self-help is ahead of plan and cash generation is at record levels, yet raw-material and logistics inflation is outrunning every one of those offsets.
The segment detail shows how narrow the profit base has become. Performance Chemicals was the only bright spot. Sales rose 11.9% on 10% volume growth tied to share gains and restocking, and adjusted EBITDA climbed to $29.6 million from $26.1 million. Railroad and Utility Products was flat on sales, but EBITDA fell 23.6% to $22.3 million as Class I crosstie price concessions ate into results. Carbon Materials and Chemicals was the real damage. Its EBITDA collapsed 60.9% to $6.1 million and its margin shrank to 5.8% from 14.4%, driven by $9.0 million of higher raw-material costs, poor-quality tar receipts and utilization losses tied to the accelerated Stickney closure. Consolidated adjusted EBITDA fell 18.2% to $58.0 million, with the margin compressing to 11.6% from 14.6%. GAAP results tell a similar story at $0.75 per diluted share. The GAAP picture for the year, however, is skewed by $233 million of impairment and restructuring charges, which have pushed nine-month results to a $6.55 loss and cut shareholders' equity to $402.5 million from $574.0 million.
The call made clear the pressure is not finished. Input costs were roughly a $16 million year-over-year headwind, with coal tar up about 30%. Performance Chemicals' margin, the company's best line, slid to about 18% from roughly 22% in the second quarter, and management guided it lower again in the fourth quarter as copper hedges roll off. Adjusted EBITDA guidance now stands at $220-225 million, down from $240-250 million last quarter and $250-270 million at the start of the year. Adjusted EPS guidance fell to $3.10-3.25 from $3.80-4.20, and sales guidance sits at the low end of the prior range near $1.9 billion. Against nine-month adjusted EPS of $2.70, the new range implies a weak fourth quarter, and a higher 31% tax rate adds to the drag.
The case for patience rests on 2027 and on cash. About 80% of Performance Chemicals' 2027 book has already been repriced from January 1, covering copper, oil and freight inflation with some cushion, and additional industrial share gains are booked. Stickney distillation ended ahead of schedule, and Nyborg is now supplying most railroad creosote. Florence idling completes this quarter. Catalyst program benefits reached $42 million year to date, above the original $20-40 million target. Free cash flow hit a record $92 million year to date, and full-year free cash flow guidance edged up to $115-135 million. The quality of that cash deserves scrutiny, though. Much of the improvement came from working capital, including a $32.9 million swing in payables, rather than earnings. Net leverage also rose to 3.7x from 3.5x despite $31 million of debt reduction, because EBITDA is shrinking faster than debt. Bears also point to the uncertain carbon recovery and a Class I pullback heading into 2027.
The market had largely anticipated trouble. Shares fell 18.5% from the open after the August report to $39.64. That leaves them about 5% below the 200-day moving average and just 1.7% above an inter-earnings low set the day before this release. The stock has surrendered the entire spike to a 52-week high of $53.00 that followed last quarter's report. Investor sentiment weakened meaningfully, sliding from 0.23 to 0.04. It remains barely positive, which suggests investors have shifted from cautious optimism to near-neutral rather than outright capitulation.
The bottom line is that Koppers is asking investors to look through a lost 2026 toward a repriced 2027. The repricing evidence in Performance Chemicals is concrete, and the cash flow is real enough to fund buybacks and debt paydown. But three straight guidance cuts, deteriorating margins in the strongest segment and rising leverage give skeptics legitimate ammunition. Until January pricing shows up in reported margins, credibility will be the stock's binding constraint.
Read our earnings preview for Koppers Holdings Inc.: https://www.earningswhispers.com/article/KOP/22491
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Nov-04 | |
| Oct-30 | |
| Oct-29 | |
| Oct-23 | |
| Aug-31 | |
| Aug-10 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-23 | |
| Jun-25 |
