Nutex Health Edges Past Estimates As Visit Growth Surges, But Falling Revenue Per Visit, Margin Compression And IDR Legislative Risk Cloud The Quarter
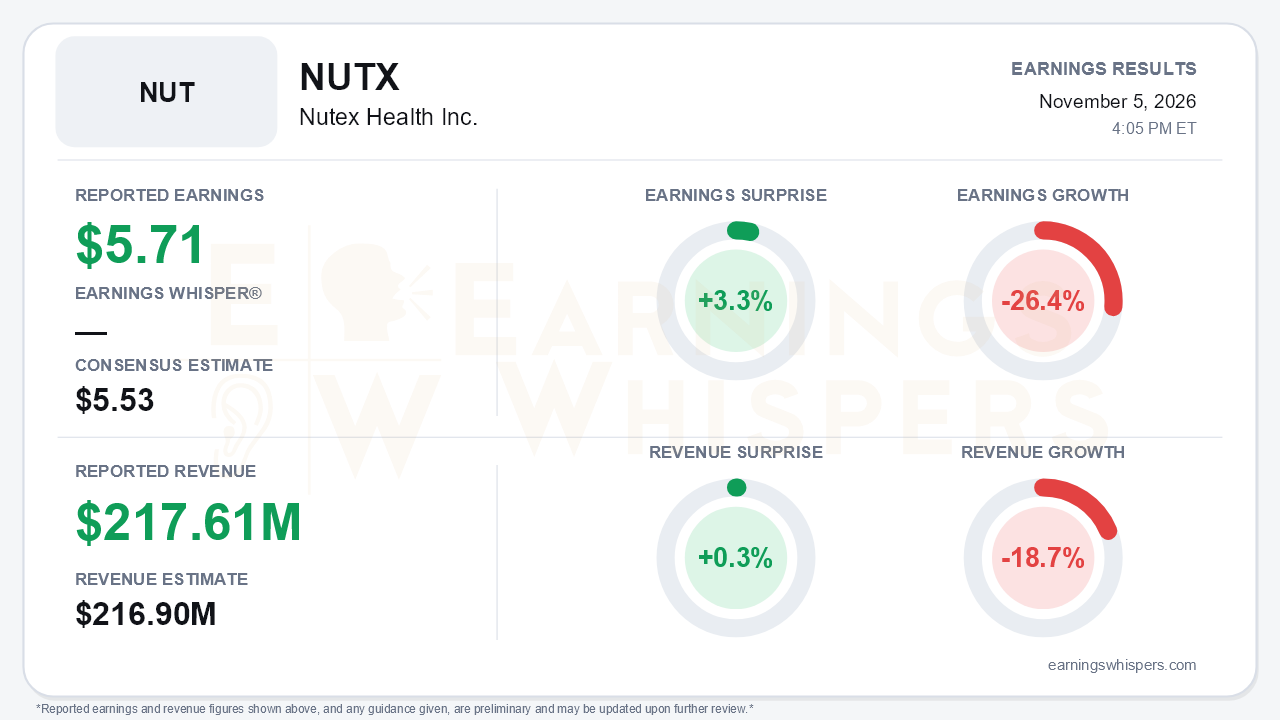
Nutex Health (NASDAQ: NUTX) delivered a modest third-quarter beat, but the quarter's real story sits beneath the headline. The company earned $5.71 per share on revenue of $217.61 million, topping the $5.53 consensus by 3.3% and edging past the $216.9 million revenue estimate by 0.3%. Those are narrow beats on shrinking numbers. Earnings fell 26.4% from a year ago and revenue declined 18.7%. The central tension is that patient volume is accelerating sharply while the economics of each visit, along with margins and adjusted EBITDA, are moving the other way.
The quality of the beat deserves scrutiny. Gross profit fell to $101.5 million from $154.9 million a year earlier. Gross margin dropped to 46.7% from 67% in the second quarter. Operating income fell about 41% to $77.1 million, a much steeper decline than the drop in attributable net income. Two items cushioned the bottom line. Income attributable to noncontrolling interests fell to $17.1 million from $41.4 million, and lower stock-based compensation helped as well. The share count also shrank to 6.86 million from 7.09 million at year-end after roughly $50.7 million of repurchases. Cost pressure showed up across the expense lines: payroll rose to $48.4 million from $38.8 million, and G&A rose to $17.0 million from $11.3 million.
Adjusted EBITDA was $63.9 million, down from $98.5 million a year ago and $90 million in Q2. Q2 had been flattered by a $38.4 million retroactive HaloMD credit. Nine-month adjusted EBITDA is now down 13%, compared with up 2% at the half-year mark. Year-to-date GAAP profit also includes a $52.3 million non-cash change in estimate tied to the HaloMD amendment, which added $4.83 per diluted share. Management attributes the revenue decline to favorable 2025 items, namely updated collection data on 2024 services and later-reconciled ineligible charts. That explanation is credible, but it does not account for the margin slide.
The operating picture is genuinely mixed. Hospital visits rose 18.1% to 54,622 and same-hospital visits climbed 12.4%. That compares with 9.6% and 6.3% in Q2, and 3.1% and 0.6% in Q1, and management credited its business-development investment. Demand is clearly improving. Monetization is not keeping pace:
- Revenue per visit slipped to roughly $3,800, below the $4,000–$4,200 range management reiterated in each of the first two quarters.
- Physician-side collections are trending down.
- The cited IDR win rate eased to over 80% from over 85%.
- Facility costs rose to 53.3% of revenue and G&A to 7.8%.
- Employee turnover climbed to 9.6% from 6.8%.
The growth pipeline also slipped. Expected 2026 openings were cut from three to two, with West Little Rock no longer listed, and the next four projects now point to late 2027 or early 2028.
The reimbursement backdrop is where the bull and bear cases collide. On the positive side, management highlighted several developments:
- a Fifth Circuit en banc ruling against "ghost rates" in QPA calculations;
- a Virginia ruling extending provider-favorable IDR decisions to at least seven states;
- Kansas and Michigan attorney general suits against insurers;
- CMS audits finding payer noncompliance;
- company support for the Murphy Bill, which would add penalties for unpaid IDR awards.
Management also hinted at the first formal 2027 guidance. Bears have legitimate ammunition, however. The Pallone Bill would eliminate IDR beginning in 2028 and make QPA the final payment. With Democrats now controlling Congress, that is a structural risk to a model in which 50–60% of billable visits run through IDR.
The balance sheet remains a real strength. Cash rose to $249.9 million from $207.1 million at the end of Q2, against just $34.2 million of long-term debt. Nine-month operating cash flow reached $188.1 million, up 6%. Quarterly operating cash flow did ease to $78.3 million from $99.5 million, and receivables climbed to $356.1 million.
Investors entered the report far more constructive than they were three months ago. Earnings Whispers sentiment improved from -0.48 to -0.21, a meaningful move, though it remains in negative territory. The stock has rallied 17.5% since the opening after the August report to $193.64. It now sits about 28% above its 200-day moving average of $151.15. That run means the market had already priced in some of the volume acceleration and favorable court rulings before this print, which raises the bar for a quarter whose margins went the wrong way.
The bottom line is that Nutex cleared a low bar while revealing a business that is winning more patients but earning less from each one. Accelerating visit growth, rising cash and a string of favorable legal rulings support a credible growth story. Falling revenue per visit, compressed margins, delayed hospital openings and a live legislative threat to IDR make the setup more complicated than the beat implies. Whether management issues formal 2027 guidance, and how it frames per-visit economics, will likely matter more than this quarter's few cents of upside.
Read our earnings preview for Nutex Health Inc.: https://www.earningswhispers.com/article/NUTX/22351
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Oct-28 | |
| Oct-19 | |
| Sep-22 | |
| Sep-10 | |
| Aug-31 | |
| Aug-25 | |
| Aug-18 | |
| Aug-14 | |
| Aug-06 | |
| Jul-21 | |
| Apr-30 | |
| Apr-22 | |
| Mar-11 |
