EZCORP's Fiscal Year-End Report Tests Whether Core Pawn Strength Can Outrun Fading Scrap Gains
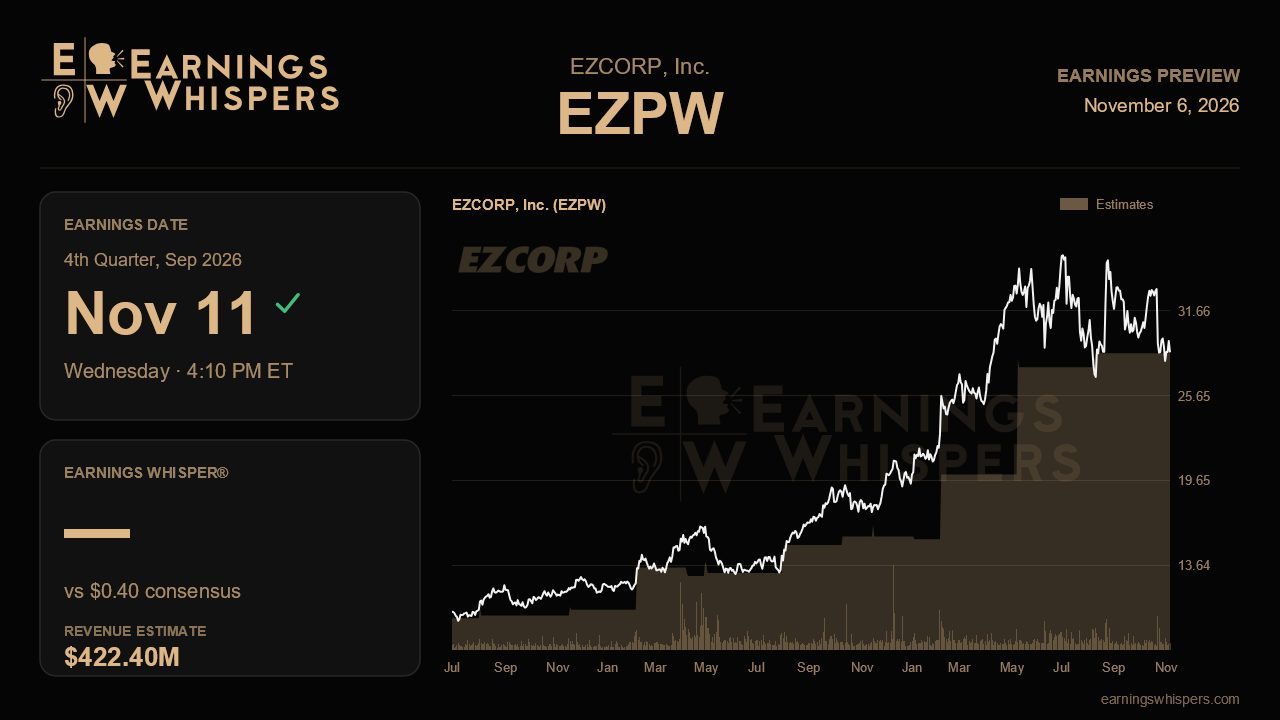
EZCORP heads into its fiscal fourth-quarter report with a clean narrative and a messy math problem. Last quarter, management argued that its earnings were driven mostly by core pawn operations rather than the gold-scrap windfall that lifted the prior period. The upcoming release, due after the close on November 11, will show whether that claim holds up as scrap margins keep sliding toward historical norms.
Wall Street expects earnings of $0.40 per share on revenue of $422.4 million. That would mean roughly 18% EPS growth and 25% revenue growth from a year ago, solid by any measure. The sequential picture is more telling. Revenue is expected to edge up from the $418.7 million reported last quarter, yet EPS is forecast to fall from $0.47. The gap between those two lines is essentially the Street's estimate of how much scrap normalization and rising expenses will cost. EZCORP does not issue formal guidance, so the closest thing to a roadmap is management's own framing. Consolidated scrap margin dropped to 26% from 38% the quarter before, and the company signaled further drift toward a long-term range of 15% to 20% if gold prices stay put. Consensus appears to have absorbed that message.
The real test is whether the underlying engine keeps accelerating fast enough to fill the hole. Management described pawn loan demand as exceptionally strong in both the US and Latin America, and regional EBITDA margin expanded 240 basis points to 22% last quarter. US merchandise margin reached its highest level since 2022, climbing steadily over the past year. Confirmation this quarter would look like continued growth in same-store pawn loans outstanding, merchandise margins holding near those recent highs, and Latin American jewelry mix staying around half of the loan book. A pullback in retail margin would be a bigger warning than any scrap decline, because it would suggest last quarter's pricing gains were not as durable as management implied. Investors should also watch pawn yield, which has been compressing as average loan sizes rise in markets like Texas. Modest compression is tolerable; a sharper drop would undercut the quality story.
This is also the first quarter with SMG fully owned, up from about 74.6% effective ownership earlier in the year. That should let more of SMG's profit accrue to EZCORP shareholders and, according to management, frees the business to shift from scrap reliance toward fuller jewelry cases and higher retail margins. Early evidence of that cultural and systems transition, along with contributions from the 33 Guatemala stores and recent Mexico deals, will help explain how much of the revenue growth is acquired versus organic. The flip side is cost. Expenses have been climbing sequentially with de novos, acquisitions and integration work, and cash fell to $311 million after SMG debt retirement and deal spending. Commentary on the Latin American de novo opportunity flagged for fiscal 2027 will shape how investors think about next year's spending.
Sentiment has warmed considerably. Investor mood is only slightly bearish now, compared with a markedly more pessimistic reading ahead of the last report. The stock is up less than 1% since then, but that beats the S&P 500 by about five and a half points. Still, shares at $28.72 sit below the 200-day moving average and closer to the bottom of the post-earnings range than the $35.92 high, suggesting the market has not fully bought into the core-pawn thesis.
That leaves a clear question. If pawn growth, merchandise margins and SMG's early contribution can offset a falling scrap line while keeping expenses in check, the quality-over-windfall narrative survives intact. If earnings slip mainly because gold profits faded and costs rose, the market may conclude last quarter's optimism leaned on tailwinds that are now gone.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-03 | |
| Jul-23 | |
| Jun-23 |
Dow Jones Futures: Nasdaq Breaks Key Support; FedEx, Cerebras Tumble Late With Micron Due
EZPW
Investor's Business Daily
|
| Jun-23 | |
| May-06 | |
| May-06 | |
| May-04 | |
| Mar-23 | |
| Mar-10 | |
| Mar-06 |
