Imunon's Cash Runway, Not Its Quarterly Loss, Defines The Third-Quarter Test
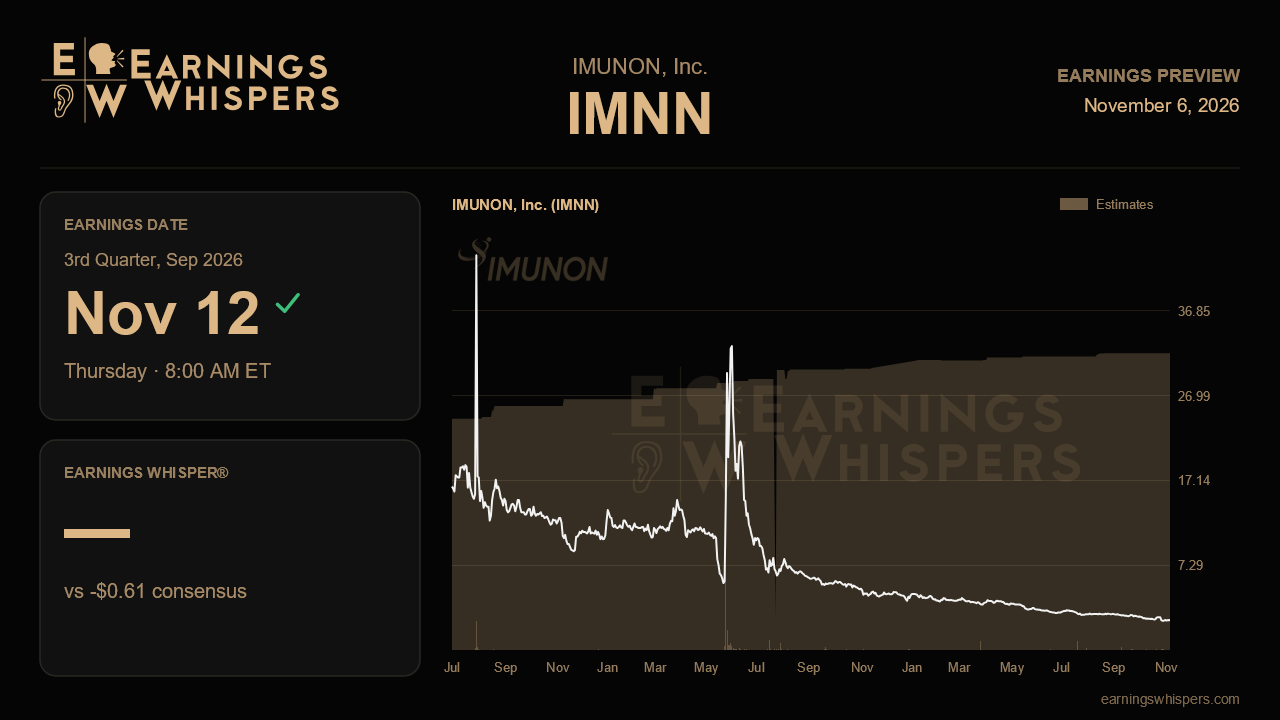
Imunon heads into its third-quarter report with a split personality. The clinical story has rarely looked better: Phase 3 enrollment is outrunning internal plans and the company finally attached hard numbers to its MRD program. The balance sheet tells a different story. Management said last quarter that cash would last only through the end of the year, and the stock has lost 44% since then. That makes this report less about the size of the loss and more about whether Imunon can show a credible bridge into 2027.
The Street expects a loss of $0.61 per share. That would be a 47% improvement from the $1.16 loss a year ago, which reflects the cost discipline management has been showing. It would also be a modest step back from the $0.54 loss last quarter. There is no revenue to speak of and no formal financial guidance to measure against. In practice, the per-share figure matters less than the cash line and what management says about funding. Last quarter, operating cash burn fell to $3.0 million from $4.0 million, and G&A dropped about 20% from a year earlier to $1.3 million. If burn stays near $3 million, simple arithmetic leaves a thin cushion from the $6.9 million reported at the end of June. Any slippage back toward the $4 million pace would tighten things further. Imunon needs to show that its lower spending rate is durable, not a one-quarter dip.
The operational narrative is where Imunon has earned some credibility. In Ovation 3, management reported enrollment of roughly 0.5 patients per site per month. That compares with a 0.3 internal assumption and a historical benchmark near 0.2. About 35% of planned sites were active or activating, and the company had identified roughly twice the sites it needs. To validate that story, this quarter should show a higher share of sites up and running and an enrollment rate holding near last quarter's pace. The completion target is a separate concern. It has drifted from late 2028 to the first quarter of 2029, and most recently to the first half of 2029. Another push would undercut the argument that faster per-site enrollment translates into a faster trial. A firm restatement, or a pull-forward, would strengthen it.
The MRD data are the newest piece of the bull case. The preliminary figures compared Imunon's arm with the control arm:
MRD positivity: 44% versus 67%
ctDNA clearance: 87.5% versus 62%
No evidence of disease: 100% versus 56%
The September R&D Day and the November SITC presentation give management two chances to show whether these signals are deepening or simply being restated. Ovation 2 median overall survival has held at 14.7 months across three consecutive updates, so the progression that once climbed from 11.1 months has plateaued. Final Ovation 2 survival data are slated for a major meeting in early 2027. Any clarity on timing or venue would help keep that catalyst on the calendar.
Sentiment has tilted from neutral to moderately bullish, a sign that some investors see value in the clinical progress. The share price argues otherwise. At $0.90, the stock trails the S&P 500 by nearly 39 percentage points since the last report and sits well under its 200-day average of $2.19. It is hovering just above its post-earnings low of $0.81, and its entire recent range of $0.81 to $1.75 sits below the prior quarter's band of $1.47 to $2.76. The market is clearly pricing financing risk ahead of trial progress.
Last quarter's June raise used preferred stock and secured notes without warrants, which spared shareholders heavy dilution. Management also acknowledged that more capital is needed to fully fund Phase 3 and overhead. The central question is whether Imunon can pair continued enrollment momentum with a concrete funding path that extends the runway beyond year-end. A clean clinical update with a vague financing answer likely keeps the discount in place. Visible progress on both fronts would be the first real evidence that the improving operational story can outlast the cash constraint.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Nov-02 | |
| Oct-21 | |
| Oct-08 | |
| Sep-29 | |
| Sep-24 | |
| Sep-22 | |
| Sep-10 | |
| Sep-09 | |
| Aug-26 | |
| Aug-11 | |
| Aug-04 | |
| Jul-30 | |
| Jul-23 |
