Dyadic's Q3 Report Must Show Its Cash Lifeline Before Its Product Ramp
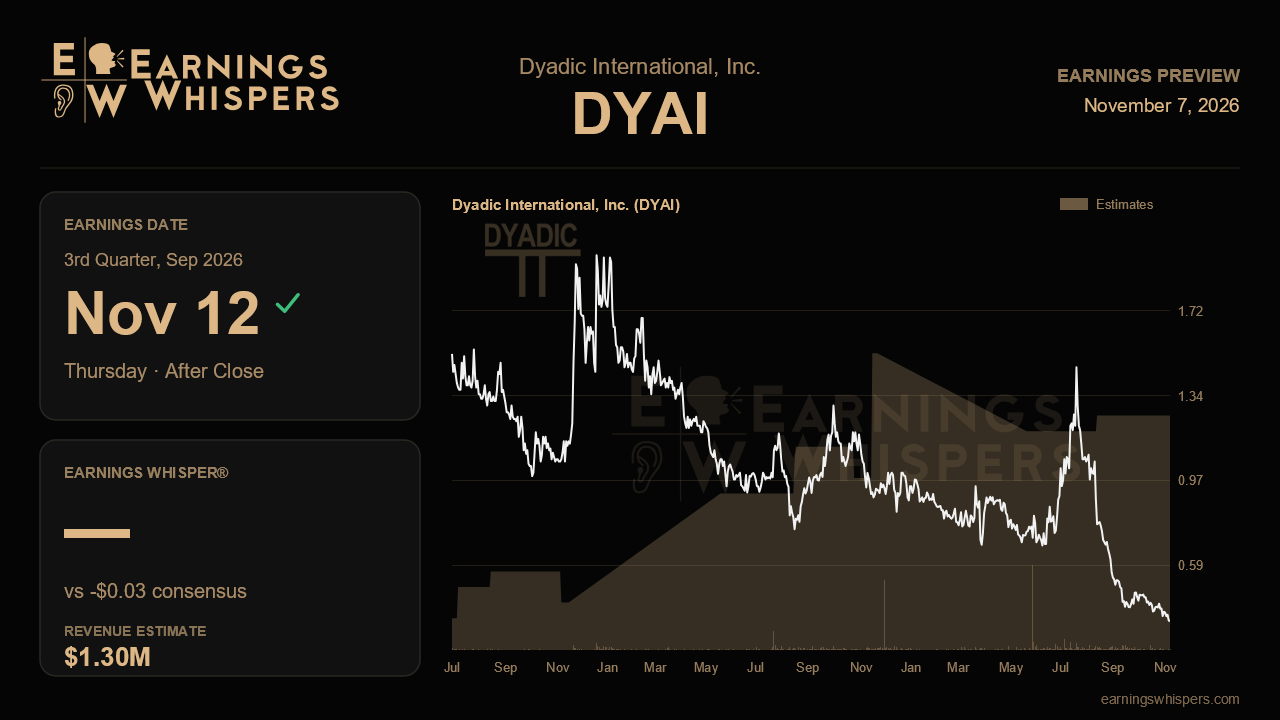
Dyadic International heads into its third-quarter report with an awkward split screen. On one side, the company finally has products moving through distribution channels and partners launching goods built on its C1 platform. On the other, management flagged substantial doubt about its ability to continue as a going concern last quarter, and the stock has lost two-thirds of its value since. That makes this report less about whether revenue ticks up a few hundred thousand dollars and more about whether Dyadic can show that its commercial progress and its balance sheet are heading in the same direction.
The Street is looking for revenue of about $1.3 million, up roughly 13% from the year-ago quarter and a step up from the $961,000 reported last time. Analysts also expect the loss to narrow to about 3 cents a share from 6 cents a year earlier. Management has not provided formal guidance, so there is no range to measure that against. The revenue figure implies modest growth, not a breakout, which seems fair given management's own description of product sales as lumpy and the absence of recurring orders. The sharper improvement in per-share loss deserves scrutiny. A narrower loss could come from tighter spending, but it could also reflect a larger share count if the company has leaned on its at-the-market facility, and those two paths mean very different things for existing holders.
Operationally, last quarter's call gave investors a list of things that should start showing up in the numbers. IBT OEM shipments covering six product opportunities moved from a promise to reality, with follow-on orders after quarter end. Initial pilot sales of recombinant transferrin and growth factors into cultivated meat landed, and management disclosed an 80% productivity gain on transferrin that should cut costs by about 40%. Partners are also commercializing: ProLiant launched AlbuFree DX, the enzymes business is selling non-animal chymosin, and a new industrial cellulase arrived in July. The validating evidence this quarter would be repeat orders from any of these channels, product revenue that grows without help from grant or milestone payments, and some improvement in cost of revenue, which jumped 60% last quarter. If revenue rises mainly because of Gates or CEPI funding, the commercial story has not yet been proven.
The balance sheet is the bigger swing factor. Cash slid from $10.4 million a year ago to $4.8 million at the end of the second quarter, and the going-concern warning replaced earlier assurances of runway into 2027. Management mentioned discussions with major suppliers and pharmaceutical companies about potentially large non-dilutive strategic payments. Any concrete deal, or a clear explanation of how the company funded itself through the quarter, would matter more to the stock than a penny of EPS. Conversely, a further cash decline without a credible funding plan would reinforce the market's skepticism, especially with convertible notes maturing at the end of 2027.
The market has already rendered a harsh verdict. Shares have fallen about 67% since the last report while the S&P 500 slipped about 5%, and at $0.34 the stock sits barely above its post-earnings low of $0.33 and less than half its 200-day moving average of $0.75. Curiously, sentiment has improved to 62.2% bullish from 56.4% before the prior report, suggesting a contingent of holders sees the selloff as overdone. That optimism is not a forecast, but it does mean some buyers are positioned for a relief rally if the funding picture clears.
Ultimately, the question is whether Dyadic can bridge the gap between early commercial traction and financial survival. Evidence of recurring product orders paired with a credible, ideally non-dilutive, path to sustained liquidity would start rebuilding the narrative. Flat product sales and a thinner cash cushion would leave the going-concern warning as the defining story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-07 | |
| Oct-30 | |
| Sep-08 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 | |
| Aug-11 | |
| Aug-04 | |
| Aug-03 | |
| Jul-28 | |
| Jul-24 | |
| Jul-16 | |
| Jul-07 | |
| Jun-29 | |
| Jun-22 |
