GCT Semiconductor Must Show Its Delayed 5G Deployments Are Finally Turning Into Revenue
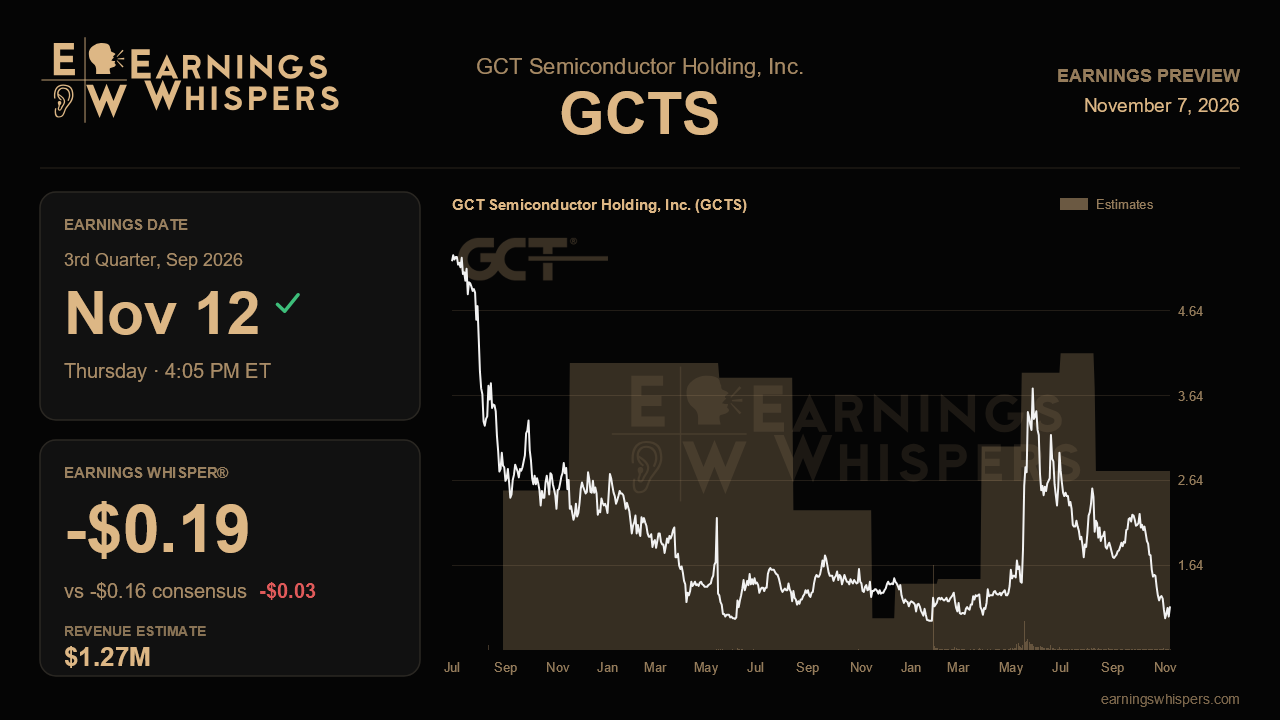
GCT Semiconductor heads into its third-quarter report with a credibility problem of timing rather than demand, at least by management's own account. Last quarter the company shipped 5,100 5G chipsets, up 71% sequentially and the third straight quarter of rapid unit growth, yet revenue slid to $1.0 million and gross margin turned negative as customer restructuring and macro factors pushed several deployments out by one to two quarters. The upcoming release, due after the close on November 12, lands squarely inside that one-to-two-quarter window, which makes it the first real test of whether those launches slipped or stalled.
The Street is looking for revenue of about $1.3 million, nearly triple the $0.4 million posted a year ago and a modest step up from the prior quarter. Consensus calls for a loss of $0.16 per share, a 36% improvement from the year-ago loss of $0.25. The Earnings Whisper sits a bit lower at a loss of $0.19, suggesting the more skeptical crowd expects a deeper loss than published estimates and that the bar has drifted down. The company offered no formal numeric guidance, but management did say second-half shipments should exceed the first half, and it has secured wafer capacity through the first quarter of 2027 in anticipation of what it described as a relatively large ramp. A revenue figure only marginally above last quarter would sit uneasily beside that framing.
Three items should carry more weight than the headline numbers. First, unit shipments and customer breadth: the shipment base widened from essentially one primary customer late last year to roughly four customers across four applications, including a newly added push-to-talk phone. Continued sequential unit growth with revenue finally following would validate the timing argument; flat units or a shrinking customer list would challenge it. Second, gross margin needs to climb back into positive territory after swinging from 49% in the first quarter, which was flattered by one-time licensing revenue, to below zero. Without that, scale offers little operating leverage. Third, cash. The company ended the second quarter with $30.2 million after leaning on its at-the-market program, now expanded to $120 million, while lifting its quarterly burn outlook to $9 million to $9.5 million, partly from wafer prepayments. Burn at or below that range would ease dilution worries; anything higher shortens the runway and invites more share issuance.
Reported EPS deserves some caution. Last quarter's net loss of $20.4 million included a $12.3 million warrant fair-value charge, and those mark-to-market swings can move per-share results sharply in either direction. The adjusted EBITDA loss, introduced as a new metric last quarter at $6.6 million, is likely a cleaner read on whether the core business is improving. Updates on the newly signed UAV customer serving consumer and defense markets, and any progress toward naming the satellite partner, which management targeted for late this year or early next, would add substance to the broader pipeline story.
The market has already rendered a harsh verdict. Shares have fallen 44% since the last report against a 5.1% decline in the S&P 500, and at $1.16 the stock trades well below its 200-day moving average of $1.81, closer to the bottom of its post-earnings range of $0.96 to $2.27 than the top. Bullish sentiment has roughly halved, to 32.5% from 62.3% ahead of the prior report. Expectations, in other words, are depressed, which lowers the hurdle for a relief move but also reflects real doubt about execution.
Ultimately, this report hinges on whether the deployments management described as delayed show up as revenue, positive gross margin and a firm outlook for the fourth quarter. If they do, the slip looks like a temporary detour. If timing is cited again as the swing factor, investors will reasonably start treating it as a demand question instead.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-07 | |
| Oct-29 | |
| Aug-26 | |
| Aug-11 | |
| Aug-10 | |
| Jul-27 | |
| Jun-23 | |
| May-27 | |
| May-27 | |
| May-13 | |
| May-12 | |
| May-07 | |
| Apr-28 | |
| Mar-25 | |
| Mar-25 |
