BeOne Medicines Beats Big And Raises Guidance Again As BRUKINSA Tops $1 Billion In The U.S., But The 2027 Setup Gets Harder
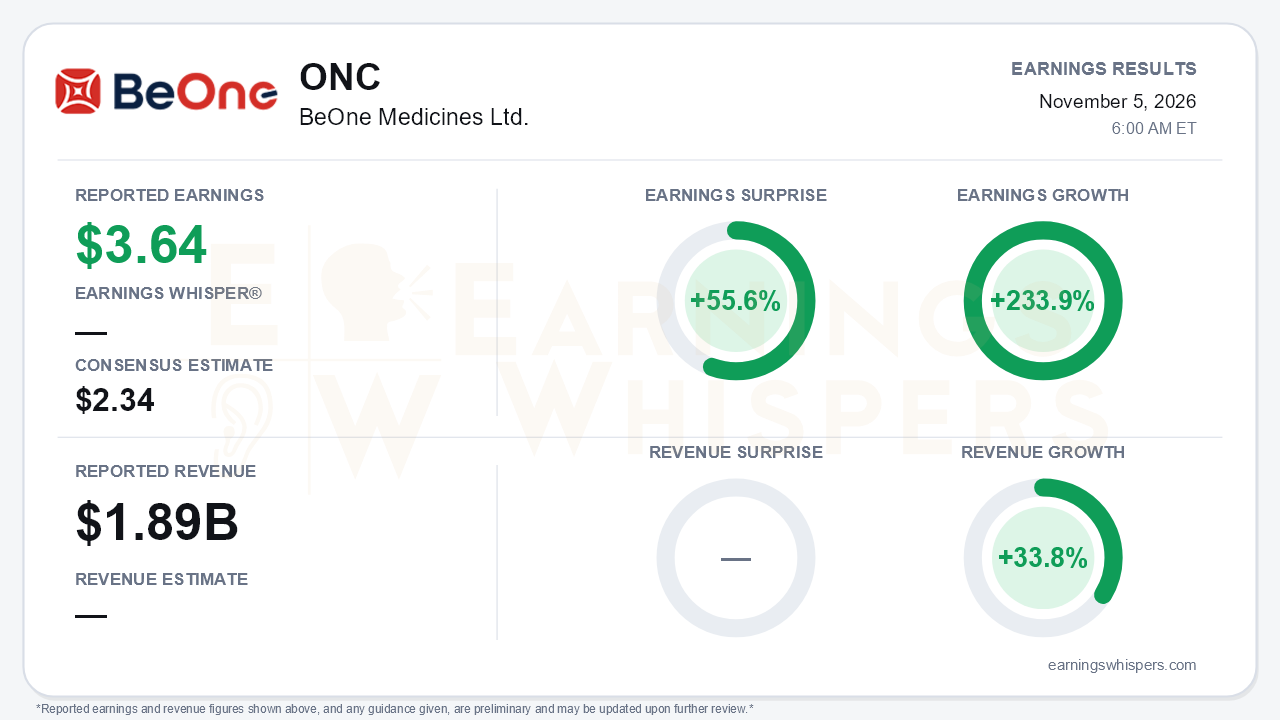
BeOne Medicines delivered another large beat. Earnings Whispers normalized EPS came in at $3.64, against a $2.34 consensus, a 55.6% surprise. Earnings grew 233.9% year over year. Revenue rose 33.8% to $1.89 billion. On the company's own reporting basis, diluted GAAP EPS per ADS was $3.28, up from $1.09, and non-GAAP EPS was $4.59, up from $2.65. The normalized figure falls between the two, so readers should note which basis is being cited.
More important than the beat itself was the fourth consecutive raise to full-year guidance. Revenue guidance has climbed from $6.2 to $6.4 billion at the start of the year to $6.9 to $7.0 billion now. GAAP operating income guidance has gone from $700 to $800 million to $1.2 to $1.3 billion. The central tension is that this raise comes alongside a less generous outlook for 2027, along with signs that Q3 itself was flattered at the margin.
The quality of the quarter is mostly high. Total revenue growth accelerated to roughly 33% from about 30% in Q2. Product revenue was driven by BRUKINSA:
- Global BRUKINSA sales reached about $1.4 billion, up 34%.
- U.S. sales crossed $1 billion for the first time, up 36%, compared with $893 million in Q2 and $761 million in Q1.
- TEVIMBRA growth accelerated to 28% from 18% in Q2.
- Europe grew 41% and rest of world grew 58%.
Operating leverage was striking. GAAP operating income rose 157% to $419 million, as non-GAAP operating expenses grew 24% against 34% revenue growth. Free cash flow was $474 million, and cash rose to $5.87 billion.
There are blemishes. Management said Q3 included roughly a $50 million U.S. BRUKINSA order-timing benefit. GAAP gross margin of 88% improved from 86% a year ago but slipped from just under 90% in Q2, partly because of a $22 million impairment tied to discontinuing POBEVCY promotion. Adjusted gross margin was 90%.
The guidance math deserves scrutiny. Nine-month revenue was $5.11 billion. The $6.9 to $7.0 billion target therefore implies flat-to-down fourth-quarter revenue against Q3's $1.89 billion. That pattern is consistent with the timing pull-forward and conservative guidance-setting, but it is not a reacceleration story into year-end.
The bigger adjustments concern 2027:
- Management guided to only modest margin expansion next year.
- Opex growth is expected to be at least consistent with recent years.
- Medicare Part D manufacturer liability is expected to turn this year's U.S. net-price tailwind into a flat-to-modest headwind.
- Xgeva biosimilar erosion has begun, with volume-based procurement exposure for Xgeva and Kyprolis beyond 2026.
- The BTK degrader tacabrutideg met its pivotal Phase 2 endpoint, but its accelerated-approval filing slipped from end-2026 to mid-2027 after the FDA requested more follow-up.
- CADENCE-302 was downgraded to Phase 2.
The call still preserved a credible growth story, and the pipeline arguably did more de-risking than any single quarter has recently.
- **MANGROVE:** BRUKINSA plus rituximab in first-line mantle cell lymphoma is filed in the U.S., EU and China, with FDA priority review and an ASH plenary slot.
- **Sonrotoclax:** BEQALZI is launching in the U.S. in relapsed/refractory MCL.
- **ESMO solid-tumor data:**
- GPC3x4-1BB bispecific: 36% response rate in second-line-plus liver cancer.
- CEA ADC: 60% confirmed response rate.
- PRMT5 inhibitor: 38.5% response rate with intracranial activity in MTAP-deleted lung cancer.
- **Late-stage expansion:** Phase 3 starts are slated for late 2026 and early 2027, the CDK4 Phase 3 was upsized to pull in its readout, and the Revolution Medicines collaboration adds RAS(ON) combinations.
- **Tax:** a potential valuation-allowance reversal in Q4 could produce a material one-time GAAP tax benefit, which investors should separate from operating earnings.
The market had largely anticipated strength. Shares were $406.96, up 23.7% since the open following the August report and about 25% above the 200-day moving average. They sit within 1% of a new 52-week high of $410.71 set the day after the release. Price and AVWAP trend readings are positive, while sequential growth is neutral, which fits a Q4 guide that implies a plateau. Investor sentiment remained positive but cooled, slipping from 0.29 to 0.19. That suggests some investors are weighing the 2027 headwinds against the headline beat.
The bottom line is that BeOne produced a high-quality quarter with accelerating BRUKINSA and TEVIMBRA growth, real operating leverage and a deepening late-stage pipeline. Even so, the setup is more complicated than a 55.6% surprise implies. With shares near record highs, investors must now underwrite a flattish Q4, pricing pressure from Part D, slower margin expansion and a delayed degrader filing, all against pipeline catalysts that remain promising but mostly lie in 2027.
Read our earnings preview for BeOne Medicines Ltd.: https://www.earningswhispers.com/article/ONC/22159
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-08 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Oct-28 | |
| Oct-24 | |
| Oct-23 | |
| Oct-22 |
BeOne Stock Breaks Out With Visions Of 177% Earnings Growth. This Telltale Clue Bodes Well.
ONC
Investor's Business Daily
|
| Oct-22 | |
| Oct-19 | |
| Oct-19 | |
| Oct-15 |
Big Pharma Is Pouring Billions Into a New Class of 'Protein Degrader' Drugs
ONC +6.43%
The Wall Street Journal
|
| Oct-01 | |
| Aug-31 |
