PEDEVCO Faces A Steep Sequential Reset As Its New 20-Well Drilling Push Gets Its First Real Test
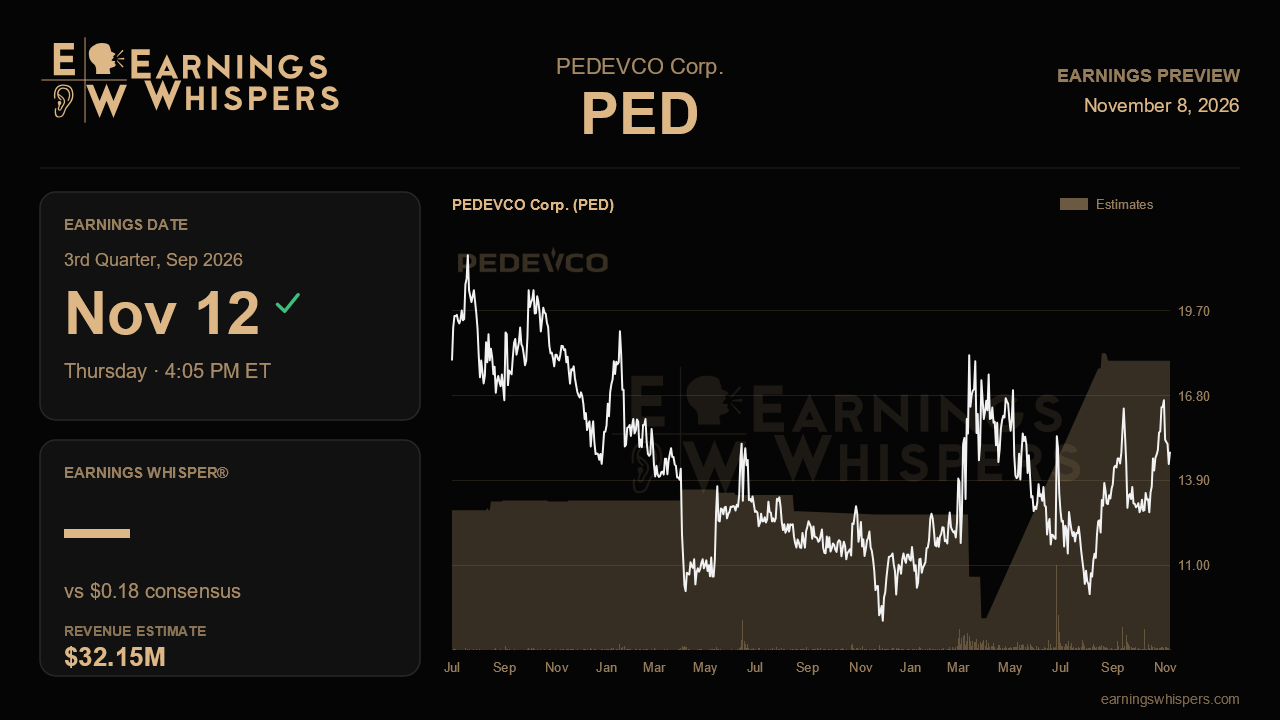
PEDEVCO heads into its third-quarter report with a split personality. On paper, the numbers will look explosive: Wall Street expects revenue of roughly $32.2 million, up about 362% from the $7.0 million the company booked a year ago. That comparison mostly reflects the merger that reshaped the company, though, not organic growth. The more telling figure is the sequential one. Consensus revenue sits about 30% below the $46.1 million delivered last quarter, and the $0.18 EPS estimate is well under the prior quarter's $0.32. The Street is bracing for a step down, and the question is whether management's more confident tone from the last call survives it.
That expected decline is not a surprise to anyone who followed management's framing. Full-year adjusted EBITDA guidance of $60 million to $70 million has been reiterated on three consecutive calls, and the first half already produced $36.8 million. Simple arithmetic says the second half needs only about $23 million to $33 million, or roughly $12 million to $17 million per quarter, compared with $18.7 million in the second quarter. In other words, the guidance itself already assumed a softer back half, and consensus appears to be sitting comfortably within that framework rather than stretching beyond it. A result near the top of that implied range would suggest the company could reach the upper end of its annual outlook. A quarterly figure at the bottom would leave little cushion for the fourth quarter.
The operational story is where this report matters most. Production fell 16% sequentially to 6,800 barrels of oil equivalent per day last quarter as the flush from 31 late-2025 DJ Basin wells faded, a decline management had telegraphed. It also warned that July volumes would dip further because nearby wells were shut in for the Hastings DUC completion and accelerated optimization work. So the real test is not whether production fell again, but whether it recovered later in the quarter once Hastings came online and the shut-in wells returned. Evidence that volumes stabilized by September would validate the claim that July was a temporary air pocket. Continued erosion would challenge it.
Costs are the second checkpoint. Management pulled its optimization program forward into the summer, targeting up to $1 million a month in lease operating expense savings through pump conversions, recompletions, cleanouts and compression. Per-unit costs rose last quarter because absolute spending held flat against lower volumes. Early signs of lower absolute LOE would show the program is working ahead of the 2027 run rate management is promising. Hedging also deserves attention after $8.1 million in realized settlement losses last quarter, when spot prices of about $94 per barrel ran well above contract strikes. The company's revenue story has leaned heavily on pricing, which makes realized prices a major swing factor.
Then there is the genuinely new catalyst: a development program of 20 or more gross wells that management said could be funded within cash flow, helped by resolution of Wyoming BLM litigation that opened permitting for top-tier Powder River locations. Details were promised within weeks of the last call, so this report should show how capital spending is ramping and whether the balance sheet, with net debt near $73 million and leverage around 1.0 times, keeps improving while drilling accelerates.
The market has been generous. Shares are up 17.2% since the last report while the S&P 500 fell 5.6%, and at $14.88 the stock sits above its 200-day average of $13.73, though well below its post-earnings high of $18.00. Sentiment has nonetheless cooled, sliding to 13.1% bearish from 5.8% bearish a quarter ago, which suggests some unease about the sequential drop. Ultimately, the report hinges on whether PEDEVCO can show that volumes have bottomed and costs are falling just as its drilling program ramps, proving the company can grow without relying on elevated oil prices to do the heavy lifting.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-08 | |
| Oct-29 | |
| Sep-24 | |
| Sep-16 | |
| Aug-14 | |
| Aug-14 | |
| Aug-13 | |
| Jul-31 | |
| Jul-30 | |
| Jul-23 | |
| Jul-08 | |
| May-21 | |
| May-15 | |
| May-14 | |
| May-12 |
