OptimumBank's 46% Rally Meets A Revenue Reset As Profit Durability Faces A Test
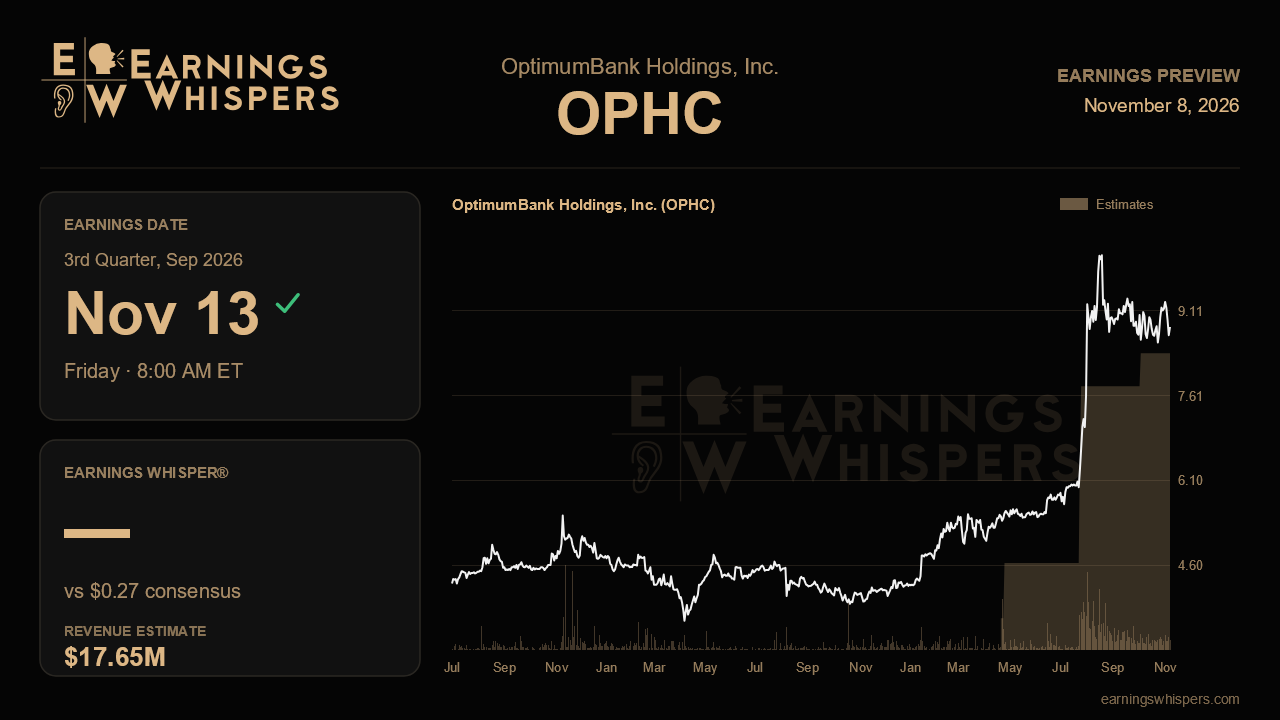
OptimumBank Holdings heads into its third-quarter report with an unusual mismatch. Its stock has jumped 46% since the last release, while the S&P 500 slipped slightly. Yet analysts expect quarterly revenue to fall well short of last quarter's level. The Street is betting that earnings can hold steady even as the top line resets lower. Whether the South Florida lender can deliver that combination is the real test of whether the rally rests on solid footing.
Consensus calls for earnings of $0.27 per share on revenue of about $17.7 million. That profit figure would be up 50% from the $0.18 earned a year ago, a strong increase for a small bank. Revenue, however, is projected to decline 3.6% from the year-ago $18.3 million. It would also drop sharply from the $24.2 million reported last quarter. The size of that sequential gap suggests analysts do not treat last quarter's top line as a sustainable run rate. Meanwhile, they expect earnings per share to come in only a penny below last quarter's $0.28. Management has not issued formal guidance, so there is no company range to measure the Street against. That leaves the consensus as the main benchmark.
The arithmetic behind those estimates is the heart of the story. Earnings that rise 50% on lower revenue imply tighter cost control, a better funding mix, lighter credit costs, or some combination of the three. For a bank focused on real estate lending in Broward, Miami-Dade and Palm Beach counties, the most telling evidence will be net interest income and the margin behind it. Steady or improving spread income would show that core lending economics are doing the heavy lifting. That would validate the earnings trajectory. Earnings that lean heavily on lower provisions or a smaller expense base would be a weaker foundation. The same goes for one-time items. Credit quality in the commercial real estate book deserves particular attention, because a concentrated lender can see results swing quickly when problem loans emerge.
The revenue line needs careful reading as well. If the report confirms that last quarter's $24.2 million included elements that have now rolled off, a lower figure near $17.7 million should not alarm anyone. That is especially true if earnings hold up. A larger shortfall, or a beat that comes only from noninterest items, would raise doubts about how much organic growth the bank is actually generating.
Sentiment has cooled noticeably even as the shares have climbed. Going into the previous report, the reading stood at 78% bullish. It now sits at 5.2% bearish, a sharp swing toward caution. That divergence is worth noting. The stock has been rewarded while enthusiasm among those tracking the name has faded, perhaps because a 46% move has already priced in a good deal of improvement. Sentiment does not predict the outcome, but it does suggest that a merely in-line quarter may not be enough to keep buyers enthusiastic.
The chart reflects both strength and some fatigue. At $8.83, the stock trades well above its 200-day moving average of $6.72. The entire post-earnings range of $6.05 to $10.68 sits above the prior quarter's narrow $5.35 to $6.10 band, a clear change in how the market values the company. Still, shares are roughly 17% below the recent high, so this is a stock consolidating gains rather than pressing toward a breakout.
Ultimately, the report needs to show that OptimumBank's earnings power is coming from recurring banking income rather than a favorable quarter. Profit near $0.27 backed by healthy net interest income and stable credit would support the rerating. A miss, or a beat built on lower provisions or one-time items, would invite the market to question how much of the 46% rally was earned.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-08 | |
| Nov-05 | |
| Aug-13 | |
| Aug-06 | |
| Jul-24 | |
| May-19 | |
| May-18 | |
| May-05 | |
| Apr-27 | |
| Apr-24 | |
| Apr-20 | |
| Apr-10 | |
| Apr-06 | |
| Mar-23 | |
| Mar-13 |
