Owlet Faces First Real Test Of Amazon's Crackdown On Uncleared Baby Monitors
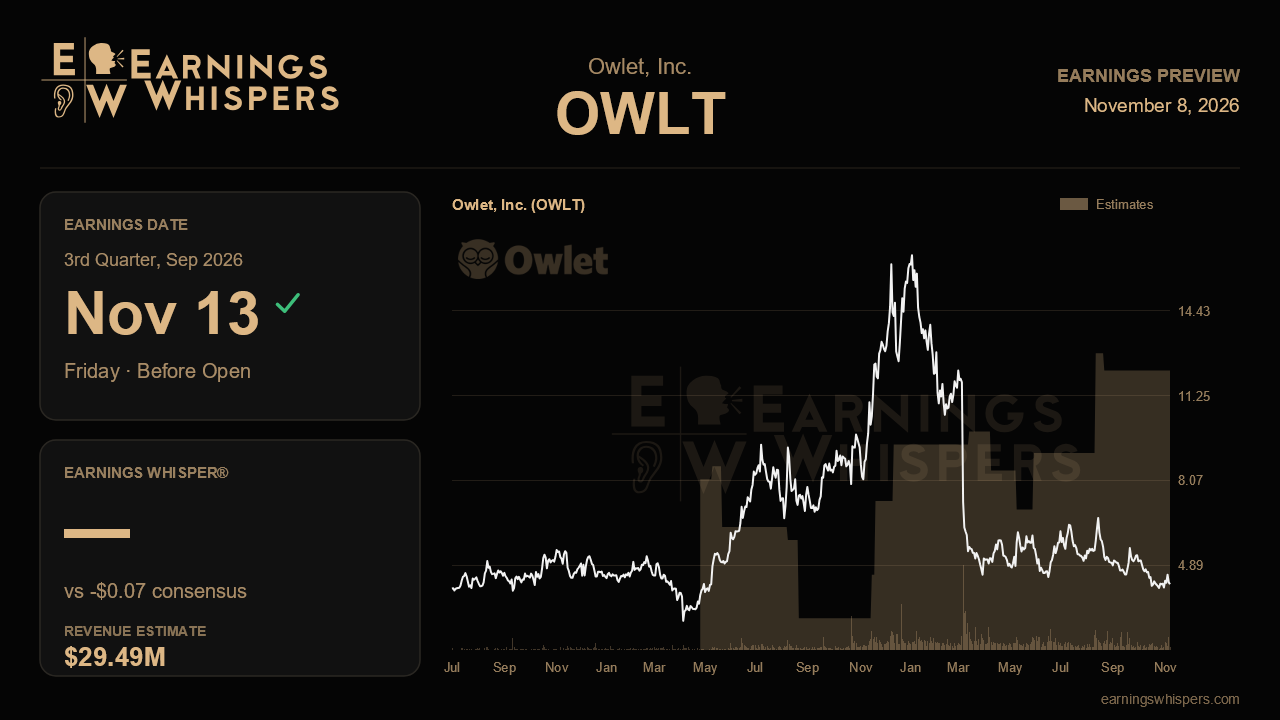
Owlet heads into its third-quarter report with a peculiar setup: management has already told the market the quarter will be weaker, yet the period also contains what could become the most important competitive development in the company's history. On August 10, Amazon began deactivating vital-sign baby monitors that lack FDA clearance, leaving Owlet as the only cleared device in that corner of the marketplace. The November 13 release, due before the opening bell, offers the first look at whether that shift is translating into share gains or whether aggressive competitor discounting and a soft consumer are swamping it.
The Street is braced for contraction. Consensus calls for revenue of $29.5 million, down 7.8% from $32.0 million a year ago and well below the record $33.9 million posted last quarter. The expected loss of 7 cents a share compares with a 4-cent loss in the year-ago period and 5 cents last quarter. None of that should shock anyone, since management explicitly guided the third quarter lower both sequentially and year over year. The more telling comparison is the full year. Owlet reaffirmed its 2026 revenue outlook of $118 million to $122 million, and consensus of roughly $118.6 million sits near the bottom of that range. With about $56.4 million booked in the first half, analysts are effectively assuming the company only barely clears its own floor. That range was already cut from $126 million to $130 million back in the first quarter, and management chose not to lift it after a strong second quarter, which tells you how little cushion it believes it has.
That makes demand commentary the swing factor. Prime Day units fell 8% last quarter after several events of sharp growth, and management described the baby-monitor category as flat to down at recent Amazon promotions. Rivals discounted heavily ahead of the deadline, pulling forward sales Owlet might otherwise have captured. A clean validation of the bullish narrative would be evidence that unit trends on Amazon improved after August 10 and that the company's share of the vital-sign category expanded meaningfully. If management instead says visibility remains murky or competitors found workarounds, the moat thesis loses some of its near-term punch.
The subscription business is the other pillar worth scrutinizing. Subscribers climbed to 130,000, DreamSock U.S. attach reached 36%, and monthly recurring revenue topped $1.1 million, all with subscription gross margins near 68%. This quarter brings the rollout of WebPay, which sidesteps roughly 30% app-store fees, along with upfront subscriptions at the point of purchase and BabyList bundles. Continued subscriber gains and any lift in subscription margin would show the recurring revenue engine compounding even when hardware sales wobble. International, which grew 214% last quarter, also needs to keep carrying weight. On costs, keep in mind that the raised gross margin and adjusted EBITDA guidance reflected only a one-time tariff refund; underlying expectations were essentially unchanged. With operating expenses at 59% of revenue and severance in the mix, signs of cost discipline would matter, as would clarity on the prior-period revisions flagged for the 10-Q.
The market has not been patient. Shares have fallen 35% since the last report, trailing the S&P 500 by about 30 percentage points, and at $4.17 the stock sits just above its post-earnings low of $4.02 and far beneath its 200-day moving average of $6.19. Sentiment is mildly bullish and virtually unchanged from last quarter, suggesting the selloff reflects fading confidence in second-half demand rather than a dramatic swing in opinion.
That depressed starting point lowers the bar somewhat, but it also means a reaffirmed range will not be enough without proof behind it. The central question is whether Owlet can show that its FDA clearance is converting into measurable Amazon share gains while subscriptions keep climbing. If it can, a weak quarter becomes a transitional one; if not, the low end of guidance starts to look like a ceiling.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 14 hours | |
| Nov-06 | |
| Oct-22 | |
| Oct-09 | |
| Oct-07 | |
| Sep-30 | |
| Aug-12 | |
| Aug-11 | |
| Aug-10 | |
| Jul-23 | |
| Jun-30 | |
| May-26 | |
| May-12 | |
| May-11 | |
| May-07 |
