Docebo Beats And Raises Again, But A Debt-Funded Special Dividend Changes The Risk Profile
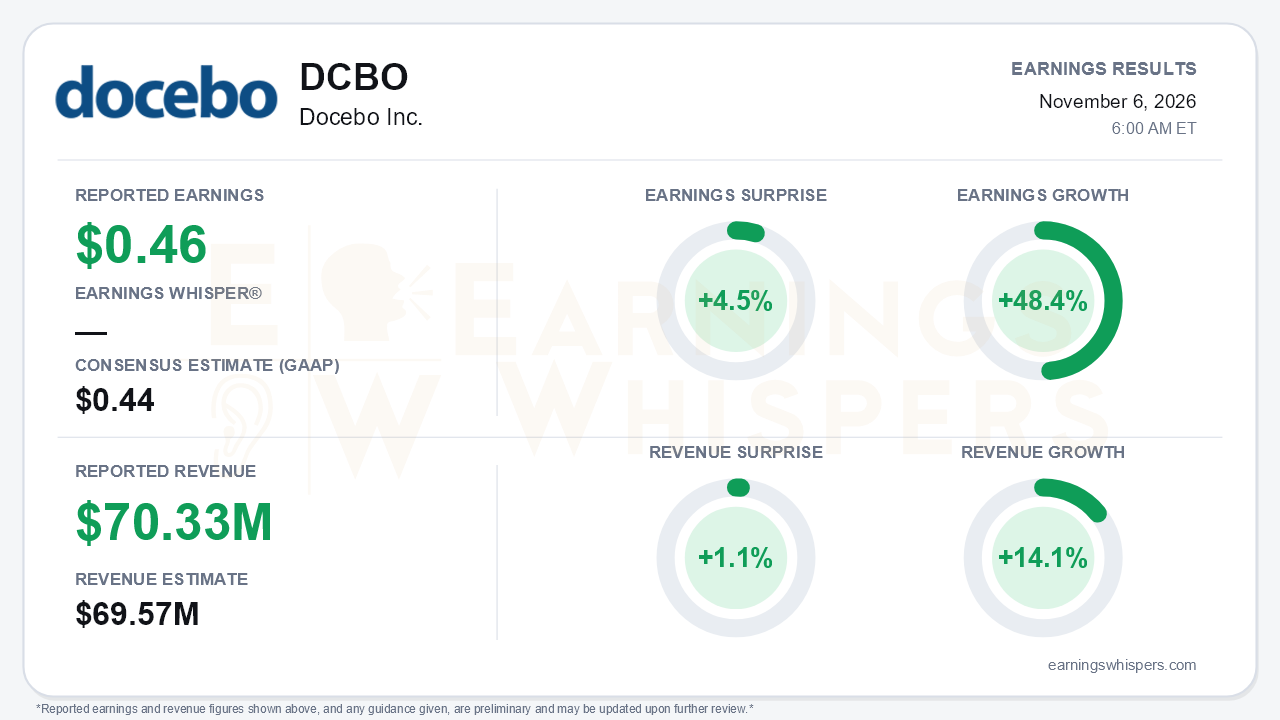
Docebo delivered another beat-and-raise quarter, and the more important development is that the rebound is becoming steadier. Subscription growth is edging higher, full-year revenue expectations have moved well above the initial plan, and management now feels confident enough to lever the balance sheet for a roughly $60 million special dividend. Earnings Whispers puts third-quarter earnings at $0.46 per share, 4.5% above the $0.44 consensus and up 48.4% from a year ago. Revenue of $70.33 million topped the $69.57 million consensus by 1.1% and grew 14.1%, slightly faster than the 13.9% pace for the first nine months. The company's own release shows IFRS earnings of $0.38 per basic share ($0.37 diluted) and adjusted earnings of $0.56 ($0.55 diluted). Investors comparing figures should note which basis is being used.
The quality of the beat deserves some scrutiny. Operating improvement was real. Operating income rose to $11.3 million from $8.0 million, and adjusted EBITDA climbed 34% to $16.7 million, lifting margin to 23.7% from 20.1% as general and administrative, sales and marketing, and R&D costs grew far slower than revenue. But several other factors flattered the per-share figures:
- **Buybacks:** Weighted basic shares fell to about 25.0 million from 28.7 million.
- **Taxes:** Tax expense dropped to $0.5 million from $2.1 million, which helped net income rise 54%.
- **Cash flow:** Operating cash flow actually fell 21.7% to $4.1 million.
- **Free cash flow margin:** Free cash flow margin slipped to 8.7% from 9.2%, although nine-month free cash flow is up 41%.
- **Gross margin:** Gross margin eased to 79.3% from 80.3%.
The underlying recurring-revenue story is healthier than the headline ARR suggests. Reported ARR grew 11.0% to $261.5 million. However, the company's largest OEM customer, which management has been deliberately working off, has shrunk to 2.1% of ARR from 6.2%. Excluding that customer and acquired ARR, and adjusting for currency, ARR grew about 13.4%. Average contract value jumped 24% to $77.9K, consistent with the enterprise wins cited in the release:
- A semiconductor-equipment leader
- Honda Motor Europe
- Snowflake
- A diabetes-focused MedTech company consolidating eight learning systems
On the call, management traced a clean progression. Subscription growth ran 12% in Q1, 12% in Q2 and 12.4% in Q3, with 12.8% implied for Q4. Full-year revenue growth now sits near 14% versus the 10.6% midpoint guided in February. The fall product roadmap also arrived on schedule:
- Agent Hub/Enterprise Knowledge launched with about 600 public beta customers.
- The first Creator agent shipped.
- The forward-deployed engineering team is staffed.
- 365Talents cross-sell is tracking ahead of budget.
Management framed these as a route into CIO budgets and higher ARPU in 2027, and it signaled further margin expansion next year.
Bears still have legitimate ammunition:
- **Federal slippage:** Large federal deals expected in Q3 slipped into Q4 on procurement complexity. Earlier calls had framed Q3 as the first real FedRAMP peak quarter, so government remains mostly pipeline.
- **Services mix:** Professional services revenue jumped 42%, and that mix is pressuring gross margin. Management expects the pressure to persist into Q4, even though subscription gross margin was unchanged.
- **Q4 guidance:** The Q4 outlook calls for revenue of $71.9-$72.1 million and adjusted EBITDA of $16.9-$17.1 million. That implies roughly flat EBITDA margin versus Q3 as healthcare and forward-deployed engineering investments ramp. Management described the guide as conservative, with little incremental Q4 bookings assumed and an October FX headwind to ARR.
- **Leverage:** The special dividend lifts debt from about $90 million to roughly $150 million, or about 1.9 times projected adjusted EBITDA of roughly $56 million. That is under management's sub-3x comfort line, but cash has already fallen to $42.5 million from $74.0 million at year-end, working capital stands at negative $34.2 million, and the substantial issuer bid filled only $2.5 million of up to $70 million.
The market had already moved ahead of the report. Shares have climbed 42.6% since the open after the August release to $28.97, about 40% above the 200-day moving average of $20.70. Earnings Whispers investor sentiment swung decisively, from -0.42 before the prior report to +0.13. That swing reflects a meaningful shift from skepticism to modest optimism rather than outright enthusiasm. Price and AVWAP trend readings are positive, consistent with sustained buying. The setup is now more demanding. The turnaround skeptics who dominated in August have largely been run over, and the stock no longer enjoys a low-expectations cushion.
The bottom line is that Docebo's fundamentals are improving in a measured, credible way: subscription growth is inching higher, adjusted margins are expanding, and the product roadmap is landing on time. However, part of the per-share gain comes from a shrinking share count and lower taxes. The deferred federal revenue and services-driven margin drag remain unresolved. With the stock up sharply and leverage rising to fund shareholder returns, execution on Q4 government deals and the 2027 margin story now carries more weight than it did a quarter ago.
Read our earnings preview for Docebo Inc.: https://www.earningswhispers.com/article/DCBO/22478
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-08 | |
| Nov-06 | |
| Nov-06 | |
| Nov-02 | |
| Oct-29 | |
| Oct-28 | |
| Oct-16 | |
| Sep-09 | |
| Aug-21 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Aug-03 | |
| Jul-17 | |
| Jul-06 |
