Flexible Solutions Needs An 83% Sequential Revenue Rebound To Back Its Rally
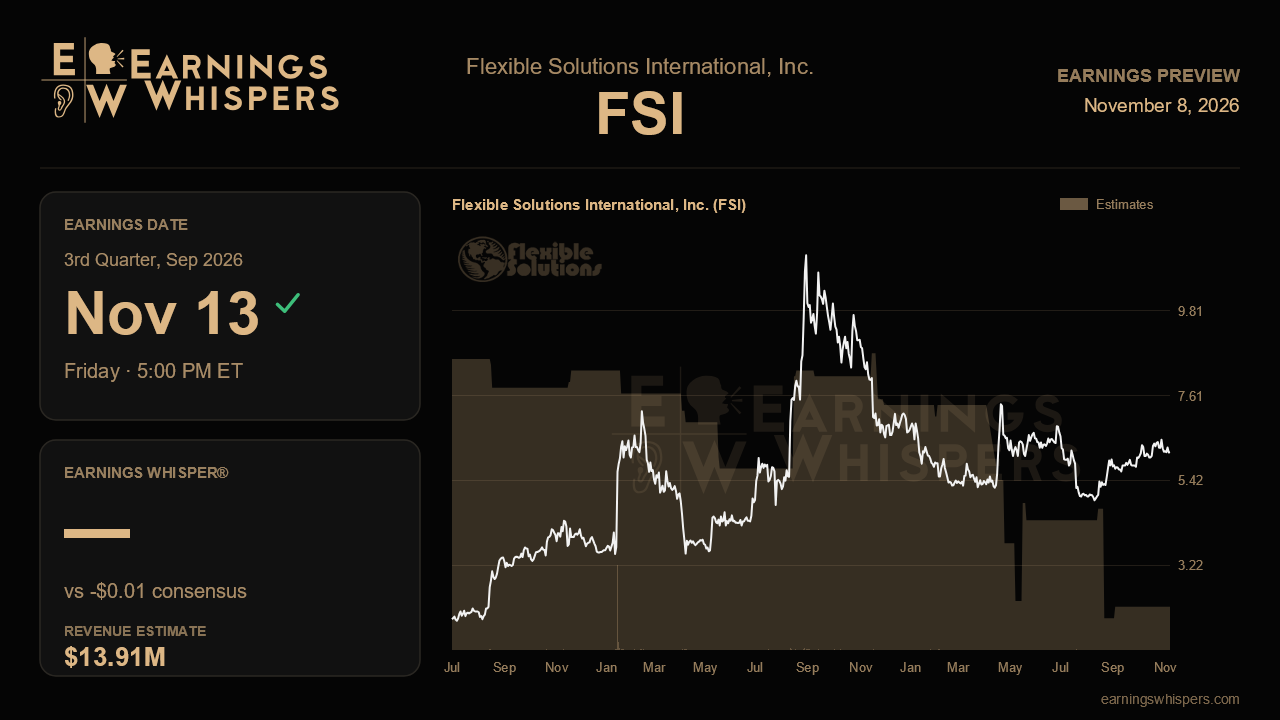
Flexible Solutions International heads into its September-quarter report with an unusual setup. The stock has climbed sharply since its last release, even though that release showed revenue sliding to $7.6 million and a loss of 15 cents a share. Wall Street is effectively betting that the last quarter was a trough rather than a trend. The report due after the close on November 13 will show whether that bet was early or simply right.
The consensus calls for revenue of roughly $13.9 million and a loss of about a penny a share. Against the year-ago quarter, that would be strong growth: revenue up nearly 32% from $10.6 million, and the loss narrowing by about 75% from 4 cents. The more demanding comparison is sequential. Getting from $7.6 million to $13.9 million means revenue would have to rise by more than 80% in a single quarter. For a small specialty chemical maker, that is a steep ramp. The company sells thermal polyaspartate biopolymers into agriculture, oil fields, detergents and personal care, alongside its water and energy conservation products. Analysts appear to assume that demand from those end markets returned in force, not gradually.
Management has not issued formal guidance, so there is no company range to measure the Street against. That leaves the consensus as the main yardstick and makes the quality of the beat or miss more revealing. A top line near $14 million with a near-breakeven result would suggest the prior quarter's weakness was mostly about timing, whether from order patterns, customer destocking or shipments shifting between periods. A revenue figure stuck closer to $10 million would point to something more durable and would make the year-ago comparison look less like a recovery and more like a stall.
Margins are the second test. The jump from a 15-cent loss to roughly breakeven depends on operating leverage. The company's fixed manufacturing and overhead costs would have to be spread over a much larger revenue base. If revenue arrives but the loss stays wide, that would raise questions about pricing, input costs or product mix. A swing to a small profit on in-line sales would be the clearest sign that the cost structure can absorb volatility in volumes. With no detailed commentary to anchor expectations, any explanation management gives for the sequential swing will be as important as the headline numbers.
The market's mood is mixed. Shares are up about 27% since the last report, while the S&P 500 fell about 5% over the same stretch, an outperformance of roughly 32 percentage points. Yet sentiment has turned more bearish, moving to about 22.8% bearish from 4.1% bearish heading into the prior report. Price and sentiment are pulling in opposite directions. Buyers have pushed the stock higher, but a growing share of observers doubt the recovery story, so a clean beat could find skeptics to win over. At $6.15, the stock sits above its 200-day moving average of $5.87 and in the upper part of its post-earnings range of $4.85 to $6.55. It is not pressing that ceiling, and it remains below the prior quarter's high of $6.93, so there is room for a move in either direction once numbers hit.
The central question is whether the September quarter proves that the June quarter's slump was a temporary air pocket. Revenue near the $13.9 million consensus, with losses that narrow toward zero, would validate both the rally and the recovery narrative. A shortfall on the top line would undercut the reasoning behind the stock's recent strength, especially if it came with a loss that stays stubborn.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-08 | |
| Oct-19 | |
| Aug-31 | |
| Aug-14 | |
| Jul-20 | |
| Jul-03 | |
| May-15 | |
| Apr-21 | |
| Apr-15 | |
| Mar-31 | |
| Feb-25 | |
| Feb-10 | |
| Feb-09 | |
| Jan-26 | |
| Jan-23 |
