Aramark Must Prove Record Wins And Nexus Ramp Can Lift Profits, Not Just Revenue
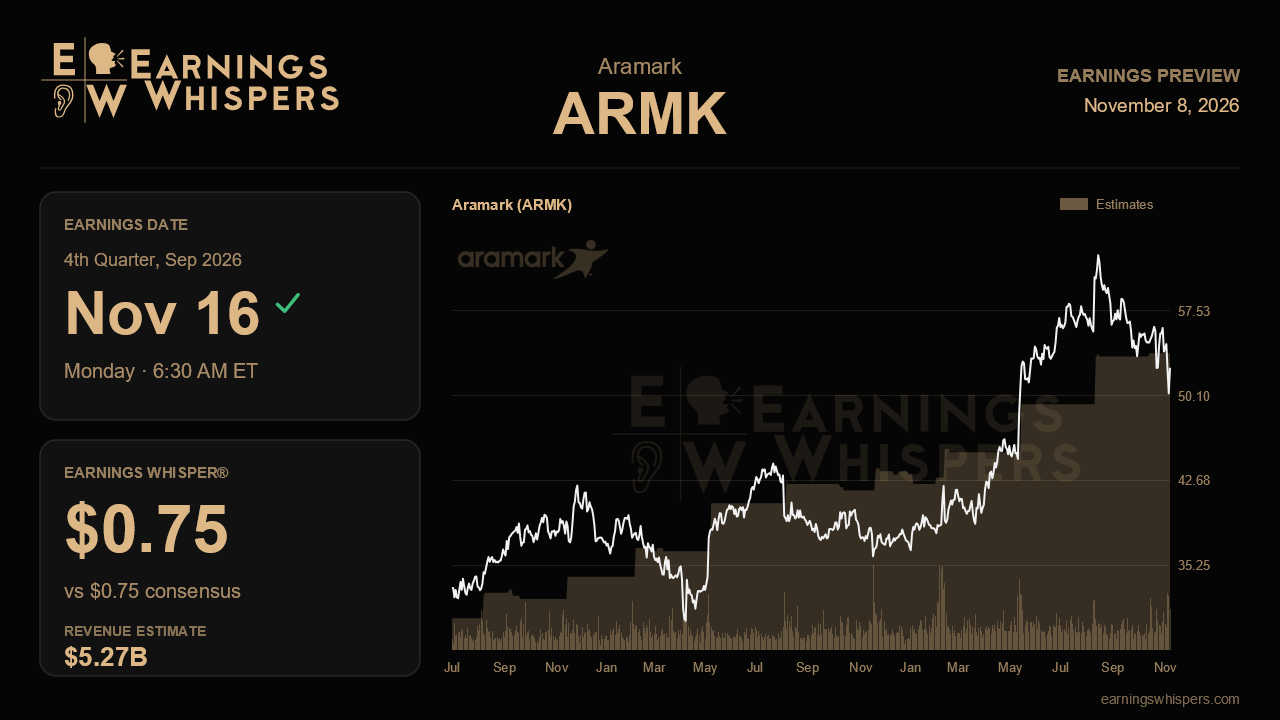
Aramark heads into its fiscal fourth-quarter report with an odd disconnect. Three months ago management delivered its most confident message in a year, lifting its organic revenue outlook, touting record new business and announcing that its Nexus AI data center platform had started generating real revenue. The stock has since fallen 12.4%, trailing the S&P 500 by more than seven percentage points. This report, due before the open on November 16, is the first chance to show whether the top-line acceleration is translating into the earnings power the market seems to doubt.
The Street is looking for $0.75 per share, up about 17% from $0.64 a year ago, on revenue of roughly $5.27 billion, a gain of about 4.4%. The Earnings Whisper sits right on consensus, so there is no hidden bar above the published estimate. The more interesting comparison is with guidance. Management kept its fiscal 2026 EPS range at $2.27 to $2.36 while raising its revenue range to $20.17 billion to $20.36 billion. Full-year consensus of $2.24 on $19.97 billion sits below the low end of both ranges, which suggests analysts either have not fully caught up with the raised revenue outlook or are discounting management's profit targets. Either way, a fourth quarter that lands Aramark comfortably inside its own guidance would look like upside relative to the Street's annual math.
The revenue piece deserves scrutiny. Management raised its organic growth target to 9% to 10% for the year and said its underlying run rate was closer to 10% to 11%, noting that a calendar shift trimmed roughly two points from third-quarter growth. Consensus implies reported growth well below that pace, so the release needs to reconcile the two. Organic growth near or above 10%, helped by any reversal of that timing drag, would validate the acceleration story. A print that drifts back toward the high single digits would raise questions about whether the guidance lift was more about timing than demand.
Nexus is the newest and most closely scrutinized catalyst. The first Texas hyperscaler site began contributing late in the third quarter, its scope expanded about 40% to roughly $140 million a year, and management expected it to account for about 1% of fourth-quarter revenue. A second site worth around $160 million annually is mobilizing, and eight sites are now assigned. Investors should look for confirmation that the first site hit its ramp, an update on the second site's timing and any commentary on Texas' data center moratorium and audit, which management says is the hyperscaler's risk rather than Aramark's. Because ramp speed depends on the client's hiring pace, any slippage would hit the fiscal 2027 narrative harder than this quarter's numbers.
Margins are the real swing factor. Unlike revenue, adjusted operating income growth of 12% to 17% and EPS growth of 20% to 25% were only reaffirmed, held back by startup costs from an unusually heavy slate of openings in higher education, healthcare with RWJBarnabas, Stone Mountain and Nexus itself. Third-quarter operating income rose 13%, or about 21% excluding the calendar shift. If mobilization costs proved heavier than planned, the fourth quarter is where it would show. Record retention near 98% and $1.6 billion in year-to-date wins provide plenty of revenue visibility; the open question is how quickly that business becomes profitable.
Sentiment has warmed sharply, with the bullish reading roughly doubling from the prior quarter, even as the shares slid toward the bottom of their post-earnings range near $50 and now sit just above the 200-day moving average. That combination of improving fundamentals, cheaper shares and a modest consensus bar is constructive, but it hinges on one issue. Aramark has convinced investors it can grow faster; this report needs to show that the cost of onboarding record new business is peaking, and that fiscal 2027 guidance captures the margin payoff from that growth.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-08 | |
| Nov-05 | |
| Oct-19 | |
| Sep-30 | |
| Sep-29 | |
| Sep-23 | |
| Sep-21 | |
| Sep-14 | |
| Sep-09 | |
| Sep-02 | |
| Sep-01 | |
| Aug-24 | |
| Aug-20 | |
| Aug-20 | |
| Aug-17 |
