IQIYI's AI Pivot Faces Its Breakeven Test As Revenue Keeps Sliding
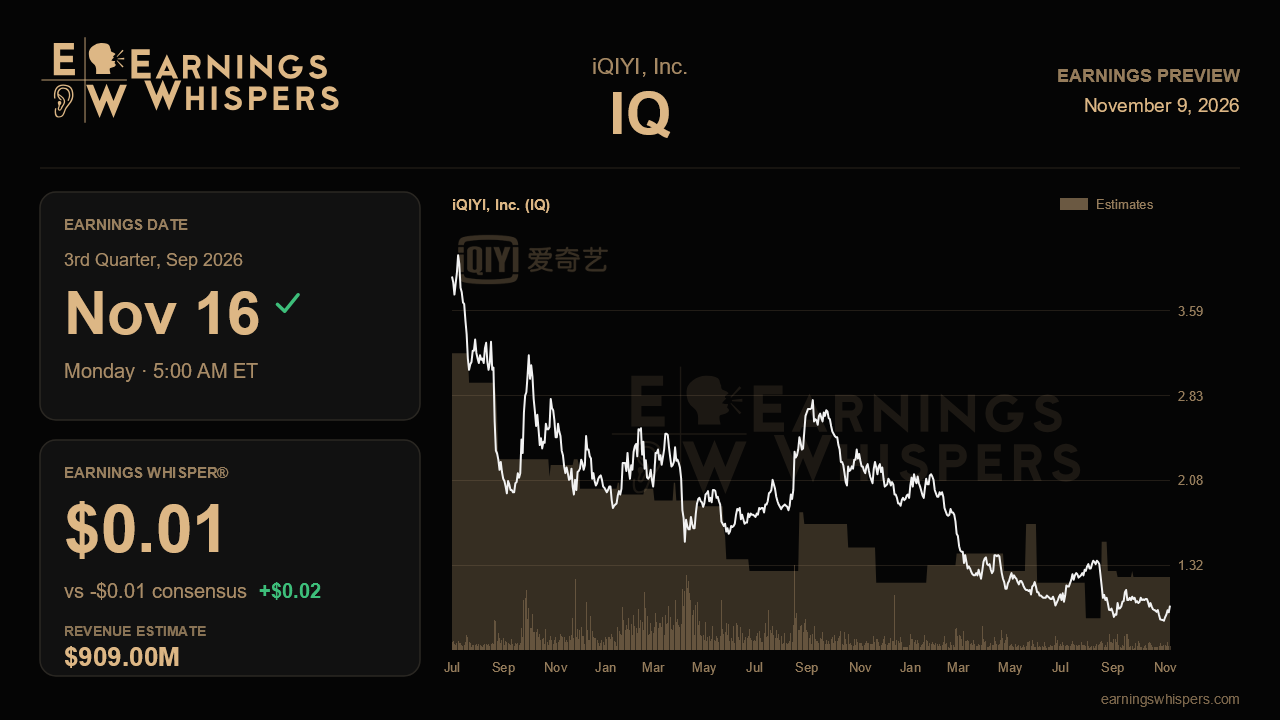
iQIYI heads into its September-quarter report with a story that has improved on paper and deteriorated on the tape. Last quarter, management showed a company shrinking its losses toward breakeven while betting everything on artificial intelligence and a creator-driven ecosystem. Since then the stock has fallen about 24%, trailing the S&P 500 by roughly 20 percentage points. The report due before the open on November 16 has to show that the narrowing losses are a trend and not a one-quarter event, at a time when the core business is still not growing.
The Street expects a GAAP loss of about a penny per share, compared with a four-cent loss a year ago. That works out to the 75% improvement implied by consensus. Revenue is forecast at $909 million, down 2.6% from $933.7 million last year and below the prior quarter's $923.8 million. The Earnings Whisper sits at a one-cent profit, slightly above consensus. The gap is only two cents, but it carries meaning: some investors think iQIYI could reach GAAP breakeven or better. The company gives no formal guidance, so the bar is set entirely by that progression in the loss line.
The progression is credible because of what happened in the June quarter. The non-GAAP operating loss narrowed about 80% sequentially to RMB30.3 million, operating cash flow nearly doubled to RMB339.6 million, and content distribution revenue jumped 90%. Two kinds of evidence would show that this momentum is structural rather than a timing benefit:
- **Cost discipline.** Operating income should move into positive territory without another outsized distribution windfall.
- **AI efficiencies reaching margins.** The AI-driven savings management described should show up in content costs.
If the improvement leaned heavily on lumpy licensing deals, a reversal in distribution revenue could quickly wipe out the gains.
The top line is where the story is most exposed. Membership revenue fell 4% sequentially last quarter, which management attributed to seasonality, and total revenue has been stuck near RMB6.2 to 6.3 billion. The September quarter typically benefits from summer viewing, so a sequential rebound in membership is the minimum requirement. A second straight decline would undercut the seasonal explanation. Advertising has been flat, and the new brand advertising leadership has yet to show results.
The growth engines management highlighted should carry more weight this time:
- **Overseas membership.** It has grown roughly 40% year over year for several consecutive quarters. Any slowdown would remove the company's cleanest growth story.
- **Short-form drama.** iQIYI's share doubled to 50% by June, making it number one in China. Holding that position would show the gain was durable.
- **AIGC monetization.** Investors should look for specifics on the revenue-sharing AIGC dramas and the licensed AI feature film. Concrete figures, rather than more launch announcements, would show the strategy is generating revenue.
Cash is the quieter risk. Balances fell from RMB4.9 billion to RMB4.1 billion over four quarters, driven by note repurchases and buybacks. Another drop, especially alongside a sub-$1 share price, would sharpen questions about how much financial flexibility remains to fund the transformation.
Sentiment has swung from bearish ahead of the last report to modestly bullish now, even as the stock slid. That divergence suggests some investors see value in the selloff. The chart is less encouraging. At $0.96, shares sit well below the 200-day moving average of $1.23, in the lower part of a post-earnings range spanning $0.82 to $1.31. They are also right at the floor of the prior quarter's range, so the stock is not pricing in much good news.
The central question is whether iQIYI can keep shrinking losses while revenue declines. A quarter that delivers breakeven-level profitability, a seasonal membership rebound and steady overseas growth would validate the AI pivot. A wider loss or another soft membership print would suggest the earlier progress was more about timing than transformation.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| Nov-06 | |
| Oct-10 | |
| Oct-01 | |
| Sep-25 | |
| Aug-18 | |
| Aug-18 | |
| Jun-17 | |
| May-27 | |
| May-19 | |
| Apr-29 | |
| Apr-24 | |
| Apr-20 | |
| Apr-20 | |
| Mar-01 |
