Perion Must Prove Its Margin Rebound After Buying Growth With Price Cuts
Perion Network heads into its third-quarter report with an awkward contradiction to resolve. Last quarter the company showed the best adoption numbers it has posted in some time, with Perion One spend climbing 15% and digital out-of-home and CTV growing far faster. Yet it paid for that growth with promotional take-rate concessions that pushed contribution ex-traffic acquisition costs down 11% and squeezed adjusted EBITDA to just $2.8 million. Management's answer was that two large strategic accounts would begin contributing in late Q3, and that end-of-quarter restructuring would lift margins in the back half. This report is the first real test of both promises.
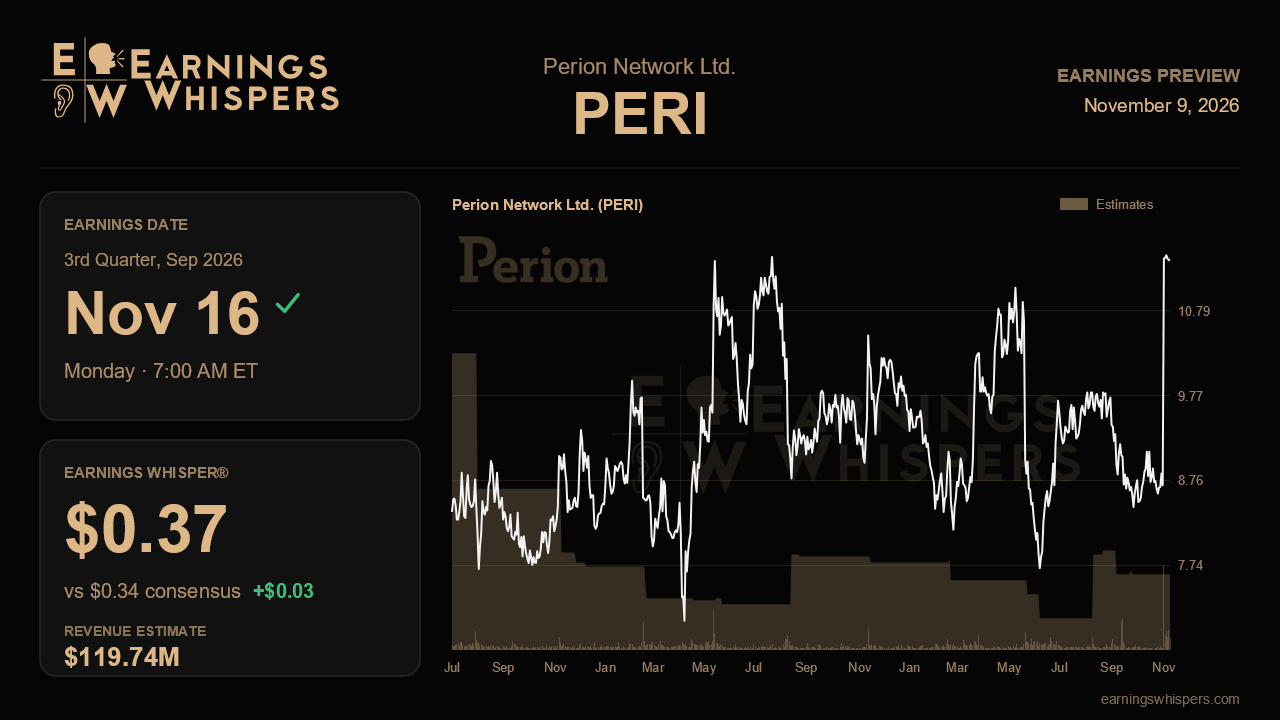
The Street is betting heavily on that rebound. Consensus calls for non-GAAP earnings of $0.34 a share on revenue of $119.7 million, up 8.4% from a year ago. That would be a sharp turn from last quarter's $0.03 loss on $98.2 million in revenue, and well above the $0.04 earned in the year-ago period. The Earnings Whisper of $0.37 sits modestly above consensus, so the bar is set a little higher than the published numbers suggest. Investors are expecting more than stabilization. They are looking for a clear inflection.
Guidance frames how much room there is. Perion narrowed its 2026 revenue outlook to $460 million to $475 million, trimming the top from $490 million, and full-year consensus of about $464 million sits near the low end of that range. That leaves analysts positioned cautiously on revenue, which makes the quarter less about the top line and more about what Perion keeps from it. The company also lowered the midpoint of its contribution ex-TAC outlook, blaming slower onboarding of those two strategic accounts, while holding its adjusted EBITDA range of $50 million to $54 million. Given how weak the second quarter was, holding that EBITDA midpoint implies a steep second-half acceleration, and Q3 has to carry a meaningful share of it.
What would validate the story? First, evidence that the strategic agreements actually started producing material revenue before quarter end rather than slipping into Q4. Second, a return to positive growth in Perion One contribution ex-TAC, which would show that spend growth is finally outrunning the take-rate giveaways. Management guided only to modest take-rate improvement, so even a small recovery would be meaningful. Third, visible cost savings from the restructuring showing up in the EBITDA margin, which collapsed to 7% of contribution ex-TAC last quarter from 37% in Q4. Commentary on Best Buy Canada, the DV360 out-of-home integration and the AskPerion agentic tool would add color, but these remain early and are unlikely to move the numbers yet. Conversely, another quarter of rising spend paired with shrinking contribution, or further trimming of the ex-TAC or EBITDA outlook, would suggest the monetization gap is structural rather than temporary. Persistent declines in search and open web would add pressure as well.
The market's reaction has been more generous than sentiment. Shares have climbed 24.3% since the last report while the S&P 500 fell 4.8%, and at $11.39 the stock sits well above its 200-day average of $9.30 and right at its post-earnings high of $11.46, effectively testing a breakout. Yet sentiment has swung from mildly bullish to mildly bearish, a sign that plenty of investors remain skeptical even as the price runs. That combination leaves little cushion: a rally into the print raises the stakes if the rebound looks thin.
Ultimately, this report hinges on one question. Can Perion show that the growth it bought last quarter is turning into profit? If the strategic accounts are ramping and margins are recovering, the price concessions will look like a smart investment. If not, the reiterated EBITDA target will start to look like the next number at risk.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-02 | |
| Nov-01 | |
| Sep-11 | |
| Aug-31 |
Dayton-based Stratacache sells in-store media division to Israeli company
PERI
Dayton Daily News, Ohio
|
| Aug-10 | |
| Aug-10 | |
| Jul-08 | |
| Jun-18 | |
| Jun-16 | |
| Jun-03 | |
| May-20 | |
| May-20 | |
| May-20 | |
| May-20 |
