Infleqtion Lifts Outlook Again, But A Sliding Stock Demands Proof On 2027 And Cash Burn
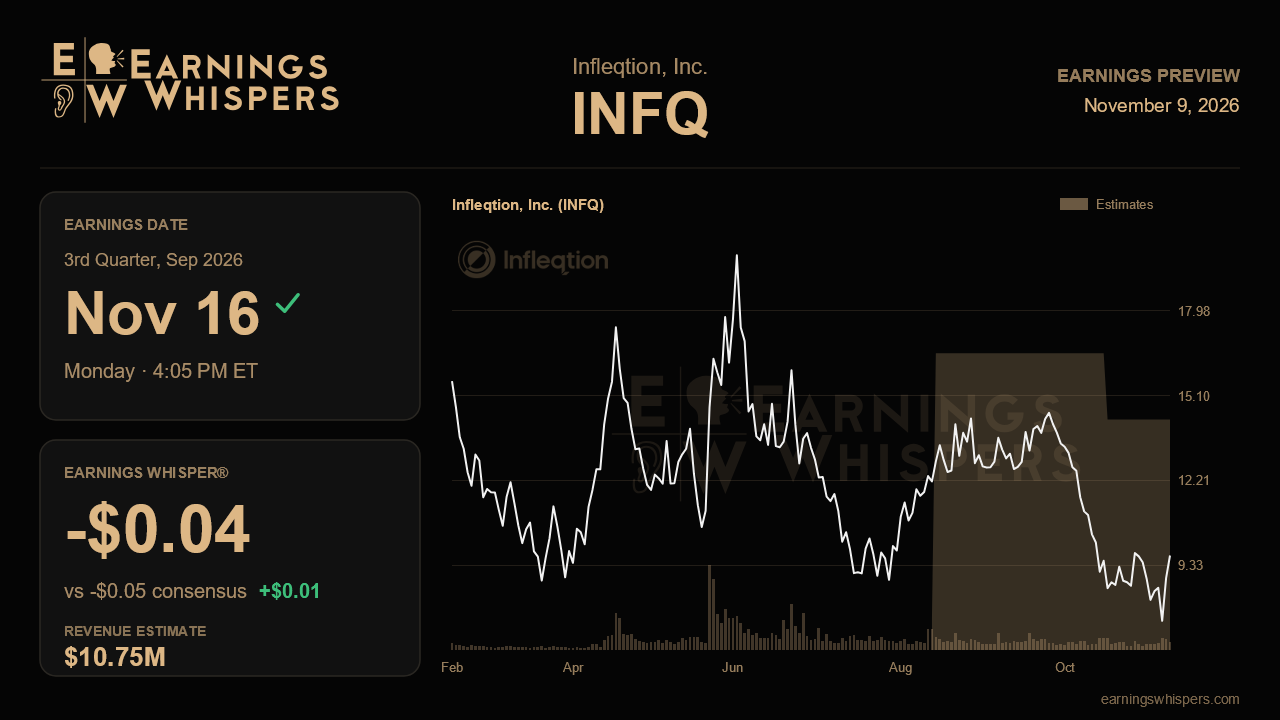
Infleqtion heads into its third-quarter report with an unusual mismatch. Management has now raised its 2026 revenue outlook three times, most recently to about $45.1 million from $43.0 million, yet the stock has fallen roughly 26% since the last report, trailing the S&P 500 by about 20 percentage points. The business narrative has moved from momentum to acceleration, while the market has moved the other way. This report, due after the close on November 16, needs to show which side is reading the situation correctly.
The quarterly bar looks modest on the surface. Analysts expect revenue of about $10.8 million, which would be a step down from the record $12.6 million posted last quarter, and a loss of $0.05 per share versus $0.06 in the second quarter. The Earnings Whisper sits at a loss of $0.04, a penny better than consensus, which hints at slightly higher hopes on the bottom line but is too small a gap to signal much. The more telling comparison is annual. Consensus for 2026 revenue sits at $42.6 million, below even the guidance management issued before its latest raise and well under the new $45.1 million target. With first-half revenue at roughly $22.1 million, the company's outlook implies about $23 million in the back half. If the third quarter lands near $10.8 million, the fourth quarter would need roughly $12 million, a level the company has already shown it can reach. The Street, in other words, is effectively betting that management is overreaching, so a third-quarter print comfortably above consensus would go a long way toward closing that credibility gap.
The quality of the revenue matters as much as the total. Last quarter, management said the raise reflected broad bookings visibility rather than a single program like NASA's quantum gravity gradiometer work, and noted that computing demand was running hotter than expected. Evidence of that breadth, including contribution from new commercial customer Eaton, growth in remaining performance obligations beyond the $21 million reported last quarter, and the promised normalization of a geographic mix that was 92% domestic, would validate the story. Revenue that leans heavily on one or two government awards would undercut it.
The call also set up two specific deliverables for this report. Management promised more color on 2027 revenue visibility, and the up to $100 million Commerce Department letter of intent was expected to progress toward a definitive agreement later in 2026, with its accounting treatment still unsettled. A signed agreement, or at least a clear timeline and confirmation that the funding would offset operating expense, would convert a headline catalyst into something investors can model. Further slippage would feed the skepticism already visible in the shares.
Costs are the other pressure point. The non-GAAP operating loss widened to $17 million last quarter as headcount rose about 25% this year, and management has guided to another measured increase in cash burn into 2027. Investors should also expect third-quarter cash flow to look ugly, since the roughly $27 million payroll-tax benefit that flattered second-quarter operating cash flow is due to be remitted. That outflow is known and should not be mistaken for a deterioration in underlying burn, which ran near $14 million. With about $582 million in cash and no debt, the balance sheet is not the issue; the trajectory of spending relative to revenue is.
Sentiment has soured sharply, with roughly 74% of readings now bearish versus about 23% heading into the last report. The stock, at $8.89, sits well below its 200-day moving average of $12.19 and in the lower part of its post-earnings range of $7.01 to $15.06. That leaves room for relief if the numbers cooperate, but the central question is simple: can Infleqtion show that its repeated guidance raises rest on diversified, bookable demand and credible 2027 visibility, rather than on optimism that the market has already stopped paying for?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Oct-30 | |
| Oct-30 | |
| Oct-29 | |
| Oct-19 | |
| Oct-15 | |
| Oct-15 |
Quantinuum Upgraded On Valuation Vs. Other Quantum Computing Stocks, Tech Road Map
INFQ
Investor's Business Daily
|
| Oct-15 | |
| Oct-13 | |
| Oct-06 | |
| Oct-06 | |
| Sep-29 | |
| Sep-24 | |
| Sep-24 |
