Sohu Swings To A Loss As Its Ad Rebound Stalls; Games Steady At A Lower Level
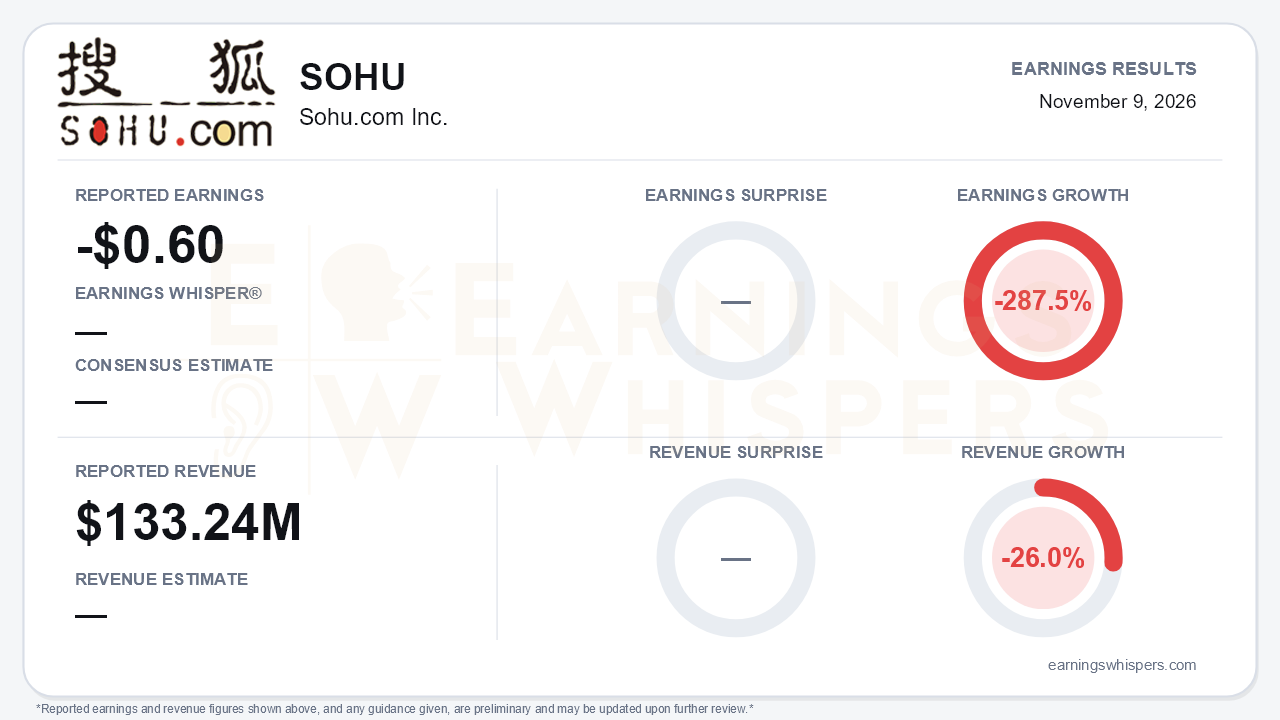
Sohu.com's third quarter delivered one encouraging data point and a broader list of reasons for caution. The company reported a GAAP loss of $0.60 per ADS on revenue of $133.24 million. Earnings fell 287.5% year over year, and revenue declined 26.0%. That compares with net income of $9 million a year earlier and a marginal $0.2 million profit in the second quarter. No consensus figure was available to measure a surprise. The more useful comparison is against management's own framing: marketing services hit the high end of guidance, while online games and the bottom line were only described as "in line." In the first and second quarters, every line beat. The central tension is that last quarter's tentative advertising recovery has already reversed in the outlook, while the game business has stabilized at a much lower base.
The quality of the sequential swing deserves scrutiny, because it is less dramatic than the headline implies:
- **Operating loss was flat.** The loss was essentially unchanged at $18.3 million in both the second and third quarters.
- **Tax and other income drove the swing.** The second-quarter profit was propped up by a roughly $13 million reversal of uncertain tax positions. This quarter carried $4.5 million of tax expense against a pretax loss, and other income fell to $3.1 million from $7.2 million.
- **The year-over-year damage is real.** Online game revenue fell to $114 million from $162 million against a tough comparison that included last year's TLBB: Return launch. Changyou's non-GAAP operating profit dropped to $59 million from $88 million, and the social media segment's operating loss widened to $74 million from $71 million.
- **Advertising growth is not profitable growth.** Marketing services revenue rose 10% year over year to $15 million, but cost of marketing services jumped 23%. The line was roughly break-even at the gross level.
The conference call largely confirmed that the advertising improvement was transitory. On the prior call, management guided third-quarter ads up 3% to 10% year over year, the first growth in a long time. The fourth-quarter guide of $13 million to $14 million now implies an 18% to 24% annual decline. Management attributed this to project spending pulled into the third quarter and a soft Double 11 shopping season, and described the fourth quarter as broadly weak. It offered little visibility into 2027 beyond hopes for growth in social network users.
The ad mix is also shifting in ways that cut both ways:
- Auto rose to 42% of advertising from 33% in the second quarter, reflecting demand for Sohu's integrated KOL, offline and live-streaming packages.
- That same shift increases concentration risk.
- FMCG (17% versus 20%) and IT (12% versus 17%) both shrank as shares of advertising.
Games are the steadier story. The fourth-quarter guide of $111 million to $121 million implies a range from an 8% decline to 1% growth year over year, and from a 3% decline to 6% growth sequentially. That is a meaningfully calmer setup than the 29% to 35% decline embedded in the prior quarter's outlook. Some caution is warranted, though:
- **Currency helps.** The guide assumes RMB6.73 to the dollar versus 6.78 in the third quarter, a modest tailwind.
- **Mobile engagement keeps eroding.** Mobile MAU fell 16% sequentially, while PC metrics held flat to slightly up.
- **A new competitive threat.** Management flagged AI short dramas as a long-term competitor for both casual and hardcore players' time.
- **The pipeline offers some hope.** The TLBB card-based RPG remains slated for late 2026 or early 2027 and is the most tangible product catalyst.
Loss guidance points to another difficult quarter. The fourth-quarter net loss outlook is $17 million to $27 million. The call analysis records a third-quarter guide of $23 million to $30 million, which would put the actual $15 million loss ahead of that range and the new outlook slightly better. Yet management characterized the bottom line only as in line, and the fourth-quarter range remains well above the $10 million to $20 million and $15 million to $25 million ranges guided earlier in the year. Either way, the direction since the start of the year has been toward deeper losses.
Capital return has been the main support for shareholders, and it is nearly exhausted. Sohu has repurchased 10.1 million ADSs for about $134 million under its $150 million authorization. Diluted share count fell to 24.8 million from 27.5 million a year ago. Management indicated no new program is planned. The balance sheet remains a substantial cushion: cash, short-term investments and long-term time deposits total roughly $1.2 billion against a sub-$340 million equity value at August's $13.66 post-report opening price. Still, that cash is not being deployed in a way that changes operating momentum.
Market context is limited this quarter. Shares opened at $13.66 after the August report, below the current 200-day moving average of $14.34. Current sentiment and price readings were not available to show how investors have positioned into this release.
The bottom line is that Sohu's quarter removed the one fresh bullish argument it had: an advertising turnaround. The game business looks to be finding a floor and the cash pile limits downside risk at the balance-sheet level. However, a wider loss outlook, a reversal back to double-digit ad declines, a winding-down buyback, and a new competitive threat in AI short dramas leave bears with legitimate ammunition until the next TLBB title arrives.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Oct-30 | |
| Aug-10 | |
| Aug-10 | |
| Jul-31 | |
| May-18 | |
| May-18 | |
| May-18 | |
| May-18 | |
| May-08 | |
| Mar-12 | |
| Feb-09 | |
| Feb-09 |
