Ispire Misses Badly On Credit Losses As Sequential Repair Runs Into A Thinning Cash Cushion
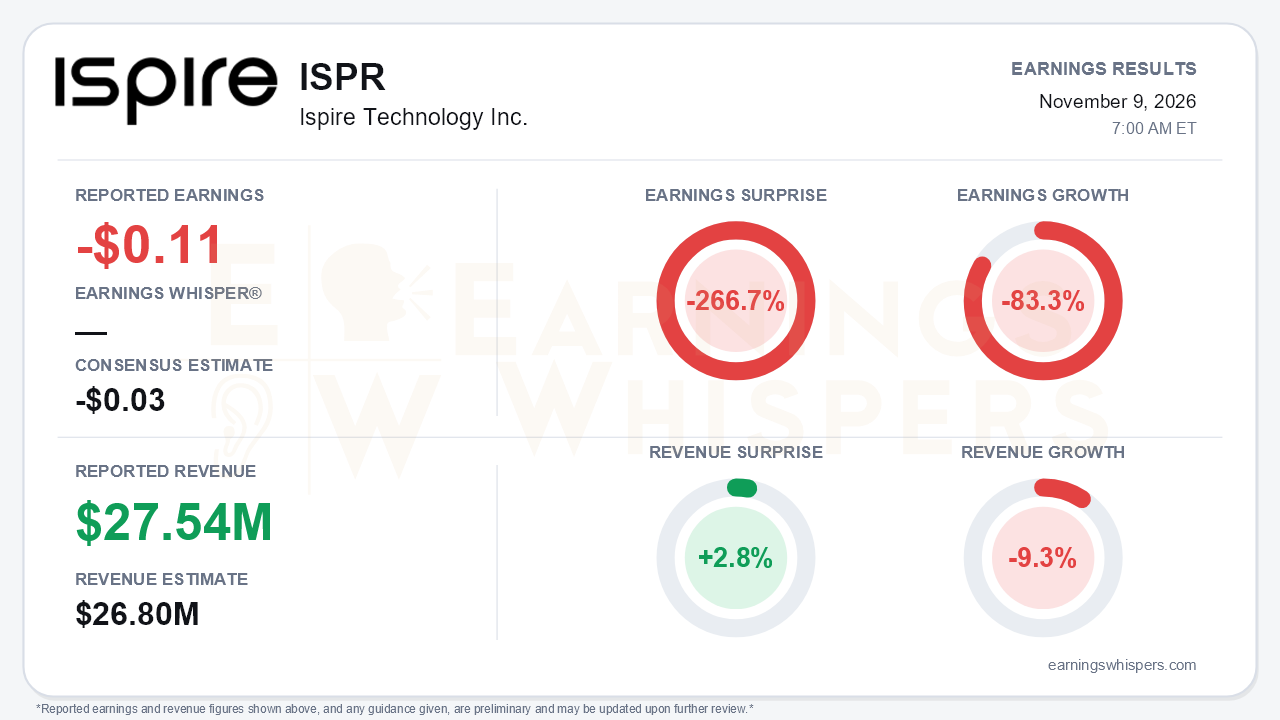
Ispire Technology (NASDAQ: ISPR) reported a fiscal first-quarter loss of $0.11 per share, far worse than the consensus estimate of a $0.03 loss. That is a 266.7% miss, and earnings fell 83.3% from the year-ago loss of $0.06 per share. Revenue of $27.54 million beat the $26.8 million consensus by 2.8% but declined 9.3% year over year. The quarter has two readings. Measured against a damaged fourth quarter, Ispire is clearly repairing itself. Measured against a year ago, it is smaller, less profitable and holding less cash. That gap is the central tension, and the report did more to show stabilization than to show a recovery.
The EPS miss comes almost entirely from one line. Credit loss expense was $4.8 million, up from $1.8 million a year earlier, and it accounted for most of the $6.4 million GAAP net loss. Excluding that charge, operating expenses were essentially flat sequentially at $5.9 million. Adjusted EBITDA, which excludes credit losses, inventory impairment and stock compensation, turned positive at $136,000. That was a $2.4 million swing from the fourth quarter's $2.3 million loss, though it remained below the $0.6 million of a year ago. Investors should not dismiss the credit charges as noise. They reflect real customers who did not pay. Management also indicated the receivables cleanup will not be finished until the end of fiscal 2027, so further charges are possible. The progress on the balance sheet is real: net receivables fell to $13.5 million, about 80% below the fiscal 2025 peak of $37.9 million. A $3.4 million court judgment against a former customer, which management views as fully collectible, offers some potential recovery.
The operating trends were mixed. Revenue rose 3.2% sequentially from $26.7 million and continued a rebound from $18.7 million in the fiscal third quarter. Gross margin recovered to 16.2% from an impairment-depressed 6.3%. Year over year, however, the picture weakened:
- Revenue growth flipped from the 33% growth cited last quarter to a 9.3% decline.
- European distributors pulled back amid disposable bans, excise changes and cautious inventory management.
- Gross margin slipped below the year-ago 17.0% because of competitive pricing pressure.
Management's tone was steady but noticeably more measured than the 'inflection point' language of the prior call.
Cash is where bears have the most legitimate ammunition. Cash fell $3.7 million in the quarter to $15.6 million, and working capital is just $0.4 million. Operating cash burn was $1.6 million, compared with $0.57 million for all of fiscal 2026. Management argued operating cash flow would have been roughly +$1.4 million excluding a $3 million paydown of aged payables to its related-party manufacturer. That adjustment is reasonable, but those payments are ongoing obligations, not one-time items. The company also paid $1.55 million toward joint-venture commitments. The amount due to the related party grew to $52 million after another $5 million of payables was reclassified as long-term, and the stockholders' deficit widened to $34.8 million.
The cash-flow-positive target for the second half of calendar 2026 has effectively lapsed. The outlook now speaks only of 'focusing on' cash-flow-positive performance while continuing to invest in Malaysia. Several previously flagged items went unaddressed on the call, including:
- a 'significant development deal' with a global nicotine company;
- the outcome of a global tobacco major's facility visit;
- a potential liquidity event at IKE Tech.
The forward story rests on Malaysia and IKE Tech. Management says it is close to an OEM/ODM agreement with a well-known Southeast Asian brand and is targeting an announcement around January 2027. It also pointed to growing supply-chain diversification interest, an approximately 25% tariff advantage, and China's planned April 2027 end of its 13% export VAT rebate on e-cigarettes, which would widen Malaysia's cost edge. IKE 2.0 launched on schedule in September. A pilot with Charlie's Holdings, using IKE's age-gating on select disposables, is planned before year-end. IKE is also in talks with multiple companies about supplemental PMTA filings. The nicotine pouch joint venture with Jincheng Pharma adds optionality. These are credible catalysts, but none is producing revenue yet.
Investor sentiment moved from slightly positive at 0.03 to modestly negative at -0.12. The decline is meaningful but not dramatic, and it suggests patience with the turnaround narrative was wearing thin. The stock behaved better. As of the pre-report snapshot, shares were at $1.55, up 8.4% since the open following the prior report. That left them 28% above the September low of $1.21 and about 5.5% below the October high of $1.64. Even so, the stock sits 13.6% below its 200-day moving average of $1.79, so the recent recovery has not repaired the longer-term damage. The AVWAP trend reads positive while price and momentum readings are neutral, consistent with a stock that has stabilized without breaking out.
The bottom line is that Ispire delivered a credible sequential repair story: positive adjusted EBITDA, restored gross margin and sharply lower receivables. It paired that progress with a large GAAP miss, shrinking year-over-year sales and a cash position that leaves little room for error. Until the Southeast Asian deal closes and Malaysia or IKE begins producing revenue, the turnaround remains a promise funded by a dwindling cash balance and continued forbearance from a related-party supplier.
Read our earnings preview for Ispire Technology Inc.: https://www.earningswhispers.com/article/ISPR/22843
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 14 hours | |
| 16 hours | |
| Nov-04 | |
| Nov-04 | |
| Sep-28 | |
| Sep-17 | |
| Sep-16 | |
| Sep-09 | |
| Aug-17 | |
| May-12 | |
| May-11 | |
| May-07 | |
| May-01 | |
| Apr-28 | |
| Apr-23 |
