Hain Celestial Misses As Margin Gains Collide With A Stalled Debt Fix And A Looming December Maturity
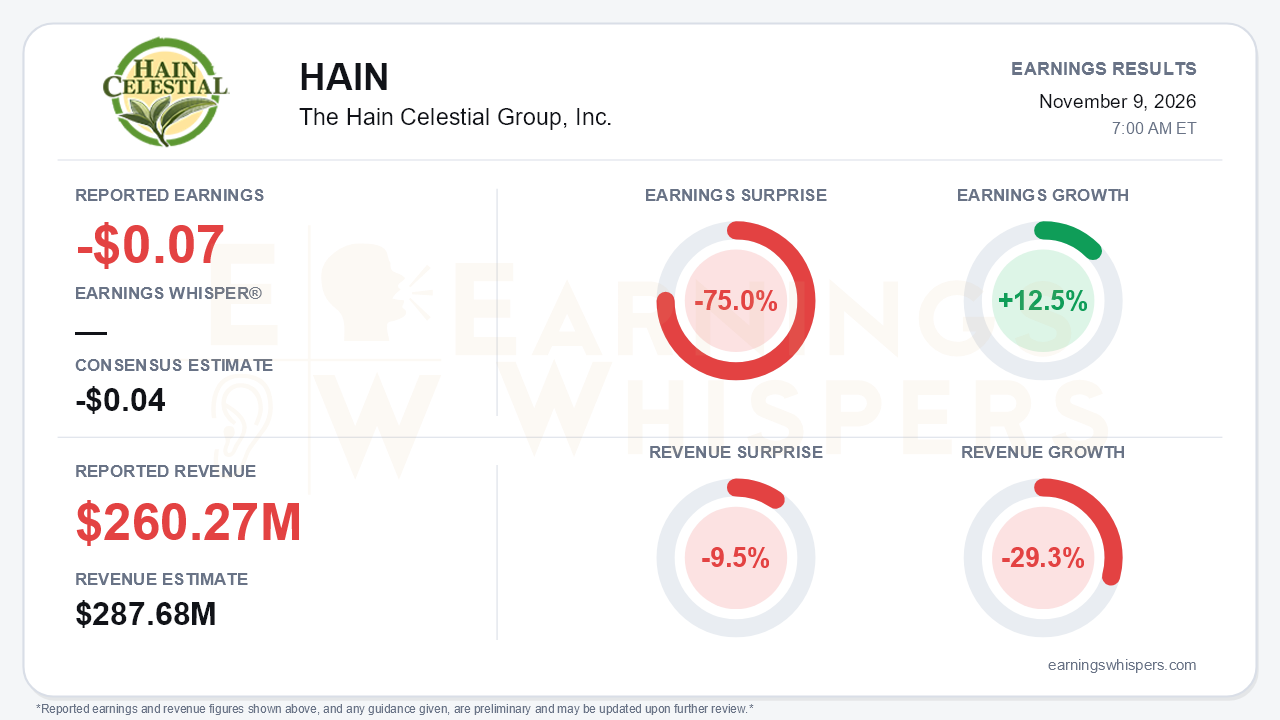
Hain Celestial's fiscal first quarter was not mainly about the miss, although the miss was real. The company reported an adjusted loss of $0.07 per share against a consensus loss of $0.04, a 75.0% shortfall. Revenue of $260.27 million fell 29.3% year over year and missed the $287.68 million consensus by 9.5%. The loss improved 12.5% from the prior-year adjusted loss of $0.08. The quarter's defining development, however, came outside the income statement. The $323 million sale of the International business to AURELIUS, the centerpiece of Hain's deleveraging plan, missed a key closing condition. Meanwhile, the company's credit facility comes due in December. That is the central tension: operational progress on margins is now subordinate to a capital-structure problem that remains unresolved.
The quality of the quarter deserves scrutiny. GAAP loss per share narrowed to $0.12 from $0.23, but that improvement leaned on a $14.8 million non-cash gain on remeasurement of assets reclassified to held and used. Adjusted operating income fell to $3.0 million from $8.2 million, and adjusted EBITDA slipped to $18 million from $20 million a year ago. That figure was also down from $19 million in the fourth quarter and $26 million in the third.
Cash moved the wrong way:
- Free cash flow was negative $23 million, versus negative $14 million a year earlier.
- Net debt rose to $523 million from $500 million at the start of the fiscal year.
- All $586 million of total debt now sits in current liabilities.
- Net secured leverage climbed to 5.3x, up from 4.5x last quarter, against the 5.5x covenant cited on the call.
Beneath the headline, the margin story is genuinely improving. Adjusted gross margin expanded 320 basis points to 22.8%, largely because the low-margin North American snacks business is gone. North America adjusted gross margin reached 33.5% and adjusted EBITDA margin 15.6%, ahead of the 30%-plus gross margin and low-double-digit EBITDA targets first laid out for the pro forma business. Management also said:
- All $25 million of snacks stranded overhead has been removed ahead of schedule.
- Roughly $8 million of a $16 million SG&A run-rate savings program has already been actioned.
- SG&A fell 6% to $62 million.
The top line, however, lost ground. Organic sales fell 6.7%, worse than the roughly 2% decline in the fourth quarter, with volume/mix down 7 points. North America swung from 2% organic growth last quarter to a 6% decline, hit by baby and kids, beverages and meal prep. The call cited a temporary Greek Gods yogurt supply disruption, warm weather and inventory cycling in tea, and share and distribution losses in baby and kids. International was weaker still. Organic sales there fell 7%, adjusted gross margin compressed to 14.9% amid energy, freight and packaging inflation, and segment EBITDA dropped 29%.
There are bright spots. Ella's Kitchen returned to high-single-digit growth, Greek Gods grew mid-single digits despite the supply problem, and priority e-commerce platforms for tea and Earth's Best grew more than 30% at the largest pure-play customer. Those are brand-level wins inside a shrinking whole, and they cannot offset the financing risk.
What changed most is management's posture on the balance sheet:
- Final regulatory approvals for the International sale arrived, but the required credit-agreement amendment was not signed by October 12. The deal is now only in "discussions" with AURELIUS.
- The December maturity is the stated immediate priority. Earlier language about being confident Hain would refinance, extend or repay has given way to "evaluating all available paths."
- There was no guidance and, for the second straight quarter, no Q&A.
- The release's risk factors now include potential cessation of the stock's Nasdaq listing.
Bears have legitimate ammunition here, and management offered little to rebut it.
The market had largely priced in distress before the report. Shares stood at $0.15, down 76.4% from the $0.63 opening after the prior report and 77.6% below the 200-day moving average of $0.67. The stock hit a 52-week low of $0.12 on October 30, shortly after the amendment deadline passed, and has since bounced about 27%. Investor sentiment, measured just before the release, remained negative but improved slightly, from -0.3167 to -0.2785. That is a modest shift rather than a reassessment. Price and AVWAP trend readings remain negative.
The bottom line is that Hain is executing on cost and mix: North America margins are already beyond pro forma targets, and stranded costs are gone. But that progress has been overtaken by a stalled asset sale, rising leverage near its covenant, negative free cash flow and an imminent maturity with no announced solution. Weakening organic sales in both segments undercut the argument that the go-forward business can carry the debt on its own. Until lenders and AURELIUS reach a resolution, the equity's fate depends more on the capital structure than on quarterly operating results.
Read our earnings preview for The Hain Celestial Group, Inc.: https://www.earningswhispers.com/article/HAIN/22780
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-03 | |
| Nov-02 | |
| Oct-15 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 | |
| Aug-17 | |
| Jul-30 | |
| Jul-15 | |
| May-18 |
