AllianceBernstein: Emerging-Market Debt: The Next Frontier for AI Disruption
NORTHAMPTON, MA / ACCESS Newswire / November 9, 2026 / Adriaan du Toit | Head of Emerging Market Sovereign and Corporate Credit Research (ex-Asia)
Elizabeth Bakarich, CFA | Head-Emerging Market Corporates
Christian DiClementi | Head-Emerging Market Debt
The rise of artificial intelligence could redefine leaders and laggards in emerging markets.
Artificial intelligence (AI) leadership is no longer a developed-market monopoly. Emerging markets (EM) now have their own AI champions, and productivity gains may follow. For bond investors, we expect the implications to differ by country-driven by industry composition, capital intensity, digital infrastructure and speed to adoption.
Methodology Matters When Evaluating EM Corporates
For EM corporate bond investors, the key issue is credit differentiation. AI can strengthen or weaken industry economics by changing costs, competition and pricing power. To assess those effects consistently across industries, we focus on the mechanisms that we believe matter most for credit outcomes:
- Functional displacement-Does AI threaten the industry's core economic function?
- Entry barrier erosion-Does AI weaken structural barriers to competition?
- Margin structure vulnerability-Are profits supported by scarcity or informational advantage?
- Structural tailwind potential-Does AI strengthen industry economics through cost, demand or scale?
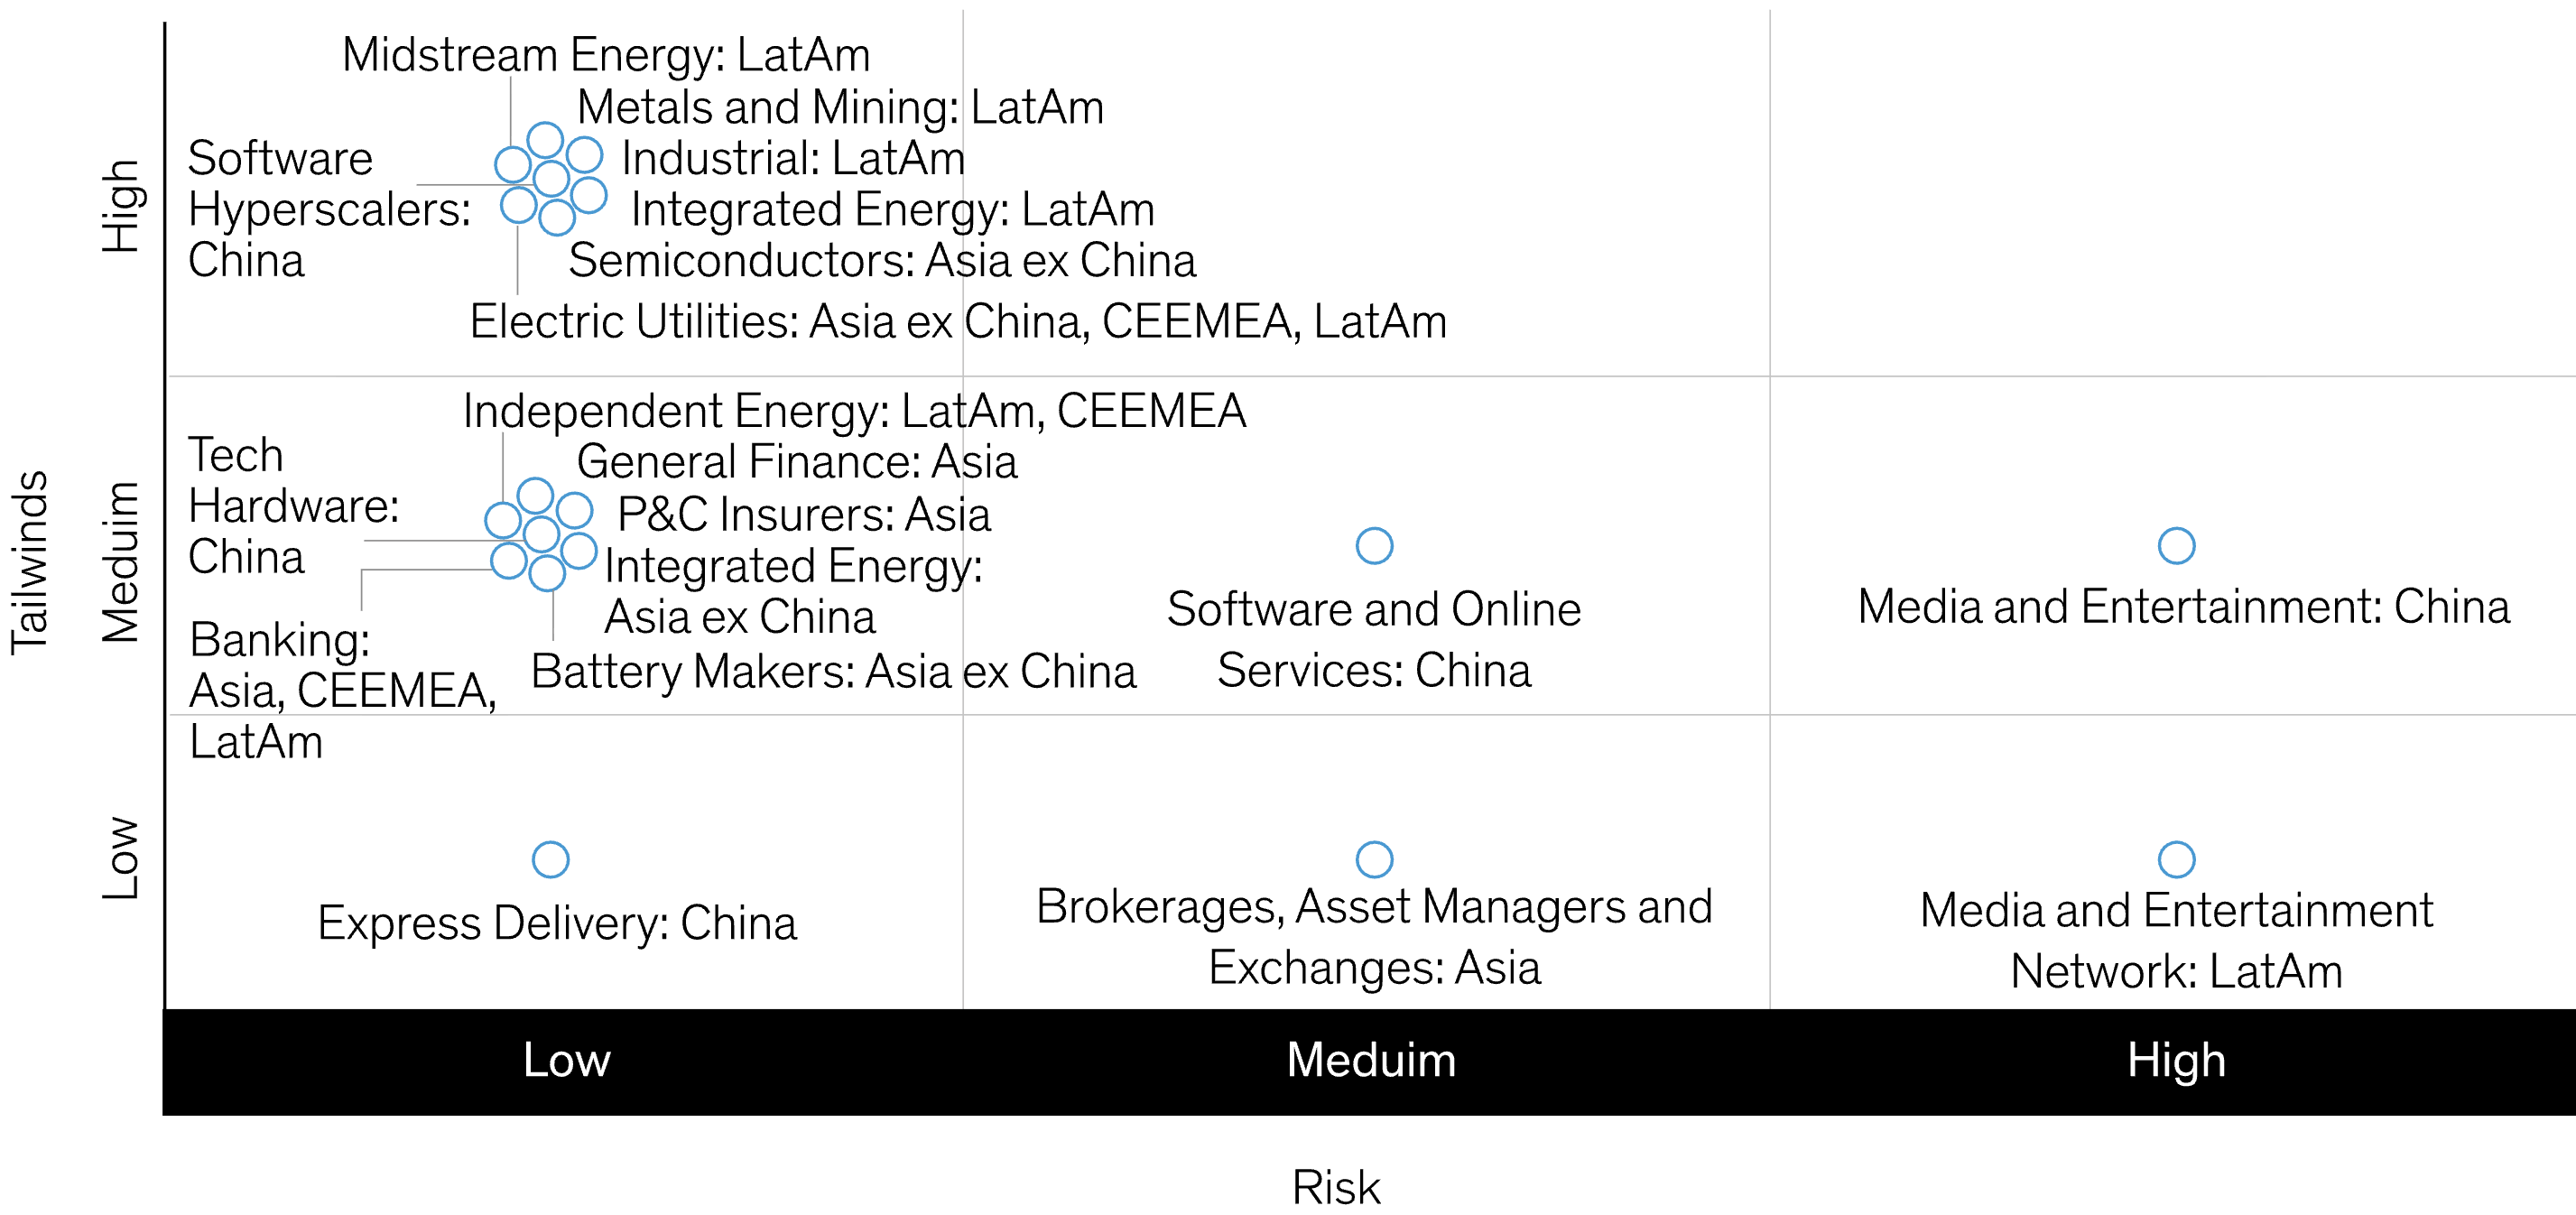
A matrix analysis summarizes key exposures, vulnerabilities and opportunities (Display).
AI Creates Diverging Credit Exposures Across EM Industries
Framework Mapping EM Industries: AI-Driven Tailwinds vs. Risk of Disruption
Current analysis does not guarantee future results. For illustrative purposes only.
CEEMEA: Central and Eastern Europe, Middle East and Africa; LatAm: Latin America; P&C: property and casualty
As of April 30, 2026
Source: AllianceBernstein (AB)
Applying the Framework: AI Exposures Across Industries
In our assessment, industries with a low risk of functional displacement and clear structural tailwinds from AI span the economy, from metals and mining to software and hyperscalers. Because AI is resource-intensive, companies tied to critical inputs-such as copper mining and energy production in commodity-rich countries-appear well positioned to benefit from rising demand without facing near-term erosion of industry economics.
By contrast, consumer-facing digital services show greater vulnerability. In media and entertainment and on online platforms, AI-driven search and agentic interfaces threaten established discovery and advertising models. Large online service providers in China, for example, face the risk that traditional feed-based engagement gives way to AI-mediated interaction, potentially compressing margins.
Financial-services issuers generally fall between these extremes. Brokerages, asset managers and exchanges rely heavily on information and analytical advantages that AI could partially erode. However, licensing, regulation and scale remain meaningful barriers to entry, limiting the extent of structural disruption-even as competitive pressure intensifies.
Regardless of industry or macro trends, evaluation of individual corporate bond issuers should remain anchored in cash-flow durability and balance-sheet resilience, in our view.
A Complementary Framework for Sovereigns
We believe that assessing AI-related risks and opportunities at the country level requires a different lens. Our sovereign analysis centers on structural leverage within the AI ecosystem-particularly where countries sit in critical supply chains.
- Which countries hold structural leverage in AI supply chains?
- Which critical commodities underpin Al infrastructure and deployment?
- Which countries control the production, processing or supply of those inputs?
- Which economies are most reliant on services with meaningful Al exposure?
Although developed economies appear better positioned to capture AI-driven growth in the near term, strategic control of key supply-chain chokepoints may give some EMs longer-term advantages.
The economies with the strongest indicators of AI structural leverage (Display) include Asian EMs that provide essential components and manufacturing capabilities for AI infrastructure. Several EMs also offer less-visible "backdoor" exposures-such as power and thermal management and data-center components-that are critical to AI deployment.
AI Structural Leverage Is Concentrated in a Few Critical Countries
Countries Ranked by Control over Key Supply-Chain Chokepoints
Historical and current analyses do not guarantee future results.
EUV: extreme ultraviolet
As of April 30, 2026
Source: AB
AI-Critical Commodities Concentrate in Emerging Markets
The build-out of AI technology and the infrastructure to support it depend on a narrow set of commodities-and the capabilities to extract and process them. Many of these materials, including key metals and rare earth elements, are concentrated in the developing world. Accordingly, EMs lead the global extraction and processing of several AI-critical inputs, giving some countries structural exposure to the AI build-out through upstream supply chains (Display).
AI Infrastructure Relies on Commodities Concentrated in EM
Key Commodities Needed for AI and the Countries That Lead Their Production and Processing
Historical and current analyses do not guarantee future results.
GPU: graphics processing unit; TPU: tensor processing unit; DRC: Democratic Republic of the Congo
As of April 30, 2026
Source: AB
In our view, as AI adoption and innovation surge, fueling greater demand for these essential commodities, some countries-such as China, Chile, Brazil and Indonesia-could see an uptick in economic growth and overall creditworthiness.
Service-Based Economies Face Greater AI Disruption Risk
Much of the routine service and software needs of developed economies have been outsourced to EMs, creating a greater potential exposure to AI disruption. Some large economies with meaningful exposure-particularly if they fail to adapt-are in Asia; these include the Philippines, India and Malaysia. Parts of Central and Eastern Europe may also be vulnerable, in our analysis, given their reliance on IT and business-services outsourcing (Display).
AI-Exposed Services Play an Outsize Role in Some Emerging Economies
Services as a Share of GDP in 2024 (Percent)
Historical and current analyses do not guarantee future results.
As of February 28, 2026
Source: World Bank and AB
Keep an Eye on AI Impacts-and Diversify Exposure
While the effects of AI on EM corporate and sovereign bonds have yet to fully materialize, the mechanisms of exposure are becoming clearer. Assessing their impacts will require ongoing research and monitoring as AI adoption evolves across economies, industries and supply chains.
For bond investors, selective diversification across EM regions, countries and fixed-income sectors remains important. We believe that allocations to EM corporates can complement sovereign-debt exposures and US credit exposures by broadening country and issuer coverage, increasing exposure across different parts of the credit cycle and, in some cases, offering a spread premium relative to sovereign debt.
As AI adoption advances, distinguishing lasting credit effects from temporary noise will matter more than predicting the pace of change.
The views expressed herein do not constitute research, investment advice or trade recommendations, do not necessarily represent the views of all AB portfolio-management teams and are subject to change over time.
Learn more about AB's approach to responsibility here.
Find more stories and multimedia from AllianceBernstein at 3blmedia.com.
Contact Info:
Spokesperson: AllianceBernstein
Website: https://www.3blmedia.com/profiles/alliancebernstein
Email: info@3blmedia.com
SOURCE: AllianceBernstein
View the original press release on ACCESS Newswire
Mentioned In This Article
Latest News
| 5 hours | |
| Nov-05 | |
| Nov-04 | |
| Nov-03 | |
| Oct-30 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-14 | |
| Oct-12 | |
| Oct-02 | |
| Oct-01 | |
| Sep-29 | |
| Sep-25 |
