Virtuix Must Turn Its Meta-Fueled Order Surge Into Revenue As Cash Runs Thin
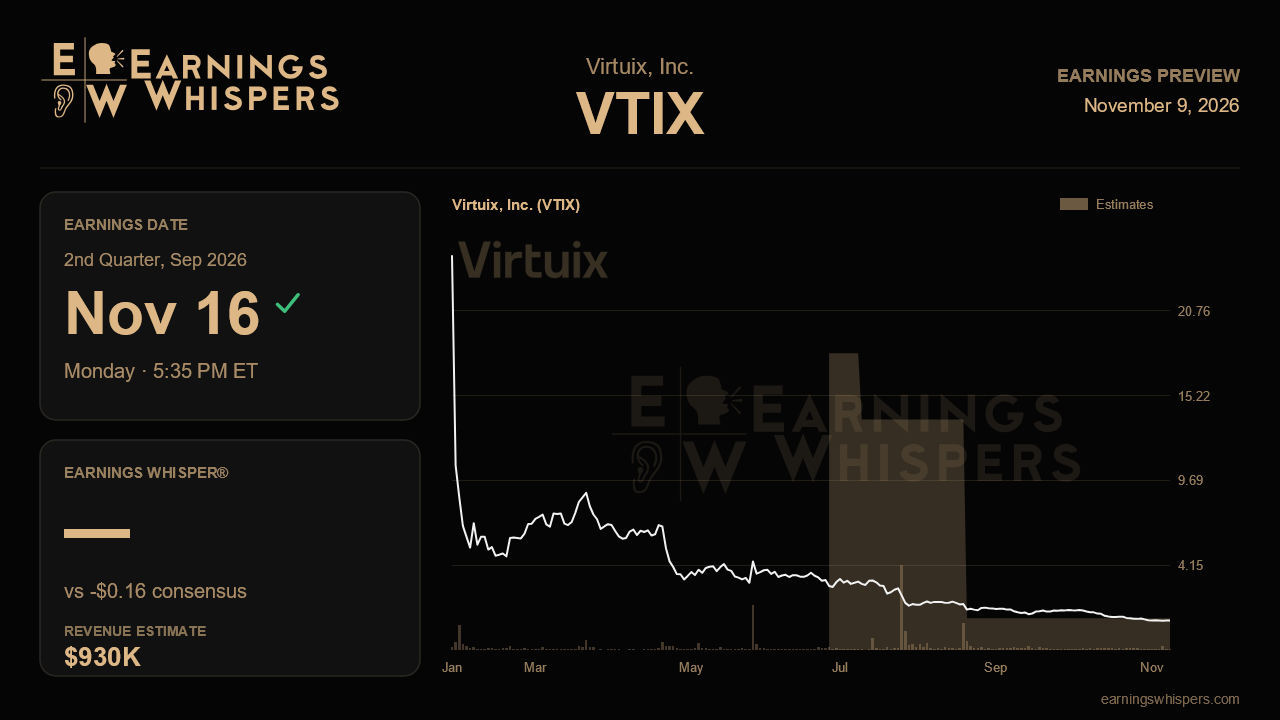
Virtuix heads into its September-quarter report with a strange mismatch. Last quarter management described one of its strongest commercial stretches in recent memory, with new orders up 72% from a year earlier and roughly two and a half times higher since the Made-for-Meta OmniOne for Quest launched in late June. The stock, meanwhile, has lost about two thirds of its value since that report. When the company posts results after the close on November 16, the question is simple. Is the order momentum finally showing up in revenue, and can it arrive fast enough to outrun a shrinking cash balance?
The Street is looking for revenue of about $930,000 and a loss of $0.16 per share. That revenue figure would be roughly 21% above the $767,000 reported last quarter, a modest absolute number but a meaningful sequential test. Management attributed last quarter's year-over-year revenue decline to the runoff of an old pre-order backlog rather than weaker demand. If orders really jumped after the Meta launch, shipments in the September quarter should reflect it. A print that clears consensus would support the timing explanation. One that stalls near the prior level would make the backlog argument look more like a convenient excuse. The company has not issued formal guidance, so the consensus figure is the main yardstick.
Margins are the second piece of the story. Gross margin climbed to 30% last quarter from 25% for the prior fiscal year, helped by higher selling prices, and management reaffirmed long-run targets of about 40% on consumer units and above 70% on enterprise systems. Holding near 30% while volume rises would suggest pricing power is real. A slide back toward the low 20s would hint that the earlier gain depended on mix or one-off pricing. Enterprise and specialty wins, including the first OmniOne Enterprise sale to Tesla for Optimus teleoperation, the NASA analog mission, the Sirica Therapeutics autism therapy partnership targeting around 100 centers, and the first Air National Guard deployment, matter because they carry the richest margins. Evidence of follow-on orders, rather than single proof-of-concept units, would go a long way. The Marine Corps Infantry Fire Team Trainer, where Virtuix is lead integrator, already slipped from around September to the fourth calendar quarter, so any further delay would be a warning sign. Management also framed a Meta bundling arrangement as a near-term conversation, and concrete progress there would be the most important upside surprise available.
The balance sheet is where the risk concentrates. Cash fell to $7.4 million at the end of June from $9.5 million in March, with burn running near $1 million a month, and stockholders' equity had swung to a $3.1 million deficit. At that pace, the September cash figure could be uncomfortably low, and the market will want clarity on financing plans and dilution. The net loss of $7.2 million last quarter included about $4 million of non-cash charges, so a cleaner quarter could narrow the loss even without dramatic revenue gains. After an auditor change that delayed the last filing and forced a revision to the March balance sheet, an on-time, uneventful filing would itself help rebuild credibility.
Sentiment has edged from modestly bearish before last quarter to slightly bullish now, though neither reading is strong. The chart tells a harsher story. At $0.54, shares sit far below the 200-day moving average of $3.63 and just above the $0.47 low of the post-earnings range, well beneath the $1.42 to $3.71 band of the prior quarter. The market has clearly been pricing financing risk over commercial progress.
That sets up the central issue. Virtuix's narrative holds together only if rising orders convert into sequential revenue growth at stable margins while management shows a credible path to funding operations. Deliver on both, and the gap between the business story and the stock price becomes hard to ignore. Miss on either, and the balance sheet will keep doing the talking.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-09 | |
| Oct-29 | |
| Oct-27 | |
| Oct-14 | |
| Oct-13 | |
| Oct-08 | |
| Oct-06 | |
| Sep-30 | |
| Sep-23 | |
| Sep-18 | |
| Sep-17 | |
| Sep-16 | |
| Sep-15 |
