Dole Misses Badly On Adjusted EPS And Cuts EBITDA Guidance Again As Port-Sale Gain Flatters GAAP Results
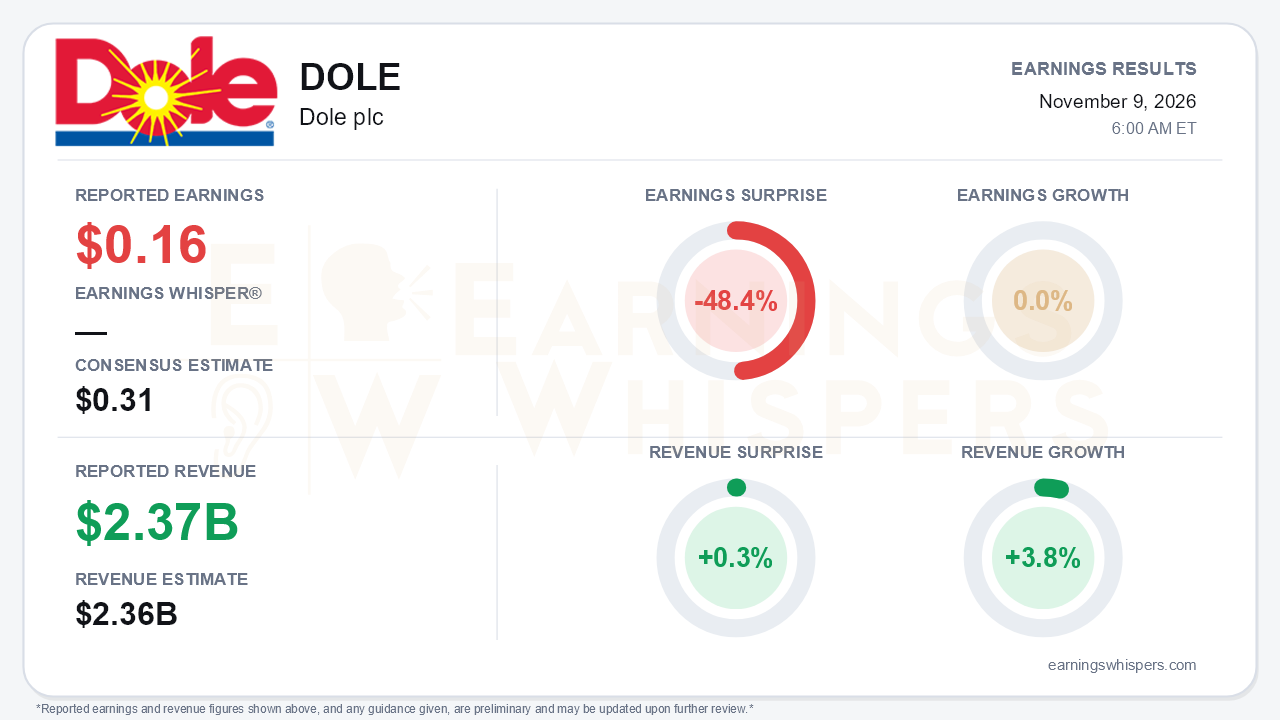
Dole plc's third quarter looked better on the surface than it was underneath. Adjusted EPS of $0.16 missed the $0.31 consensus by 48.4% and was unchanged from a year ago. Revenue of $2.366 billion edged past the $2.36 billion estimate by 0.3% and grew 3.8%. Management also cut full-year Adjusted EBITDA guidance to $380 million to $390 million from roughly $400 million. That is the second consecutive reduction, following an earlier target of "at least $400 million." That is the central tension: a quarter of modest operating improvement and a much stronger balance sheet, overshadowed by a guidance path that keeps moving the wrong way.
The quality of the reported numbers deserves scrutiny. GAAP diluted EPS jumped to $0.41 from $0.05, but almost all of that improvement came from a $48.6 million gain on the Ecuador port sale, partly offset by a $22.2 million tax charge tied to the deal. The prior-year comparison was also burdened by a $10.2 million loss from discontinued Fresh Vegetables operations. Strip those items out and the picture is static. Adjusted net income held at $15.0 million despite a 4.1% rise in Adjusted EBITDA to $84.1 million, because higher adjusted tax expense and lower equity-method earnings absorbed the gains from lower interest and depreciation. On a like-for-like basis, revenue rose only 2.0%. Over nine months, like-for-like Adjusted EBITDA is down $26.2 million, driven by a $32.2 million decline in Fresh Fruit.
The segment mix explains both the resilience and the fragility.
- **Diversified Fresh Produce – Americas & ROW** remains the clear bright spot. Revenue rose 14.1% and Adjusted EBITDA climbed 22.8% on strong North American volumes in kiwi, avocados, grapes and tomatoes, extending a streak of double-digit gains.
- **Fresh Fruit** returned to EBITDA growth, up 6.0% to $28.8 million, after declines in the first two quarters. Lagged North American fuel surcharges and better banana pricing helped, but segment revenue fell 8.0% on tariffs and weather-hit volumes.
- **Diversified Fresh Produce – EMEA** delivered a 9.3% revenue increase, largely from the Greenfood acquisition, yet EBITDA slipped 3.1% on weakness in the Netherlands and Spain. Management now expects the segment to finish the year only flat, a retreat from earlier talk of continued positive momentum.
The call made clear that the cost environment, not demand, is the problem. European shipping fuel is not covered by surcharge mechanisms and is now expected to cost about $16 million against the original 2026 plan, with Brent cited near $106 in the fourth quarter. Management described El Niño as running at the strong end of forecasts, hurting banana and pineapple yields across Central America, Colombia and northern Peru. Pineapple is also dealing with quality and sizing issues, and a strong Costa Rican colón is adding pressure. Disruption in South Africa from the Middle East conflict lingers. The expected fourth-quarter improvement in Fresh Fruit is now smaller than flagged in August. The tone shifted noticeably, from earlier "positive momentum" language to "resilience" in a "challenging" backdrop. Management also called 2027 Fresh Fruit visibility uncertain, with pricing recovery hinging on fixed-price contract negotiations now underway.
The offsetting catalysts are mostly financial. Nine-month free cash flow from continuing operations swung to a $59.3 million inflow from a $66.2 million outflow. The call cited third-quarter free cash flow of $110.4 million versus $66.5 million a year earlier, a figure the release does not separately break out. The Ecuador proceeds cut net debt to $491.3 million and net leverage to 1.3x, from 2.0x at the second quarter. Buybacks reached $24.6 million year to date, with $75.4 million still authorized. Capex guidance was trimmed to about $90 million, which helps cash but also signals caution. The Greenfood deal and planned Helsingborg automation offer longer-dated upside in Scandinavia.
The market setup is more complicated than the miss implies. Investor sentiment improved from slightly negative (-0.05) to modestly positive (0.14) heading into the report, so expectations had been rebuilding. The shares had rallied more than 10% off a 52-week low of $12.59 set on October 1. As of the pre-report snapshot, they sat at $13.88, up 7.1% since the open after the August report and just 2.4% below the inter-earnings high set on November 5. Yet the stock remained about 2.8% below its 200-day moving average of $14.27. That combination left shares running into the print near the top of their recent range just as management delivered another guidance cut.
The bottom line is that Dole's balance sheet and cash generation are materially stronger than a year ago, and the Americas business keeps compounding. But the earnings engine is stalling under fuel, weather and currency pressures that management cannot fully pass through, at least until 2027 contracts reset. The adjusted EPS miss and a second straight guidance reduction give bears legitimate ammunition. Recently improved sentiment now has to contend with a quarter that lowered, rather than validated, the earnings trajectory.
Read our earnings preview for Dole plc: https://www.earningswhispers.com/article/DOLE/22561
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-04 | |
| Nov-02 | |
| Oct-30 | |
| Oct-19 | |
| Sep-16 | |
| Aug-19 | |
| Aug-12 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Jul-31 | |
| Jul-31 |
