Bicara Therapeutics Misses As Losses Widen; Enrollment Milestone Overshadowed By A Competitive Reset In Head And Neck Cancer
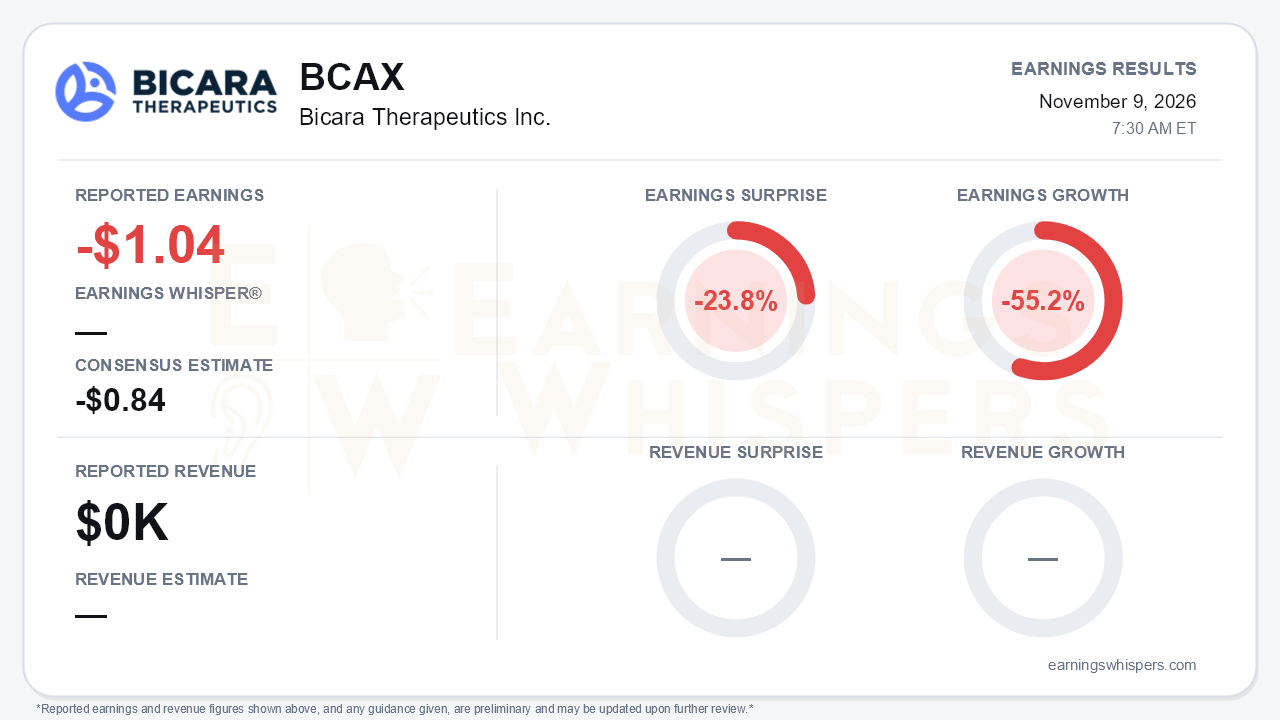
Bicara Therapeutics reported a third-quarter loss of $1.04 per share, missing the consensus estimate of -$0.84 by 23.8%. Earnings fell 55.2% year over year as the net loss widened to $71.2 million from $36.3 million. As a clinical-stage company with no revenue, Bicara's miss matters less than what changed around its lead asset, ficerafusp alfa. The company delivered the operational milestone it had promised for most of a year. At the same time, the competitive and strategic narrative around that milestone shifted, and the call took a noticeably more defensive tone. That is the central tension: execution improved, but the investment story got harder to tell.
The miss was driven by spending. Total operating expenses rose to $75.7 million from $40.7 million a year earlier:
- **R&D** rose to $56.5 million from $33.0 million, reflecting the FORTIFI-HN01 pivotal trial, the FORTIFI-FLEX dosing study and Phase 1b expansion cohorts.
- **G&A** more than doubled to $19.2 million from $7.7 million as the company built out for potential commercialization.
- **Stock-based compensation** nearly tripled to $10.0 million, accounting for a meaningful share of the G&A increase.
- **Interest income** of $4.5 million was essentially flat and offset little of the higher spending.
Per-share losses also absorbed a larger share count, about 68.4 million weighted-average shares versus 54.6 million a year ago. The balance sheet still looks sturdy on the surface. Cash and marketable securities were $442.3 million, above the year-end 2025 level, and runway guidance into the first half of 2029 was unchanged. The sequential trend is less comforting. Cash has fallen from $539.8 million in the first quarter to $497 million in the second and $442.3 million now. Accrued liabilities also jumped to $46.2 million from $18.9 million at year-end, which suggests reported cash burn may understate the true run-rate of trial costs.
On the call, the execution story held up. FORTIFI-HN01 reached substantial enrollment, meeting the target management had reiterated on each of the prior three calls. Management said the roughly 650-patient, HPV-negative-only trial will not need to be upsized, and it reaffirmed mid-2027 timing for topline interim results. The company also confirmed a planned interim overall survival analysis, though it has not disclosed the timing or scope. The Phase 1b dataset remains the foundation of the bull argument:
- 54% response rate and 25% complete responses
- Median duration of response of about 22 months
- Median overall survival just over 21 months
- Roughly one in three patients alive at three years
The commercial leadership team is now in place, and FORTIFI-FLEX continues with an unchanged design.
The risks are what changed. Genmab's petosemtamab produced a topline readout that included an overall survival hazard ratio ahead of Bicara's interim analysis. Management now concedes it trails by less than a year to approval. The messaging shifted accordingly. Earlier calls described ficerafusp alfa as "best and first in class," while this call argued that being first to market does not guarantee leadership. Management now expects both drugs' initial labels to carry a survival component, a departure from earlier assumptions built around response-rate-based accelerated approval. It frames this as a chance to compete on survival but declined to detail its regulatory strategy. Bears have other ammunition as well:
- Ryan Cohlhepp is serving as interim CEO "since earlier this fall," rather than taking over permanently in January as planned last quarter.
- Third-line colorectal cancer data slipped from the second half of 2026 to January 2027.
- A later-line amivantamab approval in head and neck cancer introduces potential post-progression confounding of survival data, though management sees limited exposure.
The market had already priced in much of this deterioration before the report. Shares opened at $22.80 after the August release, peaked at $26.95 on August 19, and then collapsed to a 52-week low of $7.87 on November 2. At $8.65, the stock is down 62.1% since the prior report and sits 58.8% below its 200-day moving average of $20.98. Investor sentiment moved from roughly neutral at -0.01 to clearly negative at -0.32, a substantial shift that reflects how quickly the competitive narrative turned. Earnings Whispers trend readings are predominantly negative, with momentum the lone positive reading as shares bounced modestly off their low. Based on the weighted-average share count, the equity is valued not far above the company's cash. In effect, the market is assigning limited value to ficerafusp alfa until it sees survival data.
The bottom line is that Bicara executed on the milestone that mattered most, but the quarter redefined what success must look like. The rationale for owning the stock no longer rests on being first; it now depends on ficerafusp alfa showing a competitive survival profile against petosemtamab in mid-2027. Rising spending, an interim CEO and a delayed colorectal readout leave little margin for error. With the stock near its lows and cash covering much of its value, the next meaningful re-rating in either direction likely awaits the FORTIFI-HN01 interim data rather than anything on the income statement.
Read our earnings preview for Bicara Therapeutics Inc.: https://www.earningswhispers.com/article/BCAX/22553
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-04 | |
| Nov-02 | |
| Nov-02 | |
| Oct-05 | |
| Sep-03 | |
| Aug-14 | |
| Aug-11 | |
| Aug-11 | |
| Aug-04 | |
| Jul-28 | |
| Jul-02 | |
| May-21 | |
| May-13 |
