Somnigroup's Record Quarter Is Acquisition-Built, And A Third Guidance Cut Exposes A Shrinking Core
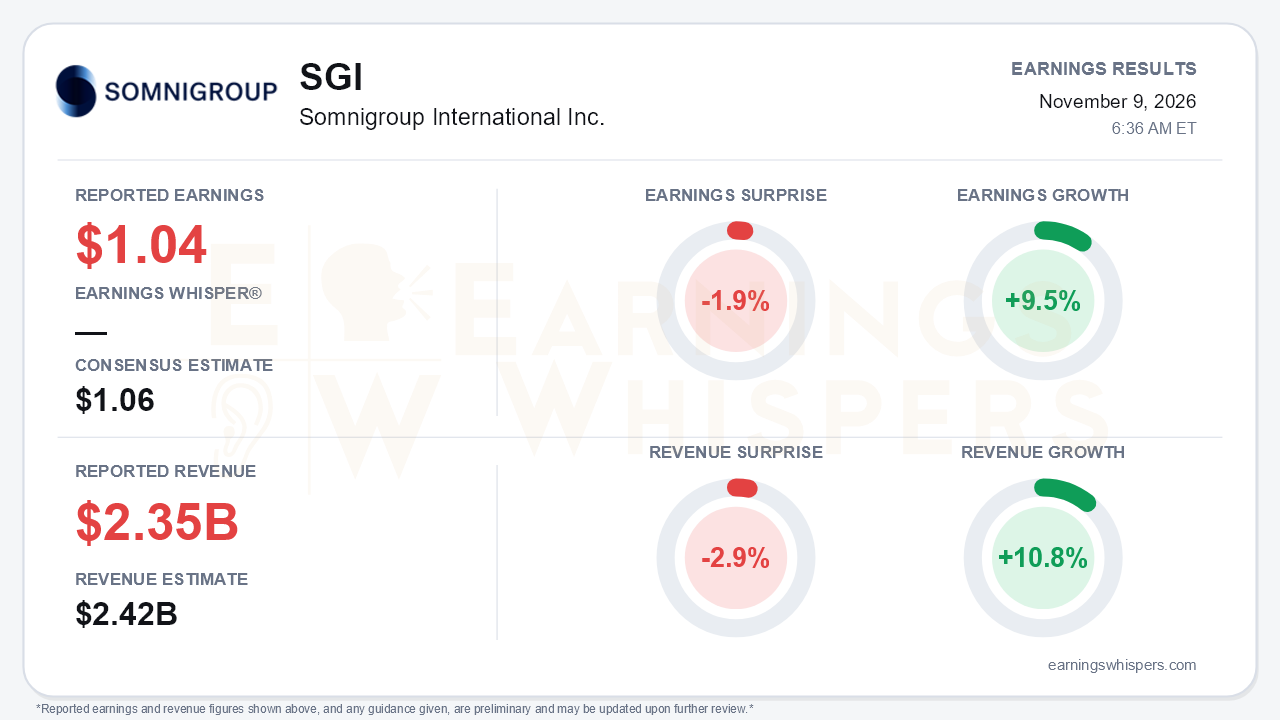
Somnigroup International posted record third-quarter adjusted EPS of $1.04, up 9.5% from a year ago, on revenue of $2.351 billion, up 10.8%. Both figures still fell short of expectations. Earnings missed the $1.06 consensus by 1.9%, and revenue missed the $2.42 billion estimate by 2.9%. The bigger problem is underneath the record. The growth came almost entirely from roughly five weeks of Leggett & Platt ownership, while the legacy business shrank. Management also lowered full-year guidance for the third consecutive quarter. That is the central tension: acquisitions are inflating the headline numbers just as the core bedding franchise is losing ground.
The quality of the quarter deserves scrutiny. Leggett & Platt contributed $372.6 million of sales for the stub period after the deal closed on August 26. Without that contribution, net sales would have declined from $2.12 billion to under $1.98 billion. All three legacy segments shrank:
- Mattress Firm sales fell 5.8%.
- Tempur Sealy North America sales fell 5.8%, with wholesale down 7.2%.
- International sales fell 12.3%.
On a GAAP basis, EPS fell 10.8% to $0.74, weighed down by $35.5 million of transaction costs and a $13 million debt-extinguishment loss. Consolidated adjusted gross margin slipped to 43.0% from 45.6%, partly because Leggett carries much lower margins.
North America looked like a bright spot, with adjusted gross margin up 690 basis points to 65.5%. That improvement leaned on about $20 million of tariff refunds and $25 million of Mattress Firm synergies. The refunds will not recur, so that margin level should not be treated as a new baseline.
The call showed how quickly the operating picture has deteriorated:
- **Dreams:** On the Q2 call, management described the UK retailer's ERP rollout as going well and said disruption would last at most another quarter. Instead, Dreams sales fell 34.7%, costing roughly $50 million of sales and $25 million of EBITDA. International operating margin collapsed 870 basis points to 9.4%.
- **Mattress Firm:** Same-store sales slid about 2%, versus flat in Q1 and slightly positive in Q2, with management acknowledging self-inflicted online weakness.
- **Freight costs:** Roughly $15 million of transportation and petroleum inflation erased an expected second-half price-cost benefit. Management signaled another price increase is likely in the first half of 2027.
- **Industry outlook:** Management now expects the industry to decline mid-single digits in the second half. That view has steadily worsened from "flat to slightly up" a year ago.
- **Segment outlooks:** North America and International like-for-like outlooks were cut to flattish, and Mattress Firm's to down low-single digits.
Earnings Whispers characterizes the guidance as narrowed, but it is more accurately a cut. The adjusted EPS range of $2.85 to $2.95 keeps the old low end while removing the top of the prior $2.85 to $3.15 range. That moves the midpoint to $2.90, down from $3.00 last quarter and $3.20 at the start of the year. Raised sales and EBITDA targets reflect Leggett consolidation, not organic improvement.
The call preserved a credible self-help story for 2027, and bulls will lean on it. Management framed a $3.40 EPS run-rate built from three pieces:
- the $2.90 midpoint;
- about $0.25 of Leggett wraparound accretion;
- about $0.25 from roughly $125 million of incremental synergies.
Management said that path requires no industry recovery, and estimated each point of industry growth adds about $0.10. Other planned catalysts include a Stearns & Foster launch that has taken about 6% incremental floor slots from competitors, a next-generation Tempur-Pedic Breeze launch in March 2027, and Mattress Firm store expansion toward 2,500-plus locations.
Bears have legitimate ammunition, however. Management's forecasts have repeatedly proven too optimistic, and Leggett adds exposure to soft residential and automotive end markets. The 2028 target of $5.15 now implies roughly 23% annual growth on a weaker revenue base, and management signaled it may be lowered.
Cash generation was a genuine positive. Operating cash flow reached $349 million, and free cash flow was about $290 million versus $182 million in Q2. Reported leverage fell to 2.69 times from 3.28 times a year earlier. Investors should note that the covenant calculation includes $330.5 million of pre-acquisition Leggett EBITDA and $145 million of synergies not yet realized.
Investor sentiment improved ahead of the report, rising from roughly neutral at 0.03 to a modestly positive 0.21. The stock has not followed that improvement. Shares entered the report at $64.17, down 1.7% from the open after the August release. That leaves them 12.2% below the 200-day moving average of $73.10.
The stock briefly reached $70.94 in early September, shortly after the Leggett closing, then fell to a 52-week low of $60.08 on October 1. It now sits only 6.8% above that low. Momentum and AVWAP trend readings remain negative, although the sequential growth reading is positive, reflecting the acquisition-driven step-up in reported scale. Modestly firmer sentiment heading into a report that delivered a two-sided miss and another guidance reduction makes the setup more fragile than the record headline implies.
The bottom line is that Somnigroup is assembling a larger, more vertically integrated bedding platform while its existing businesses lose volume and its forecasts keep slipping. The 2027 bridge, synergy pipeline and strong cash flow give the story a credible path. Credibility, however, is the scarce asset after three straight guidance cuts and a Dreams disruption that management underestimated. Until legacy sales stabilize and the company meets a forecast cleanly, the record adjusted numbers will be read more as acquisition math than as a turn in the underlying business.
Read our earnings preview for Somnigroup International Inc.: https://www.earningswhispers.com/article/SGI/22590
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-23 | |
| Oct-15 | |
| Oct-12 | |
| Oct-11 | |
| Oct-08 | |
| Oct-05 | |
| Sep-22 | |
| Sep-09 | |
| Aug-27 | |
| Aug-27 |
