CECO Misses By A Penny, But A Far Bigger 2027 Outlook Collides With A 36% Stock Slide
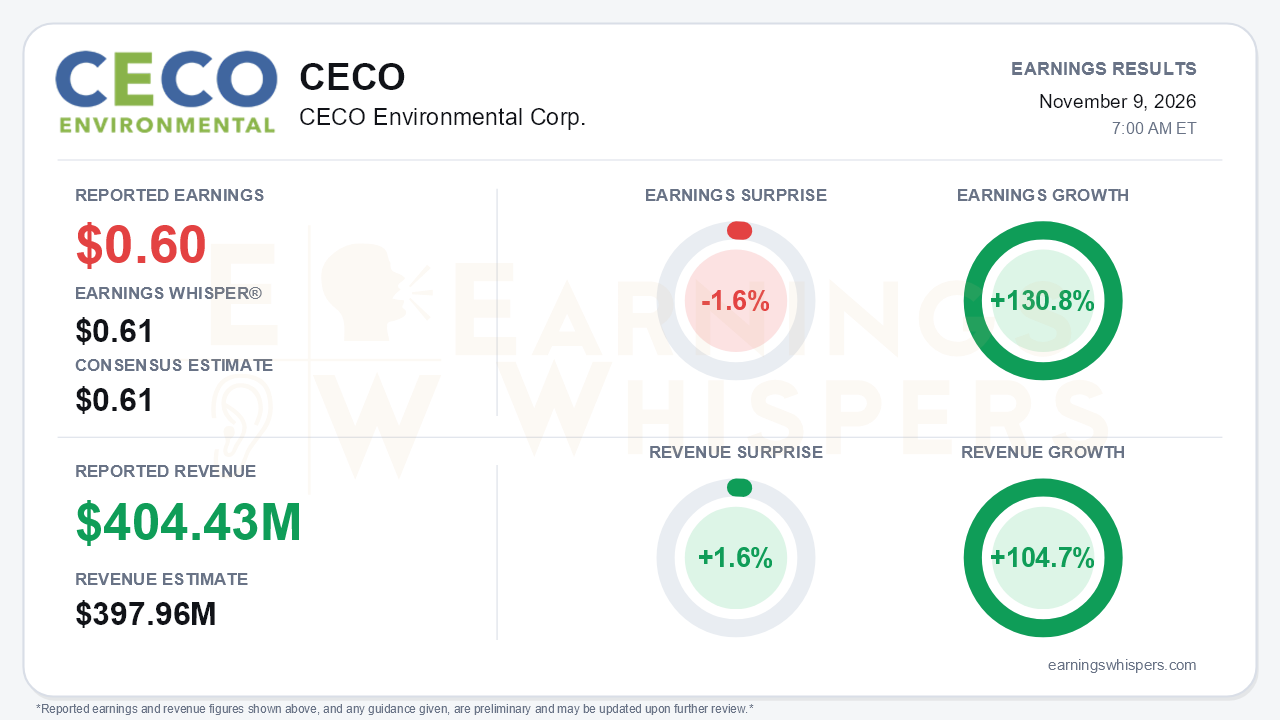
CECO Environmental's third quarter produced a technical miss wrapped inside a much larger story. Non-GAAP earnings of $0.60 per share fell a penny short of both the $0.61 consensus and the $0.61 Earnings Whisper number, a 1.6% shortfall. Revenue of $404.43 million beat the $397.96 million consensus by 1.6%. Year over year, earnings grew 130.8% and revenue grew 104.7%, both inflated by the June 1 acquisition of Thermon. The penny miss is close to irrelevant next to the introduction of a 2027 outlook of $2.1 billion to $2.3 billion in revenue and $475 million to $525 million in adjusted EBITDA. The central tension is that management is projecting a business more than twice its prior size, while the stock has been priced as if investors doubt the durability of the demand behind it.
The quality of the quarter deserves scrutiny on several fronts. On a GAAP basis, CECO lost $2.0 million, or $0.03 per share, versus a $0.04 profit a year ago. Three items drove that gap:
- $12.4 million of acquisition and integration expense;
- $15.3 million of amortization;
- a $16.7 million purchase-accounting inventory step-up that held GAAP gross margin to 32.2%, versus 36.3% on an adjusted basis.
Interest expense roughly doubled to $11.1 million. Dilution also matters: non-GAAP net income rose 269%, but per-share growth was far lower because diluted shares jumped from about 36.4 million to 58.6 million after the stock-funded deal.
The record $148.4 million of free cash flow was impressive but flattered by working capital. Billings in excess of costs, essentially customer advances, swelled by more than $256 million year to date. Management's own 2027 cash conversion guide of 50% to 60% of EBITDA, down from roughly 100% in 2026, signals that this cash tailwind will not repeat.
Beneath those caveats, the operating trajectory is clearly improving. Revenue climbed from $206 million in Q1 to $285 million in Q2 and $404 million in Q3. Legacy CECO grew about 30% organically, and Thermon grew at a double-digit rate. Adjusted EBITDA margin expanded to 17.3%, from 14.1% in Q2 and roughly 10% in Q1, while adjusted gross margin rose about 260 basis points sequentially.
Orders and pipeline tell a similar story:
- Orders of $778 million produced a book-to-bill of about 1.9x.
- Backlog reached $2.19 billion, a 13th consecutive quarterly increase.
- The pipeline exceeds $9 billion, and management expects it to top $10 billion.
Thermon synergies reached $22 million annualized, 55% of the $40 million target, and the first-year capture goal was lifted to at least 70% from 45% to 50%. Leverage fell to 2.0x from 2.7x at the deal's close.
The forward catalysts are substantial. The 2027 guide implies roughly a 22.7% EBITDA margin, above the approximately 20% framework management laid out in June. A first-ever 2028 preview calls for double-digit growth and about a 23.5% margin. Full-year 2026 orders guidance rose to at least $2.5 billion, and cash conversion guidance moved to about 100%.
Bears still have legitimate ammunition. Full-year 2026 revenue and EBITDA guidance were only maintained after repeated raises earlier in the year. Orders and book-to-bill eased from Q2's record $799 million and 2.8x. Management also disclosed two concentrations: data centers make up about 20% of backlog, and power generation roughly 60%. That is notable exposure at a time when investors are questioning the durability of AI infrastructure spending. Middle East water megaprojects remain delayed, and management cited inflation, post-election policy and geopolitics as outlook risks. The release also references material weaknesses still being remediated.
The market setup is far more complicated than a one-cent miss implies. Shares stood at $43.71 heading into the report, down 35.9% from the $68.20 opening after the August release. That is 38.7% below the 200-day moving average and 48.4% below the mid-August high of $84.77. The stock set a 52-week low of $37.15 on November 5 and entered the print only 17.7% above it. Gleason explicitly acknowledged headline- and election-driven equity volatility. Investor sentiment remained positive but weakened, slipping from 0.43 to 0.33. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP remain negative, reflecting the gap between the operating trajectory and the share price.
The bottom line is that CECO's quarter was better than its EPS miss suggests and messier than its adjusted figures suggest. The combined company is scaling quickly, margins are expanding, and the 2027 outlook resets the earnings base well above prior frameworks. However, the cash-flow peak is largely timing-driven, GAAP profitability remains buried under deal costs, and the backlog leans heavily on power and data-center demand the market is actively questioning. Management has a strong record against its guidance. Whether the stock recovers from its post-August collapse depends less on this quarter than on whether that concentrated demand converts on schedule.
Read our earnings preview for CECO Environmental Corp.: https://www.earningswhispers.com/article/CECO/22554
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-03 | |
| Nov-02 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-05 | |
| Jul-09 | |
| Jul-09 | |
| May-28 | |
| Apr-29 | |
| Apr-28 | |
| Apr-10 | |
| Mar-02 |
