Village Farms Beats On Sequential Profit Rebound, But Margin Compression And Stalled Export Growth Temper The Quarter
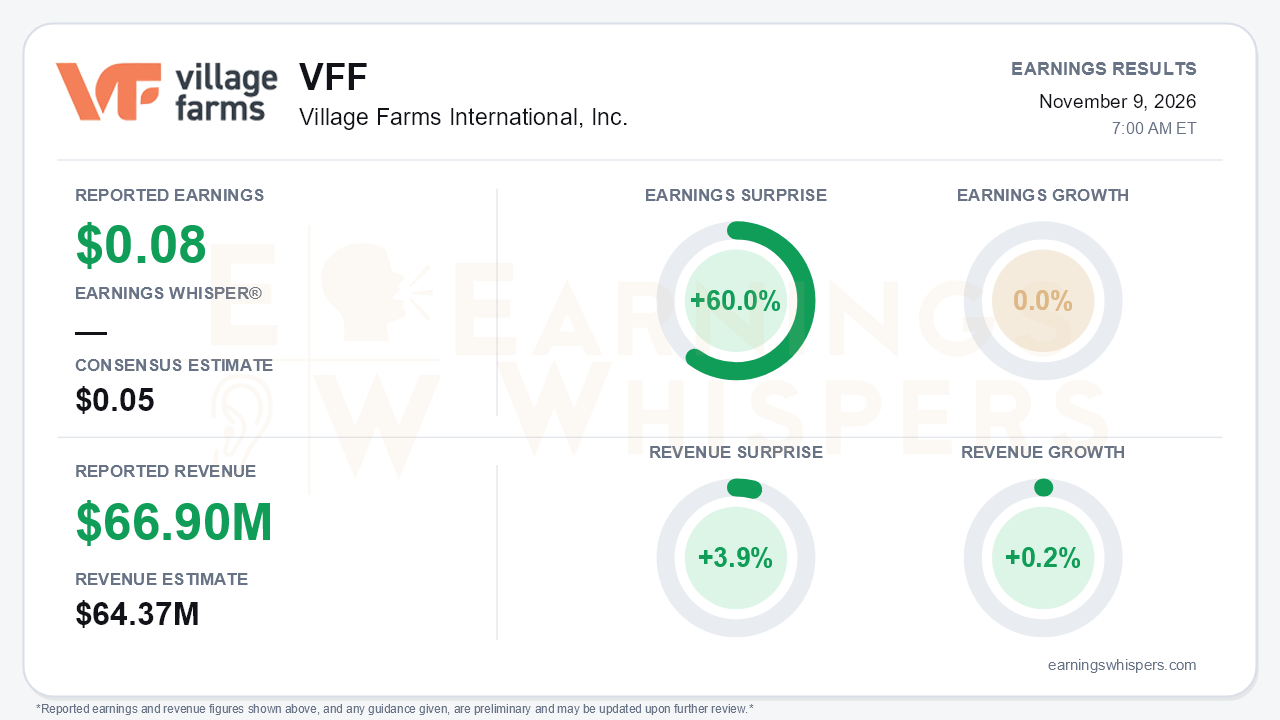
Village Farms International (NASDAQ: VFF) earned $0.08 per share in the third quarter, beating the $0.05 consensus by 60.0%. Revenue of $66.9 million topped the $64.37 million estimate by 3.9%. The beat is real, but the year-over-year picture is flat. EPS growth was 0.0% and revenue grew just 0.2%, a sharp slowdown from the 10% cannabis sales growth the company posted through the first nine months. The central tension is that the business is improving sequentially and building a larger capacity story while its core margins and near-term growth engines are under pressure. The sequential gains are clear: sales rose from $50.2 million in Q1 to $64 million in Q2 and $66.9 million in Q3, and net income climbed from $2.7 million to $7.2 million to $10.0 million.
The quality of the beat deserves scrutiny. Record cannabis sales of $55.0 million were up only 3% from a year ago, and cannabis gross margin fell to 48% from 51% in Q2 and 55% in the prior-year quarter. Consolidated gross margin slipped to roughly 44%. The culprit was Canadian spot trim pricing, which the call put down about 75% year over year. That collapse cut Canadian non-branded sales to $3.3 million from $7.3 million. Canadian branded sales also fell 6% to $25.3 million despite a 6% increase in average selling price, and management acknowledged it is missing its mid-single-digit growth goal there. Cannabis segment net income dropped 35% to $7.8 million, and cannabis adjusted EBITDA fell to $14.7 million from $20.2 million a year ago. Consolidated profit held up largely because corporate costs shrank sharply and the produce and energy businesses contributed more. Dilution is also a factor: the basic share count rose to 122.3 million from 113.0 million.
The international business, the centerpiece of the bull case, hit a pause. Exports rose 75% year over year to $20.8 million, but that was flat with Q2 after sequential gains of 60% in Q1 and 43% in Q2. Management attributed the stall to supply constraints, not demand. It said EU-GMP pricing is holding and demand exceeds supply, yet the international average net selling price fell 9% on a mix shift toward bulk flower. Planned entry into new European jurisdictions, promised for the second half of 2026 on earlier calls, has been pushed into 2027. Netherlands sales also dipped to $2.8 million from $3.3 million as propagation work temporarily reduced output.
The forward story is where the call turned more expansive:
- **Delta 2:** The expansion's full 40-metric-tonne run rate is now expected by mid-2027, earlier than the Q3 2027 timing cited last quarter.
- **Groningen:** The facility is fully planted and expected to ramp to maximum capacity in early 2027.
- **Delta 1:** The company exercised its right with Verdexa to convert 16 acres of Delta 1, roughly 50 tonnes of potential capacity. The release frames this as optionality during 2027, while the call indicated conversion timing has slipped toward 2028. Investors should treat it as a longer-dated option.
- **Texas:** Management is mobilizing plans for the 30-acre Monahans greenhouse on a roughly 12-month timeline tied to the regulatory and political pathway.
- **Regulatory tailwinds:** Management framed tighter GMP "washing" rules in the UK and Hessen, a single Canadian excise stamp, and competitor retreat from Canadian dry flower as favorable.
- **Trim recovery:** Management believes trim pricing troughed in Q3, citing new supply agreements at stronger contracted pricing beginning in October.
Bears have legitimate ammunition beyond margins. Nine-month operating cash flow from continuing operations was just $1.6 million, compared with $46.7 million a year earlier. Working capital absorbed $33 million, as receivables nearly doubled to $41.6 million on longer export payment terms and the company paid down a large tax liability. Q3 did deliver the promised improvement: consolidated operating cash flow reached $9.5 million and net cash rose to $41 million from $33 million. Management also flagged Q4 seasonality, with produce sales typically falling about 60% and European holiday orders slowing. A pending December 11 federal hemp ban clouds the U.S. CBD business, which generated only $2.8 million. The CFO role is now held on an interim basis.
Investor sentiment remained negative but improved, moving from -0.46 to -0.37 ahead of the report. Shares have been treated far better than sentiment implies. The stock entered the report at $2.88, up 24.1% from the open after the August release. That leaves it about 7.6% above its 200-day moving average, though roughly 10% below its late-September inter-earnings high of $3.20. Earnings Whispers trend readings are mostly positive, with sequential growth neutral, which fits a stock that has rallied on recovery expectations rather than on accelerating fundamentals.
The bottom line is that Village Farms delivered a clean headline beat and a credible sequential recovery in profit and cash, backed by a growing slate of capacity catalysts. However, flat year-over-year earnings, a seven-point drop in cannabis gross margin, stalled export growth and delayed European expansion mean the near-term story now depends on a trim-price rebound and new capacity arriving on schedule in 2027.
Read our earnings preview for Village Farms International, Inc.: https://www.earningswhispers.com/article/VFF/22598
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 11 hours | |
| Nov-06 | |
| Nov-02 | |
| Oct-22 | |
| Sep-15 | |
| Sep-14 | |
| Sep-10 | |
| Sep-08 | |
| Aug-17 | |
| Aug-12 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Jul-22 |
