Tonix Beats On Revenue But Misses On EPS As TONMYA Growth Slows Sharply And A Generic Challenge Arrives
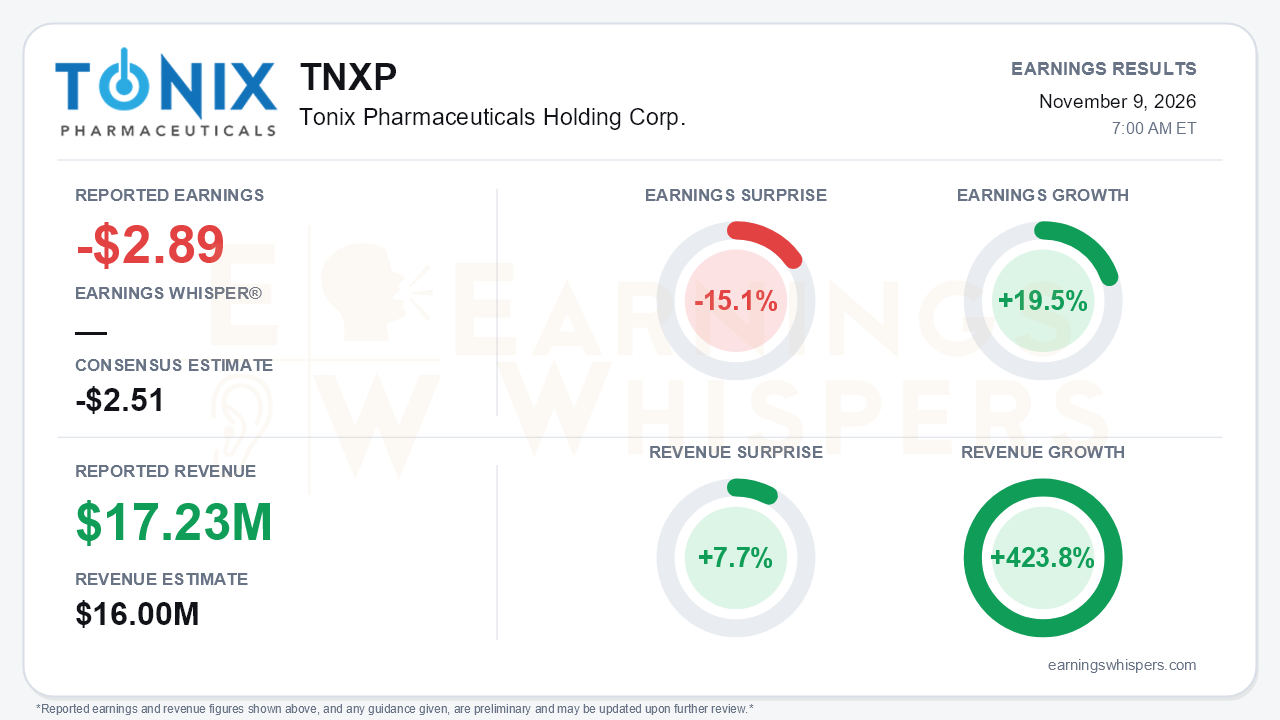
Tonix Pharmaceuticals posted a third-quarter loss of $2.89 per share, 15.1% worse than the -$2.51 consensus. Revenue of $17.23 million beat the $16.0 million estimate by 7.7% and grew 423.8% year over year as TONMYA, the company's fibromyalgia drug, finished its third full quarter on the market. The headline split matters less than the trajectory beneath it. TONMYA is still growing, but the launch curve flattened abruptly just as Tonix stepped up spending, and a Paragraph IV challenge from Dr. Reddy's added a new overhang. That is the central tension: commercial traction is real, but the market is now questioning both how fast it compounds and how long it lasts.
The quality of the quarter deserves scrutiny. TONMYA net sales reached about $15 million, up 37% from the second quarter. That is a solid sequential gain in isolation, but it compares with 197% growth in Q2. Total prescriptions rose 28% to 16,375, versus 100% growth the prior quarter. New prescriptions grew 17% (down from 36%) and refills grew 56% (down from 207%). Management also acknowledged that more favorable than expected gross-to-net helped revenue, and it still expects gross-to-net to fluctuate, so part of the beat may not recur cleanly. The migraine franchise slipped to $2.2 million from $2.5 million in Q2. The 19.5% EPS improvement reflects a larger share count, not a smaller loss. Net loss widened to $53.3 million from $32.0 million a year ago, while weighted shares roughly doubled to 18.4 million. Operating expenses grew far faster than revenue. SG&A rose to $45.6 million from $36 million in Q2, and R&D more than doubled year over year to $25.8 million, with $9.8 million of that increase tied to manufacturing.
The call preserved a credible growth story built on access and reach. Covered lives expanded to roughly 53% of the U.S. total from about 43% in Q2, helped by two managed Medicare agreements adding roughly 30 million lives, plus Medicaid access in nearly every state. On September 1, Tonix added 50 reps to reach about 150. Management says this lifted reach from roughly 40% to about 70% of its 25,000 target prescribers. It cited step-ups in total prescriptions, new prescriptions, refills and writers that it says are continuing into Q4. Two other details suggest monetization is improving:
- Bridge prescriptions, which generate no immediate revenue, are declining as covered paid scripts rise.
- A shift toward 60-count bottles is lifting average price.
Bears have legitimate ammunition on durability and funding. Dr. Reddy's filed an ANDA with a Paragraph IV certification against TONMYA. Core patents run to 2034, and Hatch-Waxman litigation typically brings a 30-month stay, but the challenge puts a question mark on the long-term value of the company's only meaningful growth asset. The balance sheet is the more immediate issue. Cash fell to $162.8 million from $176.2 million at the end of June. Operating cash burn for nine months was $125.6 million, more than double the prior-year pace. The runway now extends only into early Q3 2027, and management lengthened it from early Q2 2027 by issuing equity, so further dilution looks likely. Management offered no enrollment or topline timing for the HORIZON depression study, and TNX-1300 is at an impasse with the FDA. The nearer pipeline catalysts are slated for Q1 2027: the Lyme disease antibody TNX-4800 Phase 2 trial, pending final protocol agreement, and an investigator-initiated kidney transplant study of TNX-1500 at Massachusetts General Hospital. Management also referenced ongoing partnering discussions.
The market had turned decisively against the stock before the print. Shares opened at $11.62 after the August report, peaked at $14.50 on August 31, then fell 59.2% to $4.74 by November 6. That leaves them about 61% below the 200-day moving average and barely above a fresh 52-week low of $4.55 set on November 5. Investor sentiment swung from a solidly positive 0.52 to a slightly negative -0.10, a large reversal that reflects how much the growth deceleration and patent challenge reset expectations. The Earnings Whispers price and AVWAP trends are negative, while sequential growth remains positive, which matches a business still expanding against a sharply deteriorating stock. At roughly 19.4 million shares, the equity was valued below the company's quarter-end cash. That signals deep skepticism about burn and dilution rather than about whether TONMYA sells.
The bottom line is that Tonix delivered a revenue beat and continued TONMYA growth, but the quarter changed the narrative from launch acceleration to launch normalization. Spending, dilution and a generic challenge are now competing with that growth. The expanded sales force and broader payer coverage give management a plausible path to re-accelerate prescriptions in Q4. With cash runway measured in quarters and the stock trading near its lows, investors will need visible scripts and revenue growth from the 150-rep force before the financing and patent overhangs lose their grip.
Read our earnings preview for Tonix Pharmaceuticals Holding Corp.: https://www.earningswhispers.com/article/TNXP/22595
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-04 | |
| Nov-02 | |
| Nov-02 | |
| Oct-27 | |
| Oct-26 | |
| Oct-19 | |
| Oct-15 | |
| Sep-22 | |
| Sep-08 | |
| Sep-02 | |
| Aug-10 | |
| Aug-10 | |
| Aug-05 |
