Ferguson's Organic Growth Accelerates To 7% And Guidance Rises Again, But Margins, Leverage And Cash Flow Complicate The Beat
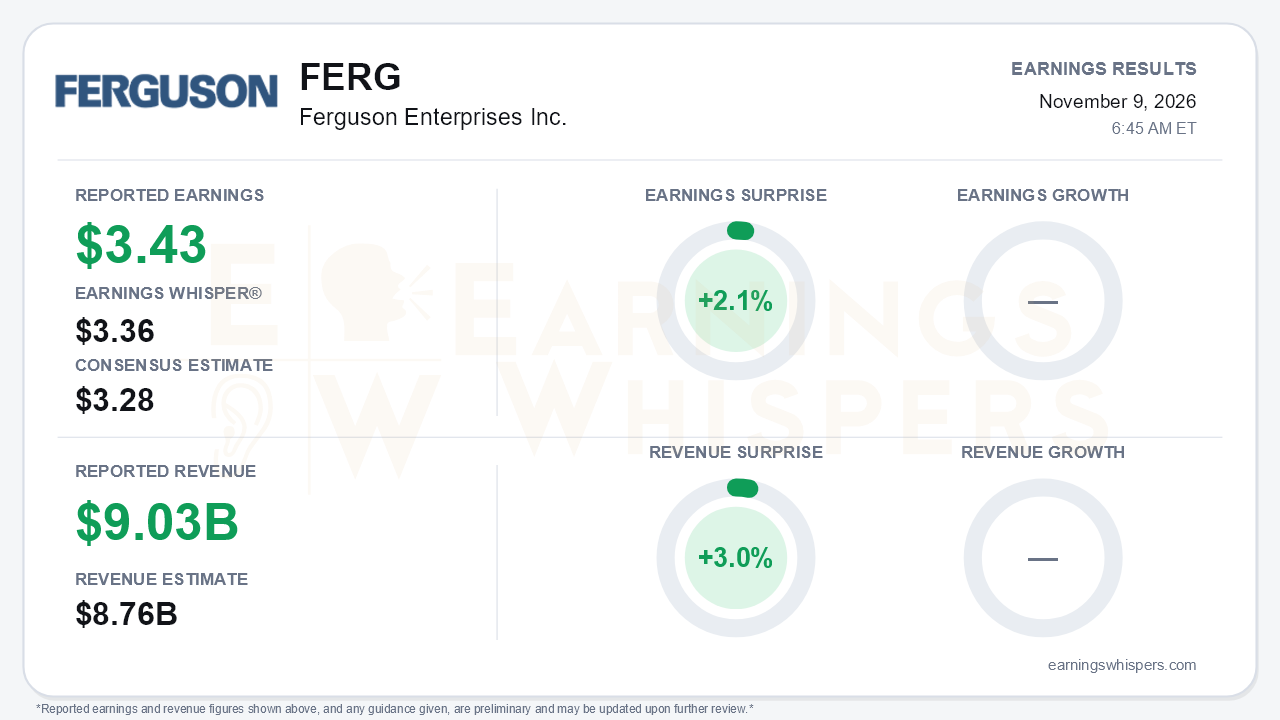
Ferguson Enterprises delivered the kind of top-line acceleration that distribution bulls have been waiting for. Adjusted earnings of $3.43 per share beat the $3.28 consensus and the $3.36 Earnings Whisper number, a 2.1% beat. Revenue of $9.026 billion topped the $8.76 billion consensus by 3.0%. The more important number is organic growth of 7.0%, nearly double the 3.8% pace in the second quarter and up from 4.2% in the first quarter. Management also raised full-year sales guidance for the second straight quarter, to roughly 7% growth from mid-single digits. That trajectory is the central takeaway. The tension is that the acceleration came alongside softer gross margins, a more leveraged balance sheet and weaker cash conversion.
The quality of the beat deserves a closer look. Adjusted EPS rose 7.9%, driven by an 8.9% increase in adjusted operating profit to $962 million. GAAP diluted EPS, however, fell 4.9% to $3.08. The company attributed that decline mainly to tax benefits in the year-ago quarter that did not recur. The adjusted figure also excludes $25 million of FloWorks acquisition and integration costs, a higher $50 million of acquired-intangible amortization and a $9 million loss on a disposal. Gross margin slipped to 30.9%, down 40 basis points. That decline was wider than the 20-basis-point slip in the second quarter, although management blamed a year-ago comparison inflated by the timing of supplier price increases. Adjusted operating margin held flat at 10.7%. In other words, cost leverage, not pricing power, protected profitability. Acquisitions also contributed 2.7 points of the 9.5% sales growth.
Beneath the headline, the mix of growth improved broadly:
- **Non-residential:** U.S. non-residential sales rose 15%, up from 8% in the second quarter.
- **Industrial:** The industrial customer group grew 55%, including 32% organically, with backlog building into 2027.
- **HVAC:** Growth reached 15%, up from 11% in the second quarter and a 6% decline in the first.
- **Residential:** U.S. residential sales grew 6%, up from 2% and then -1% in the prior two quarters, despite weak new construction and soft repair and remodel activity.
Price inflation firmed to low-to-mid single digits as copper and steel strengthened. October trends reportedly continued strong, implying fourth-quarter growth in the high single digits to low double digits. Not every line improved, though:
- Waterworks slowed to 5% from 14% in the first quarter.
- Fire and fabrication fell 8% amid a vendor transition.
- Canadian sales declined 4.5%.
The forward story rests heavily on FloWorks. The deal closed August 31 and brings roughly $1 billion of revenue at a $1.6 billion enterprise value, with about $45 million of targeted synergies. Management said it adds about 3 points to full-year growth and expands the addressable market to $400 billion. Ferguson has now completed 11 acquisitions this year with about $1.5 billion of annualized sales. The bill for that expansion is visible. Net debt to adjusted EBITDA rose to 1.7x from 1.0x a year ago. Buybacks are paused until leverage trends back toward the low end of the 1-2x target range, likely sometime in 2027. Interest expense guidance rose to about $235 million from $200 million. Year-to-date operating cash flow fell to $1.47 billion from $1.88 billion as receivables and inventory built.
Bears also have legitimate forward-looking ammunition. Management grew more cautious on new residential construction for 2027 and expects pressure to spread beyond Waterworks. Analysts pressed on data-center risk from possible state moratoria and the loss of incentives, which management called too early to judge. That matters because large capital projects are now powering the growth narrative. The guidance framing also warrants caution: the raise appears to bring the outlook closer to Street estimates rather than decisively above them. The adjusted operating margin range moved only to 9.6-9.8% from 9.5-9.8%.
The market setup is more complicated than the surprise implies. Investor sentiment collapsed from 0.40 to 0.03 heading into the report, essentially erasing a solidly positive reading and leaving expectations near neutral. The shares had fallen 11.0% since opening at $262.72 after the August report, closing at $233.70. They hit a 52-week low of $212.13 on September 21 and have since recovered about 10%. Entering the release, the stock sat 1.5% below its 200-day moving average and 12.7% below the quarter's high. That rebound has some support in the Earnings Whispers momentum and AVWAP trend readings, which have turned positive.
The bottom line is that Ferguson produced a genuinely better operating quarter. Organic growth accelerated sharply, end-market breadth improved and guidance rose again, and those results arrived when investors had grown markedly less enthusiastic. Still, the margin profile is static and gross margin is eroding. Acquisitions are flattering growth, and the balance sheet is being used to buy it, at the cost of buybacks and cash flow. Sustaining the rerating case will require industrial and non-residential strength to outrun a weakening residential outlook and unresolved data-center policy risk.
Read our earnings preview for Ferguson Enterprises Inc.: https://www.earningswhispers.com/article/FERG/22563
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-04 | |
| Nov-02 | |
| Oct-26 | |
| Sep-22 | |
| Sep-01 | |
| Aug-14 | |
| Aug-11 | |
| Aug-10 | |
| Aug-07 |
