Select Water Solutions Misses By A Penny While Pilot Deal Accelerates Infrastructure Growth And Raises The Capital Bill
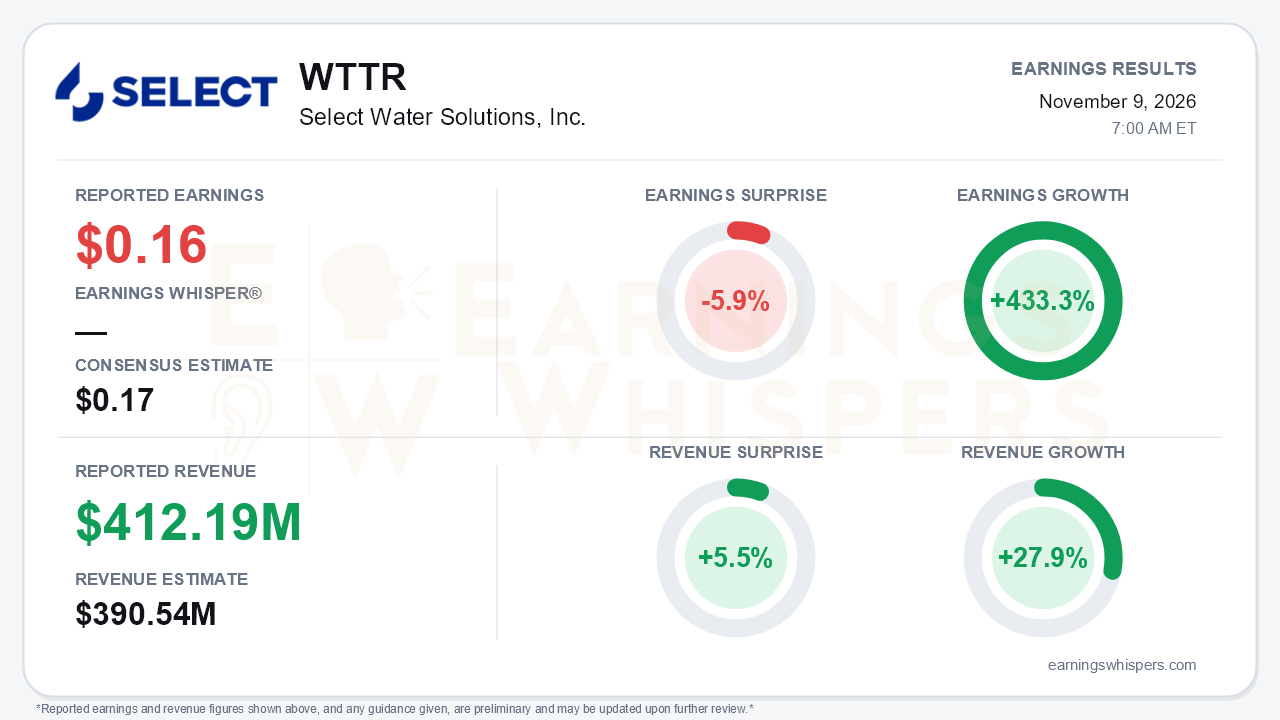
Select Water Solutions (NYSE: WTTR) reported third-quarter earnings of $0.16 per share, a penny short of the $0.17 consensus and a 5.9% miss. Revenue of $412.19 million beat expectations by 5.5%. Year over year the comparison is flattering: earnings grew 433.3% from a near-breakeven $0.03 a year ago, and revenue rose 27.9%. Sequentially, though, the picture is flat. Revenue rose about 4% from $396 million in the second quarter, while net income barely moved ($22.9 million versus $22.6 million) and per-share earnings slipped from $0.17. The central tension is that the operating business, especially Water Infrastructure, is accelerating while the per-share and free-cash-flow story is being pushed further out by deal costs, a rising capex bill, and a heavier balance sheet.
The quality of the quarter deserves scrutiny in both directions. GAAP results absorbed $7.4 million of transaction costs, which lifted SG&A to $53.6 million from $41.2 million and cut operating income to $26.9 million from $34.3 million. Pre-tax income was cushioned by a $4.2 million gain on deconsolidating Peak Rentals and roughly $4.8 million of non-recurring gains tied to a historical insurance claim. A higher tax bill and a larger Class A share count also weighed on the per-share result. Adjusted EBITDA of $93.5 million landed at the high end of guidance but was essentially flat with the second quarter's $92.7 million. Free cash flow turned negative at -$3.6 million as capital spending climbed to $89.5 million.
Beneath the headline, Water Infrastructure carried the quarter. Produced water volumes reached 1.7 million barrels per day, up from 1.5 million in the second quarter and 1.4 million in the first. Segment revenue hit a record $110 million, up 40% year over year, with gross margin before D&A at 57.2%. That margin is down modestly from 58.3% but well above last year's 53.1%. Management now expects 2026 base infrastructure growth above the high end of its 25-30% range before any Pilot contribution. That outlook has been raised every quarter this year.
Water Services grew 7% sequentially against a guided flat quarter, and its margin improved to 23.8%. Chemical Technologies was the weak spot. Revenue fell to $90 million from $96 million, and margin slid to 17.8%, below the 20-21% management had guided on the prior call. Fourth-quarter chemicals revenue is guided down to $75-80 million.
The forward story is now dominated by the Pilot Water acquisition. Pilot carries a 2026 outlook of $100-110 million of adjusted EBITDA and a 2027 outlook of $120-130 million. It also brings roughly 900,000 barrels per day of permitted disposal capacity. Management said that capacity closes the firm-disposal gap it had cited as the main reason for lost bids, and it described strong inbound customer interest. An August Northern Delaware expansion added more than 250,000 dedicated acres under a 12-year extension with a rate increase. Fourth-quarter EBITDA is guided to $95-100 million, which includes only a partial Pilot contribution and is net of losing the Peak Rentals business (roughly $7-10 million of quarterly EBITDA).
Bears have legitimate ammunition on the cost side:
- Net capex guidance rose for a third straight time, to $300-310 million from an original $175-225 million.
- Maintenance capex resets to $80-90 million from $50-60 million.
- 2027 capex is now framed as similar to 2026, pushing out the free-cash-flow inflection investors had been promised for next year.
- The $900 million of new senior notes (7.625% coupon per the release; the call cited 7.58%) lifts pro forma leverage to about 2x and roughly doubles quarterly interest expense to $15-17 million.
- Fourth-quarter infrastructure margins are guided down to 52-56% on integration costs.
- Management newly raised potential Texas disposal regulation as a risk, while pointing to change-in-law pass-through provisions in its contracts.
The market has been skeptical. Shares opened at $20.00 after the August report and spiked to a 52-week high of $22.55 that same day. They have since fallen 19.1% to $16.18, sit 7.4% below the 200-day moving average, and trade just 4.9% above the inter-earnings low of $15.43 set on November 5. Investor sentiment slipped from roughly neutral (-0.04) to modestly negative (-0.11). That is a meaningful but not dramatic deterioration, and it suggests investors entered the report focused more on capital intensity than on volume growth.
The bottom line is that Select delivered a strategically important quarter with an unimpressive earnings print. Infrastructure volumes, contracted acreage, and the Pilot deal give the company a credible path to materially higher EBITDA. However, the EPS miss, flat sequential profitability, a softening chemicals business, and a capex budget that keeps expanding explain why the stock has been sold toward its lows. Investors now need evidence that Pilot's EBITDA arrives on schedule and that spending eventually stops rising faster than earnings.
Read our earnings preview for Select Water Solutions, Inc.: https://www.earningswhispers.com/article/WTTR/22601
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Nov-02 | |
| Oct-29 | |
| Oct-27 | |
| Oct-14 | |
| Oct-13 | |
| Sep-25 | |
| Sep-25 | |
| Sep-24 | |
| Sep-24 | |
| Sep-03 | |
| Aug-18 | |
| Aug-05 |
