OPAL Fuels Posts Best EBITDA Quarter Of 2026, But Production Slippage And A Deep Revenue Miss Push The Outlook To The Low End
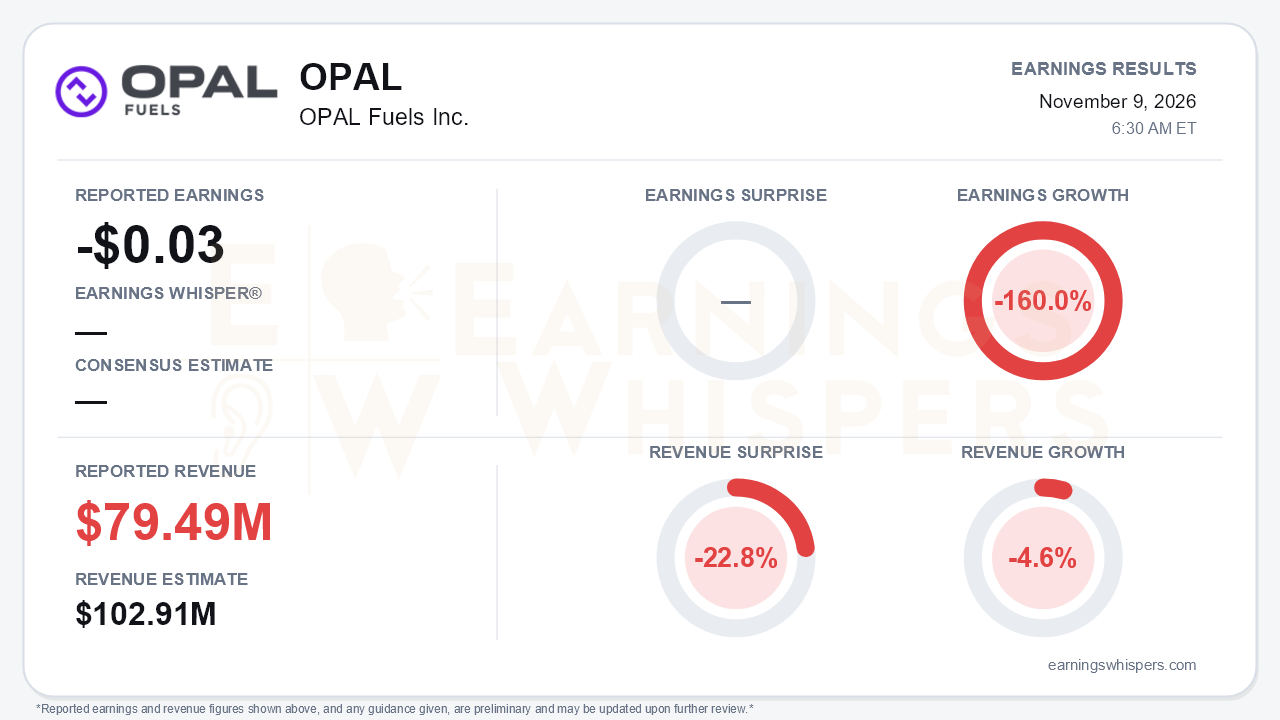
OPAL Fuels delivered two different quarters at once. Its preferred profitability measure, Adjusted EBITDA, rose 32% year over year to $26.7 million, its strongest result of 2026 after $16.7 million in Q1 and $23.1 million in Q2. The top line and the full-year outlook point the other way. Revenue of $79.49 million fell 4.6% from a year ago and missed the $102.91 million consensus by 22.8%. That reverses Q2's 4% growth. The Class A loss of $0.03 per share represents a 160.0% year-over-year earnings decline on Earnings Whispers' normalized basis. Note that the release's own restated prior-year figure was also a $0.03 loss. Prior periods were recast for a voluntary accounting change in how tax credits are recorded, which complicates the year-ago comparison. Management also conceded that 2026 RNG production will land below guidance and that EBITDA will come in at the low end of its range. That is the central tension.
The quality of the EBITDA beat deserves scrutiny. Under the new policy, 45Z clean fuel production credits are booked as a reduction to cost of sales rather than as a tax benefit. RNG Fuel cost of sales fell to $9.1 million from $13.5 million even though segment revenue was essentially flat at $22.5 million. Segment EBITDA, meanwhile, jumped 35% to $20.3 million. Credits and lower corporate costs therefore explain much of the improvement, more than volume does. Corporate costs fell to a $7.9 million drag from $9.2 million.
GAAP results show a similar split. Consolidated net income swung to a $1.7 million profit from a $1.9 million loss. However, accretion on redeemable preferred interests rose to $6.5 million from $2.6 million, leaving common holders with a $942,000 loss. Interest expense also climbed to $8.9 million from $7.2 million. Elsewhere, Renewable Power EBITDA fell to $1.4 million from $3.3 million, and OPAL's share of equity-method EBITDA slipped to $2.9 million. That decline came even as revenue at those investees rose 35%; their revenue is excluded from consolidated sales.
Operations remain the weak link. Production reached 1.34 million MMBtu, up 7% sequentially. Year-over-year growth slowed to 5%, from 8% in Q2 and 9% in Q1. Utilization of inlet gas fell to 75.0% from 77.1%, well below the company's 80% to 90% target. Inlet design capacity utilization dropped to 76.0% from 79.5%. Co-CEO Jonathan Maurer acknowledged the operational fixes "took longer to implement."
The guidance path has steadily eroded:
- **RNG production:** the 5.4 to 5.8 million MMBtu range was reaffirmed earlier in the year, became "lower end" in Q2, and is now "modestly below."
- **Adjusted EBITDA:** the $95 to $110 million outlook moved from the full range to the low end, implying Q4 roughly in line with Q3.
The downstream story strengthened, and it is what kept the call credible. Fuel Station Services EBITDA rose 18% to $13.0 million, up from $9.2 million in Q1, on higher volumes and margins. RNG dispensed grew 7%. Management's tone on fleet conversions has escalated through the year, from a possible inflection, to the "logjam breaking," to now expecting "strong acceleration." It cited $6 diesel and positive feedback on Cummins' X15N engine. Capital is tilting toward stations accordingly. Three RNG projects totaling roughly 2.0 million MMBtu of annual design capacity are slated to come online through 2027. Management described double-digit 2027 EBITDA growth as "not out of the question," which is a hedged framing rather than guidance.
Bears have legitimate ammunition:
- **RIN pricing:** D3 RINs have sagged toward the D4 floor. The quarter-end price was $2.26, versus a $2.47 average realized price during the quarter, reversing the "strengthening RIN environment" cited in Q1.
- **Liquidity:** it fell to $122 million from $162.2 million in Q2 and $233 million in Q1, as $71 million of year-to-date capex was funded partly with new debt and preferred capital.
- **Near-term pressures:** management flagged winter outage risk and higher Q4 SG&A.
- **Leadership:** Maurer will retire March 31, 2027.
The market setup offers limited new information. Investor sentiment was negative at -0.245 heading into the prior report, and no updated reading is available. Shares opened at $2.09 after the August release, essentially on top of the $2.10 200-day moving average. That suggests a stock trading in a holding pattern, priced with considerable skepticism, rather than one discounting a recovery.
The bottom line is that OPAL's EBITDA growth is real but leans heavily on 45Z credits and cost cuts, while the core production engine keeps under-delivering against its own targets. The fleet-conversion narrative and the 2027 project pipeline give the bull case substance. Until utilization moves toward the 80% to 90% target and RIN pricing stabilizes, investors are likely to discount management's 2027 aspirations.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Sep-29 | |
| Sep-16 | |
| Aug-26 | |
| Aug-18 | |
| Aug-13 | |
| Aug-10 | |
| Aug-10 | |
| Jul-30 | |
| Jul-27 |
