Kodiak Gas Services Beats And Nudges Guidance Higher, But A Delayed Power Ramp Keeps The Stock Near Its Lows
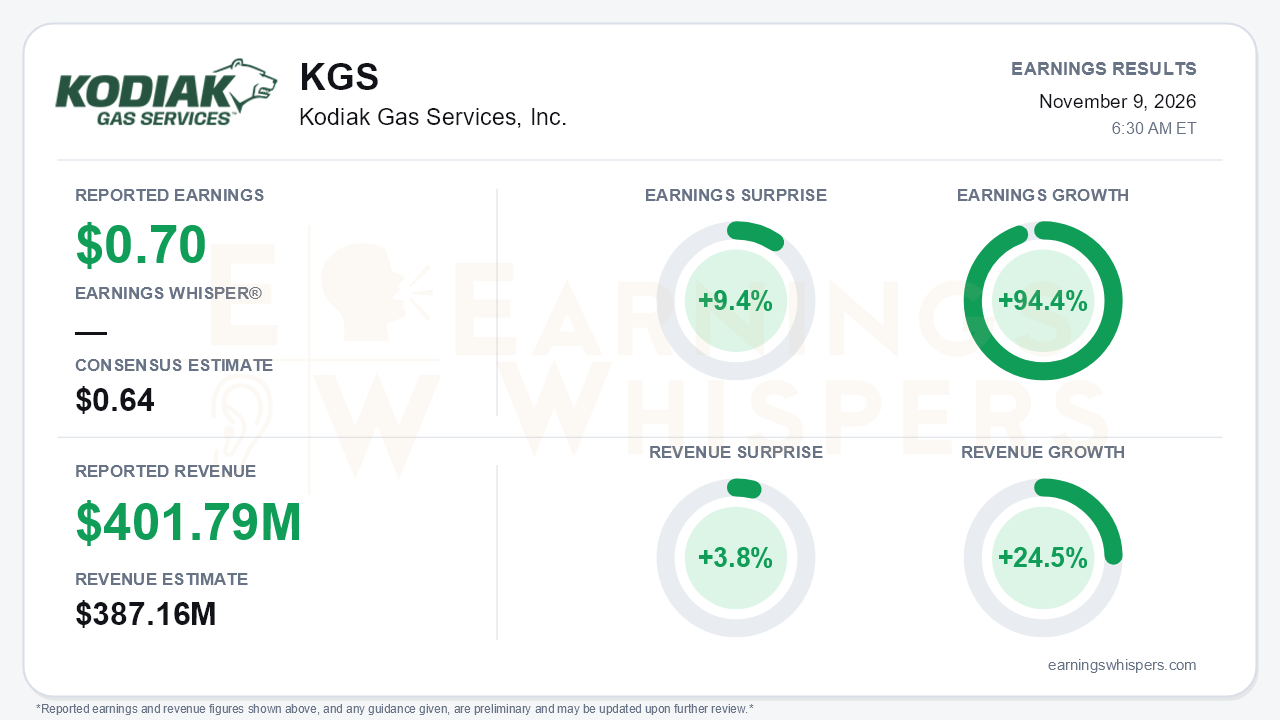
Kodiak Gas Services delivered the kind of quarter that usually lifts a stock. The market has spent three months pricing in the opposite. Third-quarter earnings of $0.70 per share beat the $0.64 consensus by 9.4% and grew 94.4% from a year ago. Revenue of $401.79 million topped expectations by 3.8% and rose 24.5%. Adjusted EBITDA reached a record $224.5 million, and full-year EBITDA and discretionary cash flow guidance moved up again. The central tension is timing. The core compression business keeps getting more profitable, but the power business that investors were counting on for the next leg of growth is arriving later than promised.
The quality of the beat holds up well. GAAP and adjusted net income were identical at $71.5 million, with no transaction or one-time add-backs flattering the result. That contrasts with a year-ago GAAP loss of $0.17 per share, which was weighed down by a sales tax reserve and a loss on a business disposal. Lower interest expense also helped, at $47.4 million versus $56.4 million a year earlier. The per-share gains came despite a diluted share count that rose to 102.2 million from 87.1 million after the equity raised to fund the DPS acquisition.
Growth accelerated on the surface. Revenue growth improved to roughly 25% from about 21% in the second quarter, and EBITDA growth to about 29% from 22%. Investors should recognize that much of that acceleration is acquired. Compression Infrastructure revenue rose a more modest 7.2% year over year and only about 1% sequentially, and revenue per horsepower slipped to $23.51 from $23.80. Management attributed the decline to a lease buyout and a contract termination.
The compression franchise remains exceptionally tight:
- Utilization reached 98.3%.
- Average horsepower per unit topped 1,000.
- Adjusted gross margin held at 70% for a third straight quarter, despite roughly a 30% rise in lube oil costs since the first quarter and mid-single-digit equipment inflation.
- Lube oil pricing is now locked for most of 2027.
- Contracting extends into 2028.
- Management said it leans toward exceeding its 5.3 million horsepower 2030 target.
Power Infrastructure was the quarter's standout. Revenue climbed 27.6% sequentially to $42.0 million, and adjusted gross margin jumped to 75.2% from 64.5%, well above the original 60%-70% range. Management credited higher genset pricing and longer time on location. The West Texas data center project, about 76 megawatts of behind-the-meter power, has moved into site work, with energization targeted by the end of the first quarter of 2027. Management reaffirmed project economics of high-teens returns, five-to-six-year paybacks and 10-to-15-year contract tenors.
The delivery schedule is where bears have legitimate ammunition:
- New 2026 power additions were cut to 29 megawatts, from roughly 50 megawatts expected last quarter and 61 megawatts in the first quarter.
- Power growth capex was lowered to $350 million-$400 million.
- Baker Hughes turbines are not expected until late 2027, pushing the significant power ramp to 2028. Kodiak remains tied to a roughly $1.4 billion turbine commitment that management conceded would "leave a mark" to exit.
- No new long-term power contract was announced beyond West Texas.
- Analysts repeatedly pressed on post-midterm political uncertainty in Texas, where most of the power funnel sits, and management's answers on project geography and M&A were hedged.
- Fourth-quarter power revenue and margins will dip as equipment is redeployed to West Texas, and Other Services faces a lull after a large low-margin project ends.
The raised guidance therefore deserves scrutiny. The $5 million EBITDA midpoint increase to $850 million is modest. Combined with the first three quarters, it implies fourth-quarter EBITDA somewhat below the third-quarter record.
Cash flow tells a similar story of heavy investment. Discretionary cash flow of $158.5 million rose 35.9% year over year but eased sequentially. Free cash flow was negative $28.1 million, an improvement from negative $87.5 million in the second quarter but still in the red. Leverage stands at 3.1x, with $1.7 billion of liquidity. The 4.1% dividend increase to $0.51 signals confidence, though spending continues to outrun internally generated cash.
The market setup is more complicated than the surprise implies. Shares have fallen 22.7% since opening at $53.90 after the August report and sat at $41.67 heading into the release. That leaves them nearly 30% below the 200-day moving average and 37% below the August 18 inter-earnings high of $66.43. The stock set its inter-earnings low of $38.21 on November 5, just days before the report. The Earnings Whispers price and AVWAP trend readings remain negative, while momentum is positive, reflecting improving fundamentals against a damaged chart. Investor sentiment improved slightly, from 0.14 to 0.17. That is a mild shift that remains only modestly positive, not a wholesale change in conviction.
The bottom line is that Kodiak's operating engine is performing at or near its best, with record EBITDA, a clean GAAP beat, 70% compression margins and surprisingly strong power economics. What changed is the calendar, not the quality of the business. The power growth story now leans on 2028, carries Texas political risk and still has only one signed data center contract. The selloff suggests investors had already discounted much of that delay. Rebuilding confidence will likely require new long-term power contracts rather than further compression beats.
Read our earnings preview for Kodiak Gas Services, Inc.: https://www.earningswhispers.com/article/KGS/22570
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-04 | |
| Nov-02 | |
| Oct-27 | |
| Oct-21 | |
| Oct-13 | |
| Oct-08 | |
| Sep-21 | |
| Aug-17 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 |
