Radiant Logistics Doubles EPS As EBITDA Growth Accelerates, But Part Of The Lift Comes From Tailwinds That May Fade
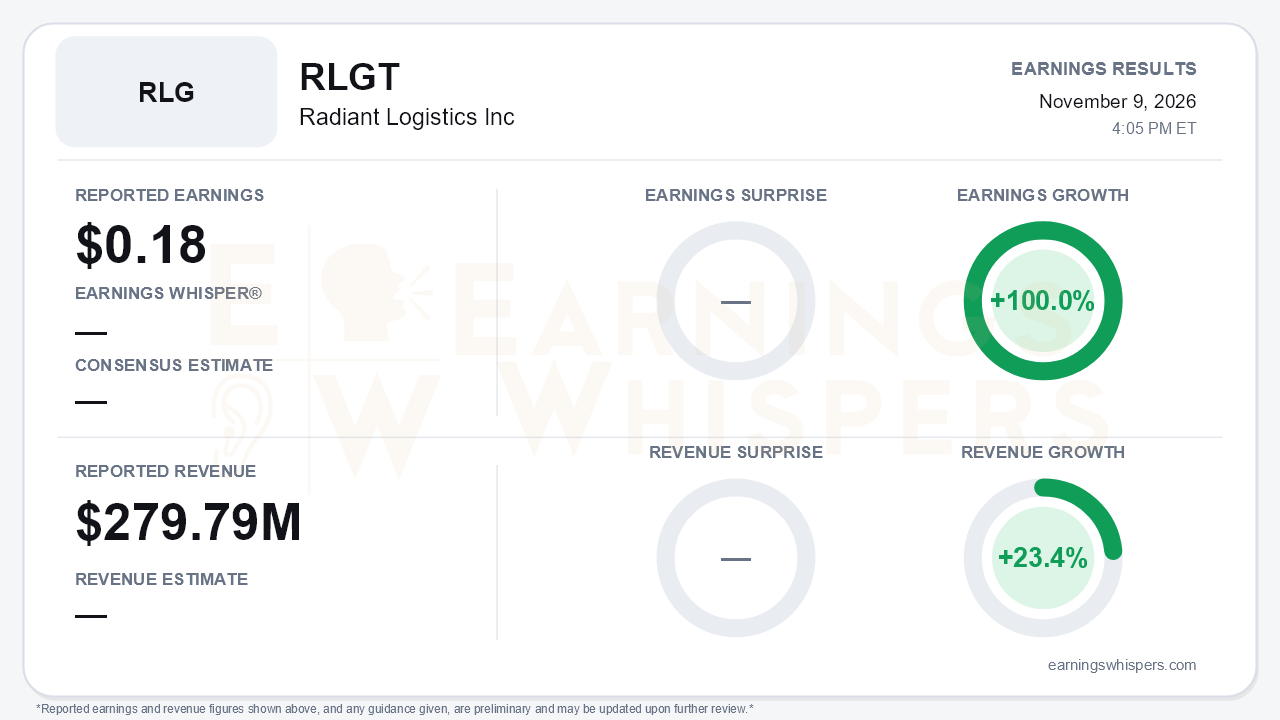
Radiant Logistics opened fiscal 2027 with its strongest year-over-year comparison in some time. Adjusted EPS was $0.18, up 100.0% from a year ago, on revenue of $279.79 million, up 23.4%. No consensus estimate was available, so this quarter is better judged on trajectory than on surprise, and the trajectory is clearly improving. Revenue growth has gone from flat in fiscal Q3 2026 ($214.1 million) to 18.5% in Q4 ($261.4 million) and now 23.4%. Adjusted EBITDA has moved from a 17.5% decline ($7.8 million) to 31.6% growth ($10.4 million) and now 79% growth ($12.2 million). On a GAAP basis, net income attributable to Radiant rose to $6.1 million, or $0.13 per share, from $1.3 million, or $0.03. Operating income roughly quadrupled to $8.3 million.
The central tension is the quality of that acceleration, which deserves scrutiny. Revenue outran profit at the gross line. Adjusted gross profit rose 15.3% to $68.6 million, and adjusted gross margin slipped to 24.5% from 26.2%. That is consistent with higher purchased transportation costs in a firmer rate environment. Most of the bottom-line leverage came from below the gross line:
- **SG&A:** it fell to $10.0 million from $12.1 million, helped by transportation management system consolidation.
- **Credit loss:** the prior-year period included a $1.3 million First Brands credit loss that did not recur.
- **Disaster relief:** the call disclosed that typhoon-related air charters added roughly $1 million to $2 million to EBITDA.
Adjust for both one-off items and underlying EBITDA growth is still solid, but well short of 79%. The 630-basis-point jump in adjusted EBITDA margin, to 17.7%, overstates how much the core earnings engine improved.
The underlying story is still credibly better, though. U.S. adjusted EBITDA more than doubled, with strength in international airfreight, intermodal and over-the-road brokerage. Management's description of the domestic freight market has firmed over three calls. In Q3 it was "approaching inflection." In Q4 it was "one month of good news." Now management points to:
- contract truckload rates meaningfully higher year over year;
- tender rejections above balanced-market levels;
- longer-haul freight shifting toward intermodal, which favors the bimodal Radiant Road & Rail offering.
Internationally, ocean rates have gone from "miserable" to holding at elevated levels amid the Strait of Hormuz and Red Sea disruptions. Tariff complexity, IEEPA refund filings and the U.S.-Canada tariff escalation are driving customs brokerage demand. Navegate adoption is also broadening: there are now more than 150 active customers, and one enterprise user has over 1,500 vendors booking 7,500 shipments, up from 1,400-plus vendors last quarter.
The forward-looking pivot may matter more than the quarter itself. Radiant extended its $200 million revolver to 2031 and raised the acquisition accordion to $100 million. It ended September with $25.0 million drawn against $27.8 million of cash, leaving no net debt. Management signaled appetite for larger acquisitions, and its closing remarks emphasized bigger transactions rather than buybacks. The October 1 purchase of Whitacre Logistics' Dallas intermodal and brokerage operations seeds the new independent agent program at Road & Rail. That program extends Radiant's forwarding-agent model into truck brokerage and offers a new organic growth channel. Management also cited data center exposure across more than 10 accounts.
Bears have legitimate ammunition. A meaningful share of the international upside rests on disruption. Management acknowledged that ocean and air margins would compress if the Hormuz and Red Sea routes normalize. Elevated fuel and rerouting costs are already pressuring those margins, and spot rates remain volatile. Management also flagged three other concerns:
- the policy shift after the Democratic congressional sweep could eventually reduce the tariff-complexity tailwind for customs brokerage;
- seasonality has become muted, so the usual sequential lift into fiscal Q2 may be modest;
- charter timing makes results lumpy.
The next quarter faces a tougher comparison: fiscal Q2 2026 adjusted EBITDA was $11.8 million. The 79% growth rate will not be repeatable. No formal guidance was provided.
Market context is limited this cycle. Shares opened at $9.45 after the September report, above a 200-day moving average now at $8.29. That suggests the stock entered this report with some recovery already priced in rather than from a depressed base. Sentiment readings and current price data were not available to gauge how investors received the release.
The bottom line is that Radiant delivered a genuine third consecutive quarter of acceleration, backed by a firming domestic freight market, a clean balance sheet and a credible M&A runway. The 100% EPS growth and 79% EBITDA surge, however, are flattered by an easy prior-year comparison, disaster-relief charters and geopolitical rate support that management itself expects to fade eventually. The investment case now depends less on proving the recovery and more on whether domestic brokerage, the agent program and acquisitions can sustain growth as those tailwinds normalize.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-13 | |
| Oct-07 | |
| Oct-06 | |
| Sep-15 | |
| Sep-15 | |
| Sep-14 | |
| Sep-14 | |
| Sep-08 | |
| Aug-31 | |
| Aug-10 |
