P3 Health Swings To A Profit And Lifts Its EBITDA Floor, But Rising Medical Costs And One-Time Items Cloud The Quality Of The Quarter
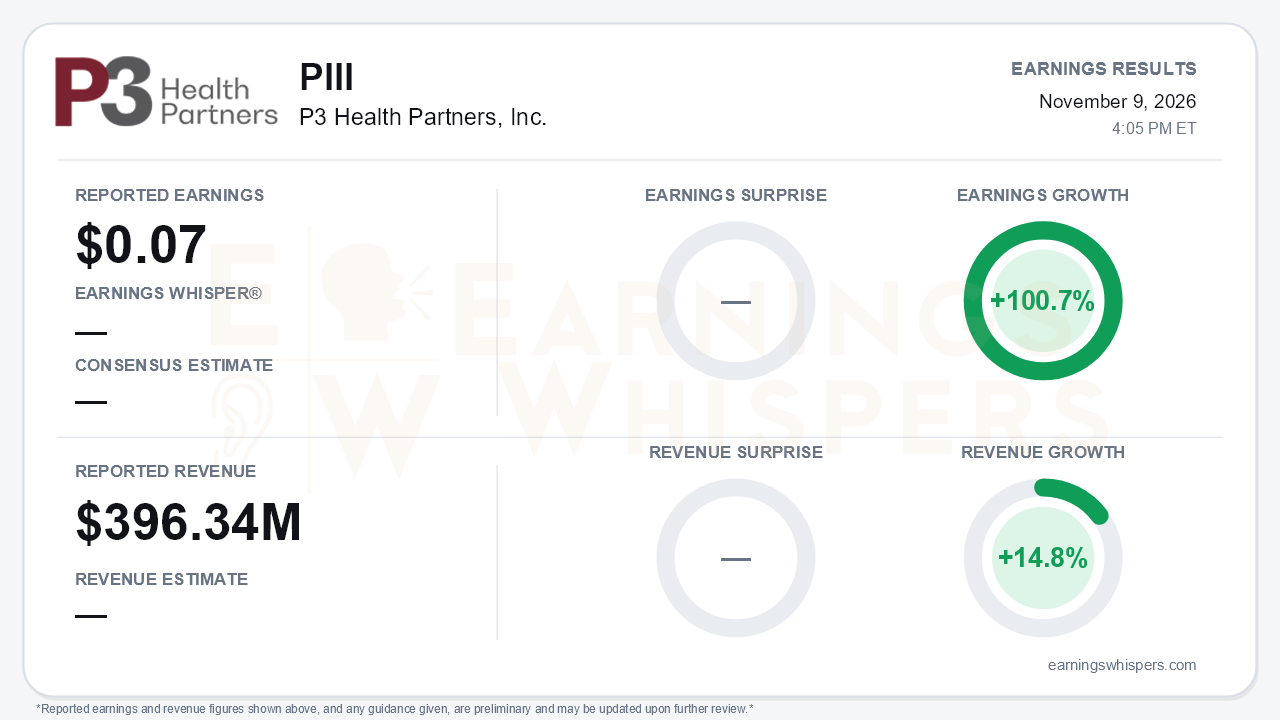
P3 Health Partners (NASDAQ: PIII) reported diluted earnings of $0.07 per share for the September quarter, compared with a loss of $9.67 per share a year earlier. That is a 100.7% year-over-year improvement. Revenue rose 14.8% to $396.34 million. No consensus estimate or Earnings Whisper was available, so the quarter cannot be framed as a beat or a miss. The swing is still striking: net income of $30.8 million replaced a $69.5 million loss, and adjusted EBITDA of $20.9 million replaced a $45.9 million loss. Management also raised the low end of its full-year adjusted EBITDA guidance. That is the central tension: the year-over-year turnaround is real, but the sequential trend in medical costs turned against the company for the first time this year.
The quality of the quarter deserves scrutiny.
- **One-time items:** Roughly $12 million of the $21 million in adjusted EBITDA came from one-time items. These were about $7 million from a favorable 2025 CMS ACO reconciliation and a roughly $5 million non-cash ACO joint-venture liability release.
- **Medical margin:** Excluding payer settlements and prior-year development, medical margin was $35.0 million, or $111 PMPM. The headline figure was $43.9 million, or $140 PMPM.
- **GAAP support:** GAAP results drew support from a $28.0 million premium deficiency reserve release, a $7.6 million warrant mark-to-market gain and $5.3 million of other income.
- **Preferred dividends:** Cumulative preferred dividends of $15.2 million, on preferred stock carrying 13.5% to 19.5% coupons, absorbed nearly all of the controlling-interest profit. Net income attributable to Class A shareholders was just $451,000, and the nine-month result remains a $0.13 per-share loss.
- **Revenue mix:** Capitated revenue grew more modestly, to $366.3 million from $341.6 million. Other revenue jumped to $30.1 million from $3.7 million and drove much of the headline gain.
The call sharpened the picture. Revenue growth has accelerated: 3.5% in Q1, 8% in Q2 and 15% in Q3. Capitated revenue per member rose about 18%, versus roughly 15% earlier in the year. That came even as at-risk membership fell 9% to about 105,000 under the company's deliberate network and payer rationalization.
Cost performance moved the other way. Adjusted medical loss ratio jumped to about 90.6% from 85.6% in Q2 and 85.2% in Q1. Year-to-date Medicare Advantage cost favorability versus 2025 narrowed to 0.7% from about 1.8% at midyear, which implies a markedly higher third-quarter run rate. The pressure came from outpatient and professional services and cardiovascular procedures, concentrated in Nevada. Medical margin per member fell to $140 from $311 in Q2. Reported adjusted EBITDA dropped to $21 million from $54 million.
Underlying EBITDA excluding one-time items edged up to about $10 million, from roughly $9 million and $8 million in the prior two quarters. Management's tone remained confident, but the emphasis shifted from celebrating cost-trend differentiation to repairing it.
The guidance raise is less generous than it looks. The low end moved to $90 million from $80 million, but the $110 million top end was unchanged. The new $100 million midpoint sits just below the $101 million already booked year to date, implying roughly breakeven to slightly negative reported EBITDA in Q4. Adjusted operating expense is also climbing, from $25 million in Q1 to $32 million in Q2 and $35 million in Q3, as the company funds the Nebraska build and data and clinical investments.
Management did offer new reasons for optimism:
- a quantified, roughly $200 million multi-year value-creation opportunity within the existing membership, with detail promised alongside 2027 guidance;
- a new Chief Clinical Officer, Dr. Mike Milley, and a new medical economics function;
- a pipeline of 60-plus mid-sized Medicare Advantage plans targeted for the Nebraska-style delegated-to-risk model.
Operating indicators such as inpatient-to-observation conversion, which rose to 34% from 24%, and quality scores improved. Visibility on 2027 membership, however, was deferred until after open enrollment.
The balance sheet remains a live concern for bears.
- **Liquidity:** Cash rose to $43.9 million from about $21 million at Q2. That still compares with $84.4 million of debt classified as current.
- **Cash burn:** Operating cash flow was a $90.1 million outflow through nine months, as the company paid down claims and health-plan settlements.
- **Funding:** Liquidity was sustained by preferred stock and warrant issuance at very expensive terms.
- **Risk factors:** The release's risk factors still cite going-concern and covenant-compliance considerations.
Investor sentiment, current price and technical readings were not available for this report. The only reference point is a $12.70 opening price after the August release, so the market's reaction to this quarter cannot be assessed from the supplied data.
The bottom line is that P3 has completed a dramatic year-over-year turnaround and continues to nudge guidance higher. However, the third quarter exposed the first meaningful crack in its medical cost advantage, and roughly half of reported EBITDA came from nonrecurring items. Accelerating revenue per member and a credible value-creation roadmap keep the story alive. The Q4 guidance math, rising operating expense and an expensive capital structure mean cost-trend repair has replaced cost-trend outperformance as the key thing investors need to see.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Oct-22 | |
| Oct-12 | |
| Aug-10 | |
| Aug-07 | |
| Jul-21 | |
| May-15 | |
| May-14 | |
| May-13 | |
| Apr-16 | |
| Mar-26 | |
| Mar-25 | |
| Mar-13 | |
| Dec-02 |
