HF Foods Misses As Fuel Costs And One-Time Fees Swamp A Searay-Aided Top Line
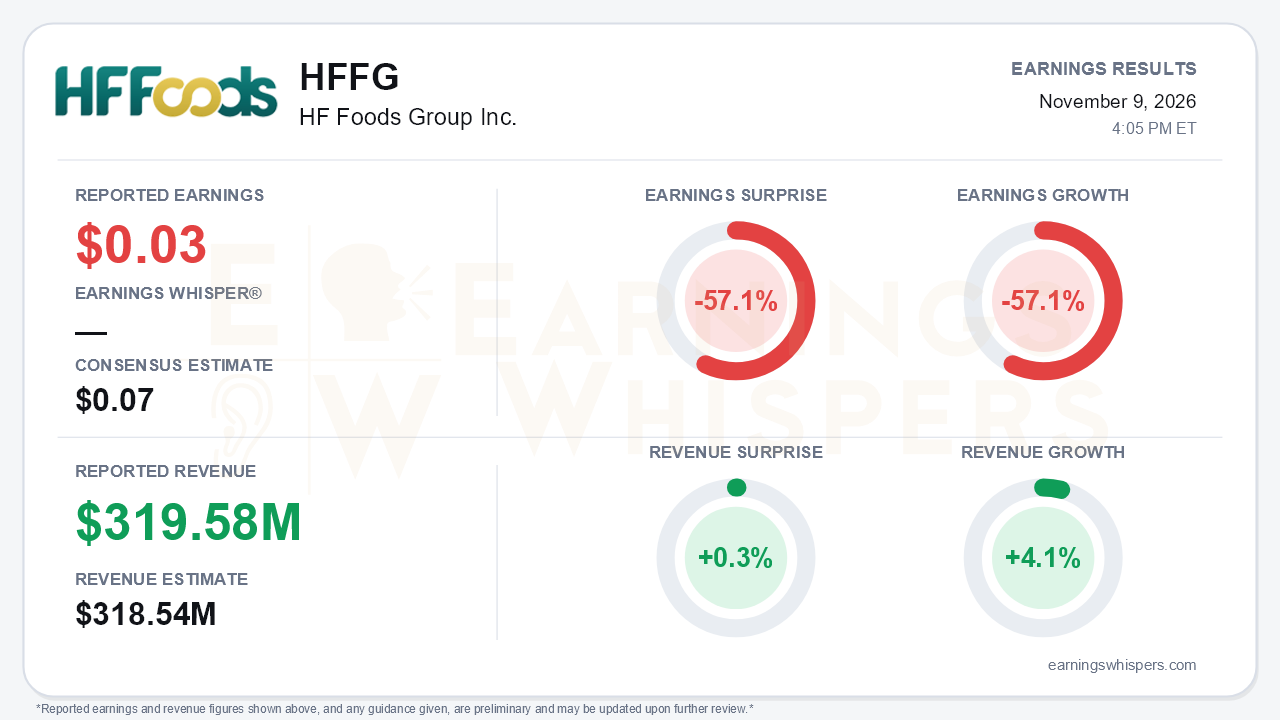
HF Foods Group (NASDAQ: HFFG) delivered a quarter in which the top line and the bottom line moved in opposite directions. Revenue rose 4.1% year over year to $319.58 million, edging past the $318.54 million consensus by 0.3% and marking a seventh straight quarter of year-over-year growth. Earnings went the other way. Earnings Whispers puts reported EPS at $0.03, missing the $0.07 consensus by 57.1% and down 57.1% from a year ago. The company's own adjusted figure was $0.04 versus $0.08, so even on management's preferred basis profit per share halved. On a GAAP basis the net loss widened to $4.2 million, or $0.08 per share, from $0.9 million, a sharp reversal from second-quarter GAAP income of $2.6 million. The central tension is that the distributor is growing and adding a margin-accretive acquisition, but it is not converting that growth into profit.
The quality of the revenue beat deserves scrutiny. Searay Foods, acquired effective August 31, contributed $4.2 million in its first month, which leaves organic growth near 2.7%. Revenue also slipped sequentially from Q2's record $323.8 million. Gross margin improved to 16.7% from 16.4%, reversing contractions in Q1 and Q2. However, part of that gain came from IEEPA tariff refunds alongside Seafood volume and Searay mix, and the refunds should not be extrapolated. Below gross profit, distribution, selling and administrative expense jumped 11.9% and rose to 17.3% of revenue from 16.1%. That pushed operating income to a $1.8 million loss from a $1.1 million profit. Adjusted EBITDA fell 6.3% to $11.0 million, and its margin shrank to 3.4% from 3.8%.
The deterioration is accelerating. Adjusted EBITDA rose 3.8% in Q1, fell 2% in Q2 and fell 6.3% in Q3, and the margin dropped from 4.2% in Q2 to 3.4% now. Management said more than half of the DS&A increase came from non-recurring professional fees tied to the revolver amendment, property refinancing, the Searay deal and legal matters. The reconciliation supports that: other non-routine expense was $3.7 million, versus $0.3 million a year ago. Most of the remainder was fuel. Diesel ran roughly 31%, 45% and 64% above prior-year levels in July, August and September, a headwind of about $1.4 million in the quarter and $3.2 million year to date. A fuel surcharge program is now in place across the customer base. By design, however, it only partially recovers the cost, so margin pressure could extend into 2027.
Management's tone shifted noticeably. After upbeat Q1 and Q2 calls, leadership acknowledged that profitability fell short. It reiterated its 4.5%-5%+ adjusted EBITDA margin target but declined to frame 2027 because fuel prices are uncertain. The earlier call for low-single-digit adjusted EBITDA growth in 2026 now looks difficult, with nine-month adjusted EBITDA of $34.7 million down 1.8%. Execution slippage also showed up elsewhere. Charlotte permitting was pushed out for a third time, now to year-end 2026, and cross-selling is now described as a three-to-five-year build paced by capital, a more gradual timeline than before.
The constructive case has real substance. Searay earned a mid-teens adjusted EBITDA margin in its first month on a roughly 5x EBITDA purchase price, and Q4 will be its first full quarter. Planned catalysts include a Los Angeles direct-import operation and a Canadian M&A pipeline that management called vibrant. Nine-month operating cash flow climbed to about $24 million from $4.5 million on better inventory management; the release cites $24.1 million and the call $23.6 million. The upsized $140 million revolver extends maturities to 2031 and 2036. The offset is leverage. The credit line balance rose to $80.0 million from $55.8 million at year-end, long-term debt reached $118.1 million, and quarterly interest expense increased to $3.4 million from $2.9 million.
Investor sentiment improved substantially ahead of the report, rising from -0.70 to -0.24. That shows less pessimism, but sentiment remains negative. The share price did not follow. As of November 6, the stock was $1.47, down 11.4% from the $1.66 open after the August report. It sat 17.2% below its 200-day moving average and only 3.5% above the inter-earnings low of $1.42 set October 30, having given back the move to $1.95 in mid-August. The price and AVWAP trend readings remain negative, while momentum is positive.
The bottom line is that HF Foods is executing on growth and M&A but losing ground on profitability. The miss is partly explained by fees management calls non-recurring, but fuel, rising interest costs and a softer organic pace are more durable problems. Investors entered the quarter less bearish, yet the stock was trading near its lows. A clean first full quarter from Searay and evidence that surcharges are recovering fuel costs are now required to rebuild confidence in the margin target.
Read our earnings preview for HF Foods Group Inc.: https://www.earningswhispers.com/article/HFFG/22631
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| Nov-02 | |
| Oct-26 | |
| Sep-18 | |
| Sep-03 | |
| Aug-11 | |
| Aug-10 | |
| Jul-27 | |
| Jul-23 | |
| Jun-22 | |
| Jun-11 | |
| May-19 | |
| May-12 | |
| May-11 |
